
Glencore: clouds are gathering over the metals market
Related content
FX - Technical Analysis
Following the correction seen over the past month, the U.S. dollar has regained strength against its major currency counterparts. The EUR/USD exchange rate has broken below the 1.1108 level, confirming the continuation of the downward trend. The dollar is also in a favorable position against the British pound, with the exchange rate potentially extending its move after breaking below the lower boundary of a broader trading range.In the case of EUR/HUF, the recent narrowing price action may soon come to an end, potentially leading to an upside breakout from the triangle pattern. The Hungarian forint had already been showing signs of depreciation against the U.S. dollar earlier, and this trend may continue with the formation of new swing highs. USD/JPY broke out to the upside from a narrowing range two weeks ago; however, the breakout has not yet been accompanied by particularly strong momentum. As for EUR/CHF, following a recent modest correction, the downward direction may once again come into focus.
Hungary: MNB decided to keep its policy rate at 5.5%, but some Monetary Council members voted for a cut
At its November meeting, the MNB’s Monetary Council kept its base rate unchanged at 5.50%. According to the central bank’s assessment, leeway of the monetary policy (in terms of monetary easing) has improved as a consequence of the good market perception of the government’s recent budget plans and mitigating energy prices after the US midterms, some members of the Monetary Council even voted for a rate cut, but were outnumbered this time.
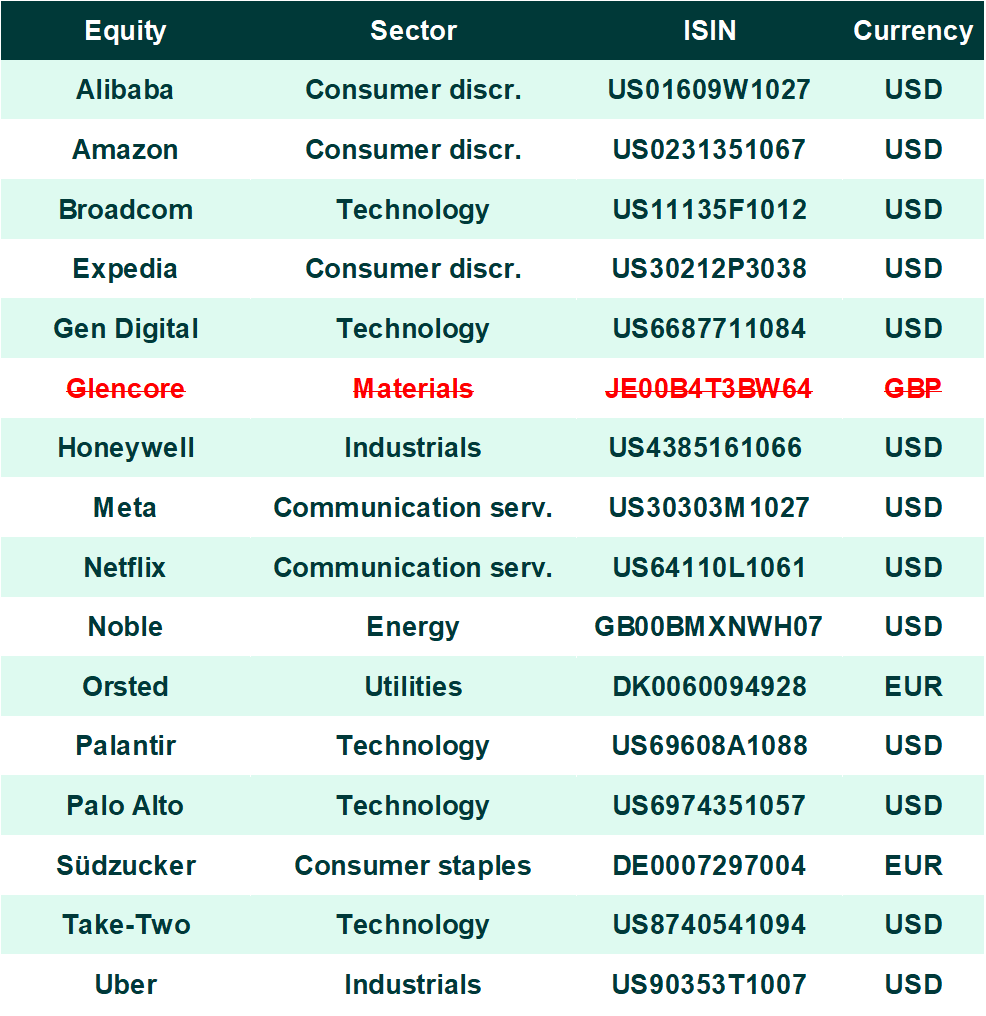
Glencore, the commodities giant, has achieved excellent financial results so far in 2026, but in our view, the outlook has taken an unfavorable turn, especially in the metals and mining sector, where both copper and zinc prices have been trending downward in recent weeks. Among other factors, weaker Chinese economic data and deteriorating AI sentiment may have played a role here, as data centers use significant amounts of copper. At the same time, although coal prices have improved significantly this year, we would have expected even higher prices given the tight conditions in the energy market. Accordingly, we are removing Glencore from our Equity Top Pick List. The stock has provided a return of about 26% including dividends since we added it to our list last December despite the decline in recent weeks.
Excellent financial performance, but...
Glencore, one of the world’s largest diversified mining companies, has had a particularly strong year so far in terms of financial performance, and this might apply for the whole year as well. The company does not publish Q1 and Q3 financial results and only reports production figures for these periods. In the first half of the year, however, revenue was up 49% YoY, and EBITDA was up 86%. Net income was $4.41 billion, compared with a loss of $655 million in the first half of last year. Operating cash flow also showed a similarly strong improvement during the same period.
The excellent performance so far this year can be attributed to several factors including high metal prices (e.g., copper, zinc), and the trading and logistics division has also been exceptionally strong in 2026, which successfully capitalized on various trading opportunities arising from the war in Iran, particularly with regard to oil. According to management forecasts, the trading and logistics division’s annual operating profit could exceed $5 billion this year. By way of comparison, the previous long-term annual average range was $2.3-$3.5 billion.
At the same time, coal prices have also improved significantly since the beginning of the year, and there may still be room for further increases due to the tight energy market conditions. The logic is that when natural gas prices are high, then it may be worthwile to substitute that with relatively cheaper coal when it is possible (i.e., if there is available unused capacity). Taking this context into account, we view coal's performance this year as still somewhat disappointing for now, despite the strong YTD rise.
Unfavorable metals market outlook
In our view, the bigger issue regarding the outlook is not with coal, but rather with metals, where trends seem less favorable. On the one hand, the surge in energy and raw material prices (e.g., fuel, explosives, sulfuric acid, etc.) caused by the war in Iran is putting cost-side pressure on mining companies. On the other hand, the protracted conflict in the Middle East, weaker Chinese economic data, and the obvious deterioration in AI sentiment could cause headaches on the demand side of the metals market. As a result, profit margins may narrow, although this year is still likely to be strong in terms of financial results (on an annual basis).
On a corporate level, Glencore can be considered one of the best global mining companies, with low-cost production and a well-diversified portfolio of assets, both geographically and in terms of commodities. In addition, the growth outlook on the production side is not bad either, as the company has significant copper projects. The only negative aspect on a company-specific level seems to be the ongoing legal dispute between Glencore and its iron ore trading partner (Radiant World).
Overall, we believe that the increasingly protracted war in Iran and deteriorating AI sentiment could keep pressure on the metals markets in the coming months, which is not favorable for the relatively more cyclical mining companies, including Glencore. However, thanks to its strong and diversified commodity asset portfolio, the company may continue to relatively outperform the broader mining sector (i.e., decline less than the others). Of course, it cannot be ruled out either that the conflict in the Middle East will be resolved in the near-term or that investor concerns regarding data centers may prove to be exaggerated, but for now, it might be worth being a bit cautious.
Accordingly, we are removing Glencore from our Equity Top Pick List. The stock, since its addition last December, has risen by about 26%, including dividends despite the apparent weakness in recent weeks. Approximately 21% of the total return is capital appreciation and 5% is dividend related.
Equity Top Pick List (updated)
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more