
Glencore: excellent performance, higher dividend
Related content
A new world may be dawning for Brazil
Elections are coming up in Brazil in October: of the two candidates who appear to be the frontrunners, current President Lula’s lead over his main challenger, Flávio Bolsonaro, appeared to be waning according to opinion polls. The race is not yet decided, and the stakes are high, as the next president will face, among other tasks, the challenge of allaying market participants’ concerns about Brazil’s growing national debt. Based on initial market reactions, investors are responding positively to Flávio Bolsonaro’s narrowing of the gap with Lula in the polls; or, to put it another way, market participants appear to be placing their trust in a stricter fiscal policy and spending cuts than before, as well as in the possibility of lower interest rates resulting from this and less government intervention. There is still roughly one month left until the Brazilian elections, and the next president will set the course for both Brazil and the local stock market in the coming period.
Hungary: Inflation in August was 1.3% YoY much below the inflation target, but service inflation is still high
Hungary's headline inflation increased to 1.3% year-on-year in August from 1.2% in July. The published data was lower than the consensus and our forecast (both 1.4%). The lower-than-expected inflation was due to above expectation core inflation but lower than expected fuel inflation and lower increase of administered prices.
Glencore, one of the world’s largest diversified mining companies, released its H1 earnings report yesterday, which showed strong results. The company exceeded analysts’ expectations across all key financial lines, and a significant improvement is also evident on an annual basis. Higher commodity prices greatly contributed to this performance, and Glencore also took advantage of the trading opportunities created by the war in Iran. In light of this, management has increased the dividend and announced a share buyback program. For now, we are keeping the stock on our Equity Top Pick List.
Excellent performance
Glencore, one of the world’s largest diversified mining companies, released its H1 earnings report yesterday, which showed strong results. The company exceeded analysts’ estimates in terms of revenue, EBITDA, and net income as well.
- Revenue was 174 billion USD in the first half of the year, up 49% YoY and 19% higher than analysts' expectations.
- EBITDA was 10.1 billion USD, up 86% YoY and 3% higher than the consensus estimate.
- Net income came in at 4.41 billion USD, compared with last year's loss of 655 million USD, and the company exceeded analysts' expectations by 37%.
A similarly significant improvement can be seen in operating cash flows, which totaled 8.1 billion USD in the first half of the year, compared with 3.1 billion USD last year.
Strong trading and metal mining results
Looking at the individual segments, it is clear that both raw materials production and the trade and logistics business contributed to the favorable results. In relative terms, raw materials production accounted for 64% of Group-level EBITDA, while trade and logistics accounted for 36%.
EBITDA in the raw materials production segment was 72% higher YoY, with metal mining performing exceptionally well, while coal production also showed a significant improvement (+35% YoY). Copper production volume rose 15% YoY to 397,000 metric tons in the first half of the year, while zinc production fell by 21%. Production of coking coal used in steel manufacturing also declined (-14% YoY), while thermal coal production remained largely flat. Despite the mixed production picture prices for most raw materials were significantly higher on a YoY basis, which gave a large boost to earnings.
EBITDA for the trade and logistics division rose by 118% YoY, as this segment was able to capitalize on various trading opportunities arising from the war in Iran, particularly in the case of oil. By way of comparison, the company’s long-term annual EBIT range is between 2.3-3.5 billion USD, while in the first half of this year alone, it has already approached 3.3 billion USD due to geopolitical tensions.
Glencore has made only minor adjustments to its production forecasts for this year (thermal coal production is expected to be slightly higher, while coking coal volumes are expected to be slightly lower). Annual copper production is expected to range between 810,000-870,000 tons (vs. 852,000 tons last year), while zinc production is expected to be between 700,000-740,000 tons (vs. 969,000 tons last year). Thus, there has been no change in the production forecasts for the two major industrial metals compared to previous figures. In addition, the company expects that the annual copper production target of 1 million tons will remain achievable by 2028.
In light of the strong half-year results, management has decided to increase the previously proposed dividend of 17 cents per share for this year to 25.5 cents and to repurchase shares worth 500 million USD. This amounts to a total shareholder payout of approximately 3.5 billion USD this year. The dividend is being paid in two installments; the first has already been paid (June, 8.5 cents per share), while the second installment (17 cents following the current top-up) will be paid in September (representing a dividend yield of approximately 2.2% on the unpaid portion).
Finally, it is worth noting that, in addition to its current listing on the London Stock Exchange, Glencore is expected to list on the Australian Securities Exchange (ASX) as well, which could take place by October 2026. This move could also help attract more foreign institutional investors.
Valuation and debt
The company's net debt stood at 10.2 billion USD at the end of the first half of this year, bringing the net debt / EBITDA ratio to around 0.5, which can be considered relatively low.
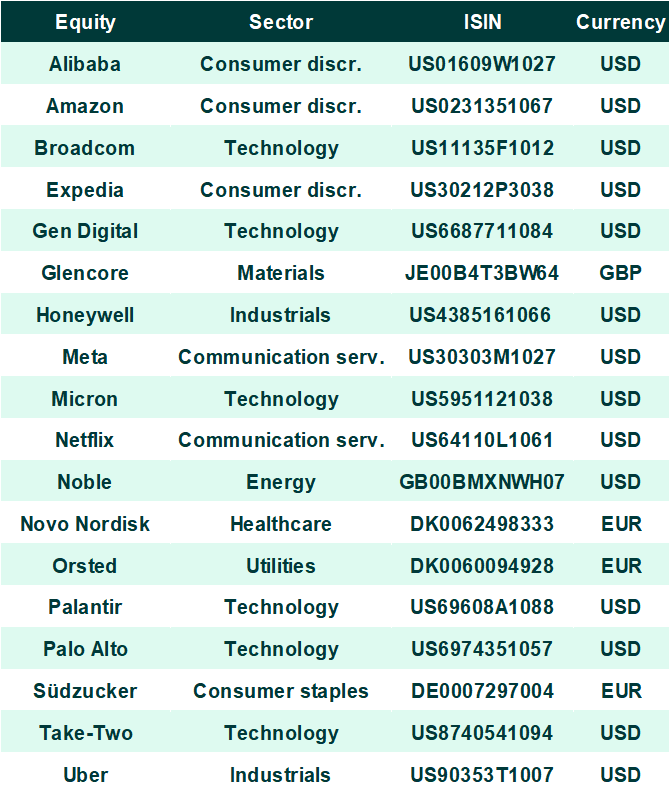
Glencore does not have an expensive valuation as based on this year’s expected EBITDA, the EV/EBITDA ratio stands ~6x, while based on the profit expected for 2026, the P/E ratio is ~13.9x. We note, however, that the company’s performance is highly cyclical, meaning that commodity prices have a particularly significant impact on its earnings. For now, despite the war in Iran, copper prices have remained high, and coal prices have also risen, but these could easily change depending on how the conflict in the Middle East unfolds. For the time being, we are keeping the stocks on our Equity Top Pick List.

Equity Top Pick List (updated)
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more