
Südzucker: little sweet, little sour earnings
Related content
One Step Closer to a New World: Brazil
Elections were held in Brazil in early October, during which Flávio Bolsonaro, the challenger to incumbent President Lula, performed better. The second round of the presidential election will follow in late October, when it will be decided which of the two will become Brazil’s next president. Currently, Flávio Bolsonaro appears to be the favorite to win, and based on market reactions, investors may already started pricing in this scenario. If Flávio Bolsonaro is elected president, it could pave the way for the fiscal turnaround anticipated by market participants, and relations between Brazil and the United States could also improve, which over time could even lead to lower Brazilian tariffs.
Vistra: A Potential Winner of the AI Energy Demand Surge
Major U.S. indices are trading near their all-time highs, but have not yet broken out toward new peaks. Meanwhile, it is rare to find stocks that are breaking out and rising after periods of consolidation or correction. This week, Vistra from the utilities sector stood out. The company is one of the largest electricity producers in the U.S., with significant nuclear capacity, and is benefiting from the growing electricity demand of AI data centers.
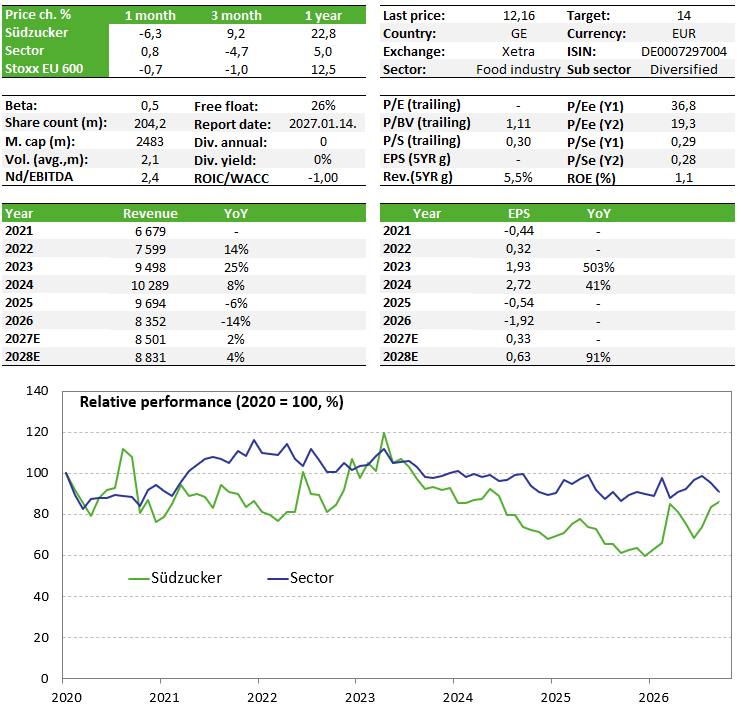
Südzucker, which is one of the world’s largest sugar producers and a leading player in European biofuel production, released its latest interim report, which contained both pleasant and slightly negative surprises. On the one hand, there has been a significant improvement in financial performance on an annual basis, three out of five business segments posted excellent results, and losses in the sugar production division also narrowed thanks to cost-efficiency measures. On the other hand, management raised its annual forecasts only moderately despite strong business performance, which may have disappointed some investors. However, in our view, the outlook for the sugar market remains favorable, so the sugar production segment’s profitability may improve in the coming period. Overall, we are keeping the stock on our Equity Top Pick List.
Quarterly earnings
The company’s financial H1 (March–August) showed a generally positive performance on a YoY basis. Although revenues remained largely flat at around 4.19 billion EUR, group-level EBITDA rose by more than 60% to over 300 million EUR compared to the first half of last year, and at the same time, the EBITDA margin increased from 4.5% to 7.2%. The operating profit of 153 million EUR is more than three times last year’s 42 million EUR, while the net income of 61 million EUR represents a significant improvement over the previous 60 million EUR loss. Operating cash flow was similarly strong, jumping by more than 70% to 441 million EUR on a YoY basis.
On a segment level we can see a fairly favorable picture as well:
- Special products (frozen and refrigerated pizzas, packaged products): revenue increased by 5%, while EBITDA rose by nearly 22% to 140 million EUR.
- CropEnergies (ethanol production / biofuels): the business unit is performing exceptionally well this year due to higher fuel prices, which have also driven up biofuel prices. Revenue here rose by 9%, while EBITDA jumped from 4 to 68 million EUR on a year-over-year basis (a 17-fold increase).
- Starch: revenue declined slightly here (-4%), but EBITDA nevertheless rose by 24% to 36 million EUR.
- Fruits: this segment performed relatively weaker in the first half of the year, EBITDA fell by 4.6% to 83 million EUR, despite a rise in revenue of more than 4%.
- Sugar production: although the segment continues to struggle - with revenue down 8.6% - the EBITDA loss was reduced to 24 million EUR, compared with last year’s loss of 46 million EUR, thanks to cost-efficiency measures.
Overall, three out of five segments showed significant improvement in fiscal H1 on a YoY basis, while losses in the sugar production division decreased significantly, and the fruit division’s performance weakened only slightly.
Business outlook
For the current fiscal year, management now expects revenue of 8.3–8.7 billion EUR, up from the previous range of 8.1–8.5 billion EUR (+200 million EUR on a midpoint basis). Although management did not raise the upper limit of the EBITDA target range, they narrowed the range upwards, so it is now expected to be between 540 and 680 million EUR (instead of 480–680 million EUR), which represents an increase of 30 million EUR on a midpoint basis.
The initial negative investor reaction to the results was likely due to a less-than-expected improvement in the EBITDA range (despite significantly improving business performance, the range has only been narrowed upwards rather than raised). In our view, this may be partly due to management’s more cautious approach in light of the rapidly changing situation in the Middle East, which could also significantly impact biofuel prices. Another negative factor is that, due to a severe drought, European sugar beet yields will be lower, and the area under cultivation is also smaller on a year-over-year basis, which will result in lower sugar production volumes (lower capacity utilization). At the same time, the company expects sugar prices to improve in the second half of the year (the segment’s EBITDA is expected to range between -60 million EUR and +40 million EUR).
Sugar market
Although Südzucker’s sugar production segment is still underperforming (though signs of improvement are visible thanks to cost-efficiency measures), the international price of sugar has risen significantly in recent months (up 36% since the beginning of the year and more than 50% since the lows in April). This is partly due to the fact that Brazil, the world’s largest sugar producer, has redirected a significant portion of its sugarcane production toward ethanol (biofuel) production instead of sugar production because of higher fuel prices. This is primarily due to the surge in energy prices caused by the war in Iran. For now it remains unclear how this situation will be resolved, so higher fuel prices may persist for the time being.
On the other hand, India, the world’s second-largest sugar producer, has faced difficulties in recent months due to the Iran war and a lack of rainfall. This year’s summer monsoon season (June–September) was particularly weak, with rainfall nearly 13% below the long-term average (the weakest since 2015). This, in turn, could negatively affect sugarcane yields there. The El Nino weather phenomenon, which is expected to intensify in the coming months, could cause further issues in India and Brazil, although it is difficult to assess the net effects.
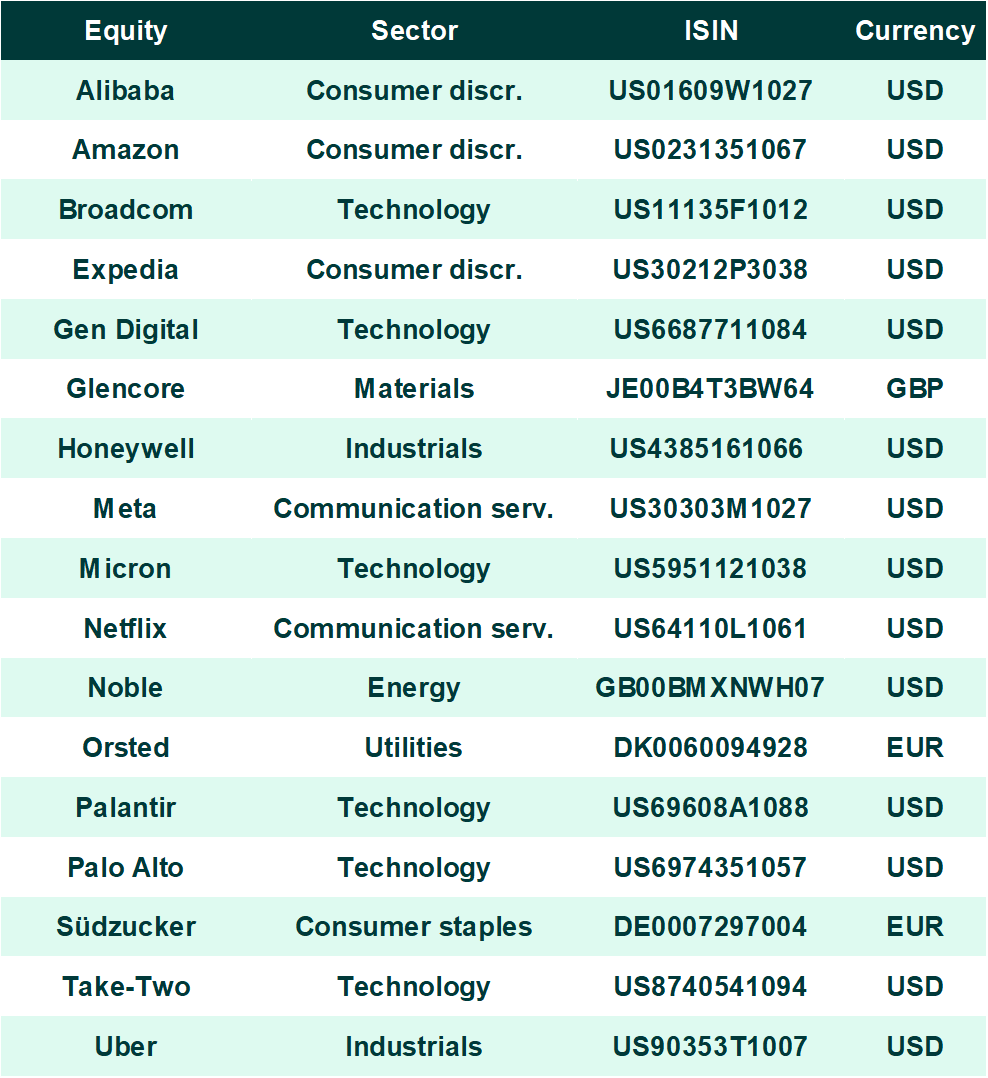
Overall, the outlook for the sugar market continues to look favorable. The war in Iran and extreme weather conditions may support current higher prices. In our view, this will eventually be reflected in the profitability of Südzucker’s sugar production segment, while the ethanol production division is likely to continue posting strong results thanks to higher fuel prices. As a result, we are keeping the company’s shares on our Equity Top Pick List.
Equity Top Pick List (updated)
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more