
Noble: No Clear Signs of Improvement Yet
Related content
Glencore: clouds are gathering over the metals market
Glencore, the commodities giant, has achieved excellent financial results so far in 2026, but in our view, the outlook has taken an unfavorable turn, especially in the metals and mining sector, where both copper and zinc prices have been trending downward in recent weeks. Among other factors, weaker Chinese economic data and deteriorating AI sentiment may have played a role here, as data centers use significant amounts of copper. At the same time, although coal prices have improved significantly this year, we would have expected even higher prices given the tight conditions in the energy market. Accordingly, we are removing Glencore from our Equity Top Pick List. The stock has provided a return of about 26% including dividends since we added it to our list last December despite the decline in recent weeks.
FX - Technical Analysis
Following the correction seen over the past month, the U.S. dollar has regained strength against its major currency counterparts. The EUR/USD exchange rate has broken below the 1.1108 level, confirming the continuation of the downward trend. The dollar is also in a favorable position against the British pound, with the exchange rate potentially extending its move after breaking below the lower boundary of a broader trading range.In the case of EUR/HUF, the recent narrowing price action may soon come to an end, potentially leading to an upside breakout from the triangle pattern. The Hungarian forint had already been showing signs of depreciation against the U.S. dollar earlier, and this trend may continue with the formation of new swing highs. USD/JPY broke out to the upside from a narrowing range two weeks ago; however, the breakout has not yet been accompanied by particularly strong momentum. As for EUR/CHF, following a recent modest correction, the downward direction may once again come into focus.
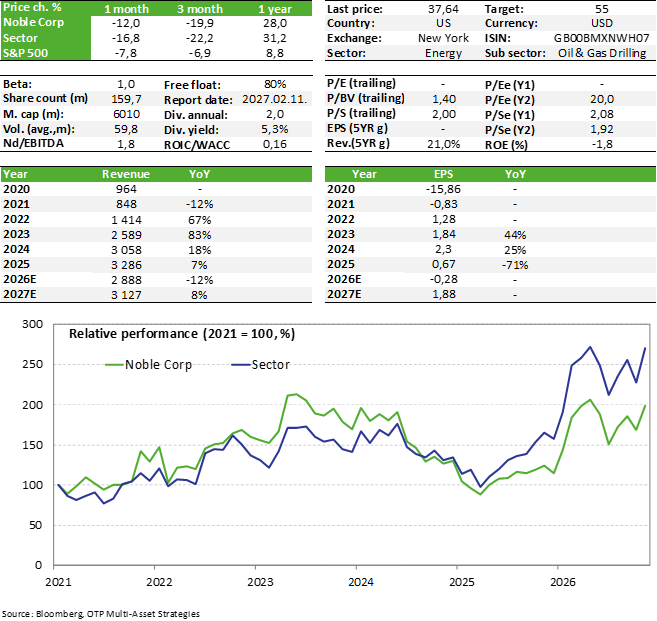
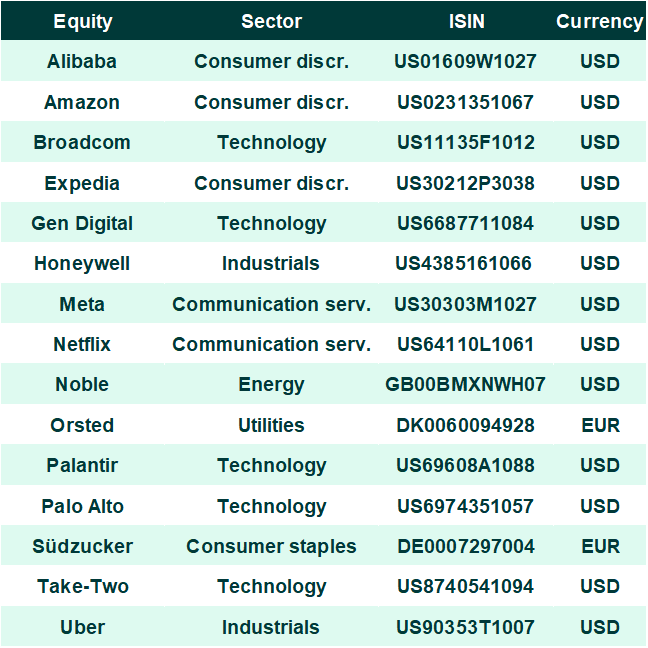
Following a disappointing second quarter, Noble’s third-quarter results also fell short of expectations. While revenue came in ahead of analysts’ forecasts, the company underperformed on both EBITDA and earnings. Management further narrowed its full-year guidance range, although the previously communicated targets remain achievable. Overall, there are no large issues: dividend payments can be maintained for now and liquidity is adequate, but an improvement in market conditions would be increasingly important. Management currently expects a more meaningful recovery in the offshore drilling market from the second half of 2027 onward. For now, we are keeping the stock on our Equity Top Pick List, but if the anticipated market turnaround is significantly delayed, we may reconsider our position.
Quarterly earnings
Noble reported its third-quarter results this week, and the figures once again came in weaker than expected. While revenue exceeded analysts’ forecasts by roughly 2%, it was still down approximately 9% year over year. At the same time, analysts had been expecting EBITDA of $225 million and earnings per share of $0.23, whereas Noble delivered $201 million in EBITDA (an 11% miss versus expectations) and a loss of $0.57 per share for the quarter.
Operating cash flow remained broadly in line with the previous quarter at around $145 million (bringing the total for the first nine months of the year to $562 million), while capital expenditures amounted to $192 million ($500 million for the first three quarters combined). As a result, Noble generated negative free cash flow of $48 million during the quarter, although free cash flow for the first nine months of the year remained positive at $62 million. That said, this is still insufficient to cover the company’s dividend commitments, which amount to roughly $80 million per quarter. The quarterly dividend will remain unchanged at $0.50 per share in the fourth quarter, implying an annualized dividend yield of approximately 4.2%. For the time being, there are no major concerns, as Noble ended the third quarter with $337 million in cash on its balance sheet. It is worth noting, however, that liquidity was boosted by a $206 million asset sale completed in the first quarter. As things stand, the dividend appears secure in the near term, but operating performance will need to improve over the next few quarters for the current payout level to remain sustainable over the longer term.
In light of the third-quarter results, management further narrowed its full-year guidance ranges. Revenue is now expected to come in between $2.85 billion and $2.90 billion (previously $2.8 billion to $2.9 billion), while EBITDA is projected to reach $850-900 million, compared to the prior range of $850-925 million. At the same time, full-year capital expenditures are now expected to total $680-705 million, up from the previously guided $615-665 million, representing roughly a $50 million increase at the midpoint. For the fourth quarter, this implies capital spending of approximately $190 million, broadly in line with the third quarter, and EBITDA in the range of roughly $160-210 million.
The company’s gross debt stood at $1.89 billion at the end of September, while net debt totaled $1.55 billion, representing a modest increase compared to the previous quarter. While leverage remains at a manageable level, equivalent to roughly 1.8x net debt-to-EBITDA based on this year’s weaker expected performance, the trend is nonetheless moving in an unfavorable direction. On the liquidity side, Noble maintains a solid position, with $337 million in cash on hand and an additional $640 million revolving credit facility available to the company.
Fleet utilization showed modest year-over-year improvement in the third quarter, reaching 67%, compared with 61% in the same period last year. Looking at the underlying segments, utilization in the deepwater fleet remained broadly stable at 63% versus 65% a year earlier, while the jack-up segment posted stronger figures, with utilization rising to 79% from 54%. However, this improvement should be viewed in the context of the asset disposals previously discussed, as the utilization rate is now spread across a smaller number of rigs. Average dayrates in the deepwater segment declined modestly, while rates for jack-up rigs increased slightly. Noble’s backlog currently stands at $6.7 billion, with 72% of available drilling days for 2027 already contracted, while 55% of available days for 2028 have also been booked. In the previous quarter, those figures stood at 65% and 51%, respectively, indicating continued progress in securing future work despite the still-challenging market environment.
Valuation
Noble trades at around 10x EV/EBITDA based on expected 2026 results, which is not particularly expensive. Based on 2027 estimates, the multiple falls to roughly 7.8x. The stock also trades at about 20x expected earnings for next year. However, offshore drilling is a highly cyclical business, so the valuation largely depends on whether the expected market recovery begins in the second half of 2027.
Overall, Noble’s results have been disappointing since the strong first quarter, although the weaker performance was largely expected given this year’s softer market environment. As such, the recent numbers do not come as a major surprise. We continue to believe there is no cause for serious concern at this stage. The current dividend appears sustainable for the time being, liquidity remains adequate, but an improvement in market conditions is becoming increasingly important. Management expects a more meaningful recovery from the second half of 2027, meaning the next few quarters could remain relatively weak. For now, we are keeping the shares on our Equity Top Pick List, but we would reconsider our position if the expected 2027 market recovery were to be significantly delayed. As a final positive note, the two Brazilian drilling rigs that were suspended in Q2 are now back in operation.
Equity Top Pick List (updated)
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more