
Investor Sentiment Reflects Cautious Optimism
Related content
The government crisis is over – what lies ahead for Romania?
Romania has experienced five turbulent months on the domestic political front. Nevertheless, after several prime ministerial candidates failed to secure parliamentary support, a new government was finally formed in late October. The Romanian equity market, which had performed strongly during the first half of the year, lost momentum towards the end of August and entered a downward correction in September. It then rebounded in October, partly reflecting the reduced risks of a snap election and a sovereign rating downgrade to below investment grade. While domestic political tensions have subsided, the BET index has yet to recover to the vicinity of its August peak. At the same time, Romanian equities no longer appear particularly inexpensive from a valuation perspective.
Commodities - Technical Analysis
Signs of a turnaround have emerged for gold and silver, and a strong upward move could trigger the next upward wave. A breakout above the key downtrend lines could also be on the horizon, which would further reinforce the positive turnaround. The price of oil has broken below the 100-day moving average, weakening the bullish outlook, and with the uptrend broken, it has entered a correction phase. Natural gas is showing a correction following a sharp decline, but has not yet managed to break through its downtrend line. Copper continues to trade within a wide range and is approaching the lower end of that range. Following a significant decline, wheat and corn prices have reached key support levels from which an upward correction—or even a new uptrend—is likely to begin.
In our Institutional Investor Survey, we are providing a unique opportunity for our institutional clients to share and gain insights on market expectations and sentiment. Our focus is on Hungarian assets in the context of regional and global trends. Here, we highlight the most notable insights.
Investor sentiment toward Hungarian equities remains firmly positive, although the latest survey shows a modest reduction in conviction. The share of outright bullish responses fell from 8% to zero, while neutral views increased from 16% to 24%. The results suggest that investors continue to expect the BUX to perform well over the next three months but see less potential for a strong rally after the market’s previous gains.
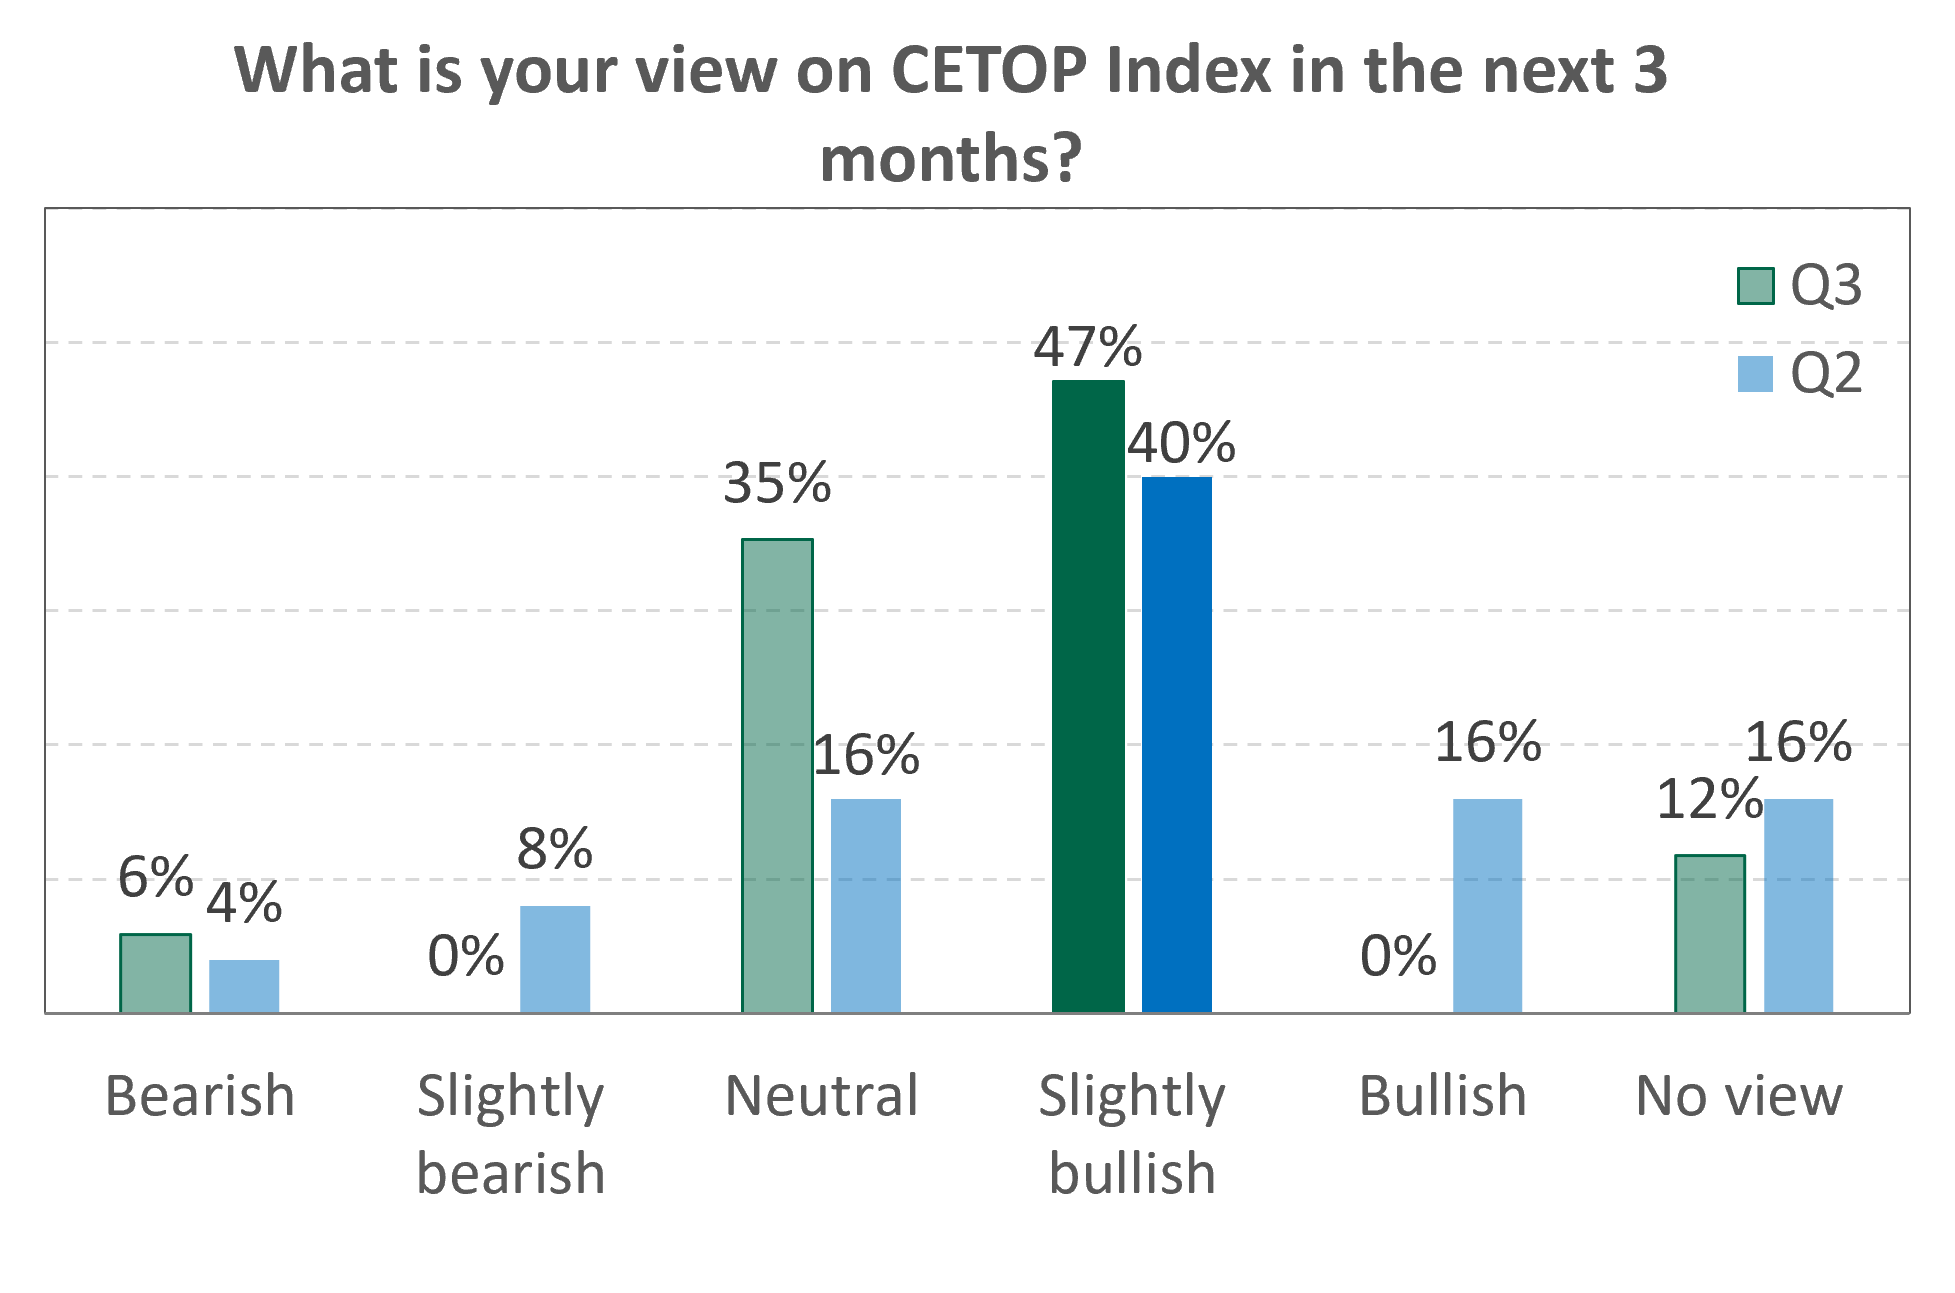
The outlook for the broader CETOP Index has become more balanced. Slightly bullish responses increased from 40% to 47%, making this the largest category. The CEE region has been able to weather the risks posed by rising energy prices relatively steadily so far this year, supported primarily by domestic consumption and investments aided by EU funds. The CEE equity market remains significantly cheaper than Europe despite a stronger earnings outlook. Corporate profits are expected to grow by 30% this year, roughly twice the European rate, while margins are near record highs. This combination makes CEE one of the most attractive options for investors seeking inexpensive growth without direct exposure to the AI theme.
Investor expectations for the forint have become more cautious since the June survey. The largest share of respondents, 65%, now expect EUR/HUF to trade between 360 and 370 over the next three months, compared with only 24% in the previous survey. Investors continue to expect a broadly stable forint but see less scope for further appreciation from current levels.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more