
Investor Sentiment Turns Constructive on Hungary
Related content
The government crisis is over – what lies ahead for Romania?
Romania has experienced five turbulent months on the domestic political front. Nevertheless, after several prime ministerial candidates failed to secure parliamentary support, a new government was finally formed in late October. The Romanian equity market, which had performed strongly during the first half of the year, lost momentum towards the end of August and entered a downward correction in September. It then rebounded in October, partly reflecting the reduced risks of a snap election and a sovereign rating downgrade to below investment grade. While domestic political tensions have subsided, the BET index has yet to recover to the vicinity of its August peak. At the same time, Romanian equities no longer appear particularly inexpensive from a valuation perspective.
Commodities - Technical Analysis
Signs of a turnaround have emerged for gold and silver, and a strong upward move could trigger the next upward wave. A breakout above the key downtrend lines could also be on the horizon, which would further reinforce the positive turnaround. The price of oil has broken below the 100-day moving average, weakening the bullish outlook, and with the uptrend broken, it has entered a correction phase. Natural gas is showing a correction following a sharp decline, but has not yet managed to break through its downtrend line. Copper continues to trade within a wide range and is approaching the lower end of that range. Following a significant decline, wheat and corn prices have reached key support levels from which an upward correction—or even a new uptrend—is likely to begin.
Over 25 senior financial professionals, active in CEE markets and managing more than EUR 6.5 billion in assets under direct control, participated in our Institutional Investor Survey. Here, we highlight the most notable insights.
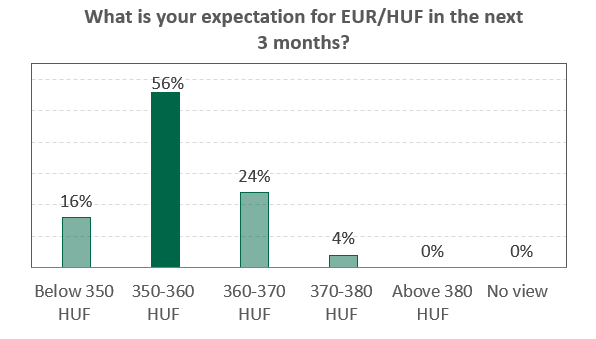
Hungarian assets re-rate sharply as election risk fades. Investor sentiment has turned decisively more constructive after the April vote, with 72% now expecting EUR/HUF below 360 over the next three months. The shift suggests investors are increasingly pricing a lower Hungarian risk premium, supported by a more predictable macro policy mix, eurozone-convergence ambitions and improving disinflation confidence.
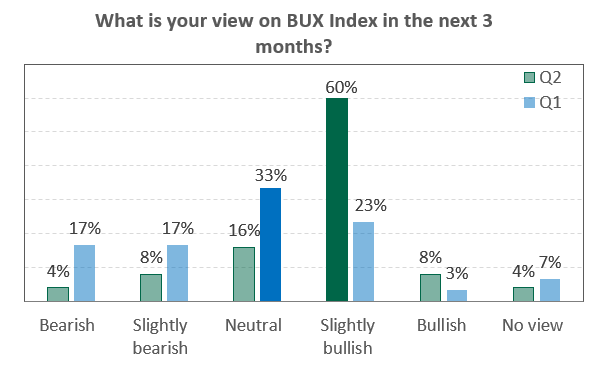
Investor sentiment toward Hungarian equities improved sharply compared with the March survey. 60% of respondents are now slightly bullish on the BUX Index, up from 23% in Q1, while bearish and slightly bearish views fell from a combined 34% to 12%. The Hungarian market had still been trading at a meaningful discount to the region before the election, despite some narrowing, mainly due to the poor perception of domestic economic policy. The change in government could support a further decline in Hungary’s equity risk premium and trigger convergence toward Poland, a market with which Hungary had moved closely for several years before 2022.
The CETOP outlook also improved, but less dramatically. The CEE stock market (CETOP) is expected to deliver around 25% profit growth this year, broadly comparable with the US, but without relying on AI- or technology-driven earnings momentum. This makes the region attractive in a scenario where global equity leadership broadens beyond US megacap technology.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more