
Gen Digital: another strong earnings report
Related content
The Fertilizer Producer’s Chart May Be Showing Promise Again After a Long Time
Despite the sharp decline, a number of previously underperforming, lagging stocks are showing signs of life. At the same time, for these stocks, we have seen almost without exception only initial, concentrated buying reactions over the past few months. However, a sustained turnaround would require the formation of higher lows and the confirmation of clear reversal patterns. In light of this, it is worth monitoring the stocks listed in the first table on a daily basis, as additional positive trading days accompanied by rising volume could significantly increase the likelihood of an emerging uptrend. We’ve selected two companies from the long list. One is Take-Two Interactive Software, which, moreover, is set to release its quarterly earnings today after the market closes, while Grand Theft Auto VI—eagerly anticipated by investors and gamers alike—is scheduled for release in ten days. The other stock we’re highlighting is Mosaic Company, one of the world’s largest fertilizer manufacturers, which is also showing an increasing number of positive technical signals following a significant drop in its stock price.
International Markets - Technical Analysis
The correction phase, which has lasted two to three weeks, gained new momentum last Thursday when an extremely sharp sell-off swept through the markets. As for the major stock indices, no clear buying opportunities are yet visible, although some of them have already corrected back by about half of their previous upward moves. The DAX and Stoxx 600 indices attempted to retest their previous highs but encountered strong resistance at those levels. Furthermore, gaps have formed on the charts; if these gaps remain open, it could signal the start of a new, more sustained downtrend. The index tracking emerging markets continues to move within a downtrend, though it is gradually approaching an important support zone. If it reaches this level, there is a greater likelihood of a significant rebound or a corrective phase.
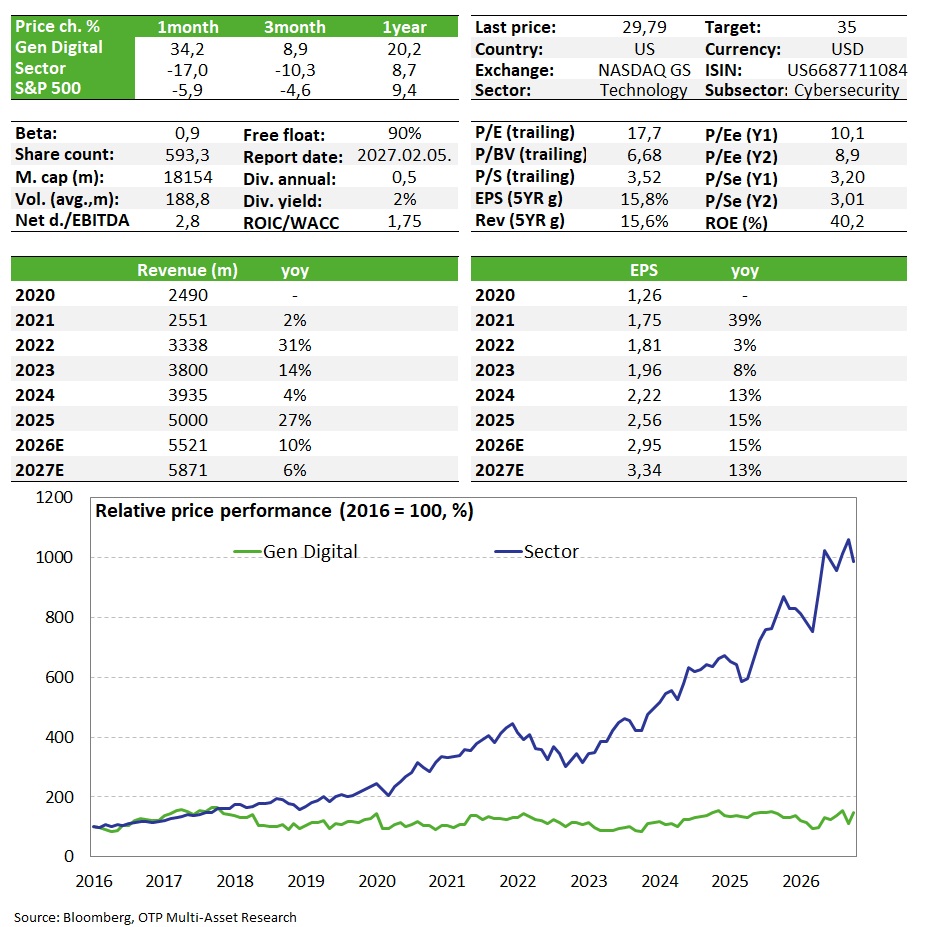
Gen Digital once again delivered better-than-expected quarterly results, while management also struck a more optimistic tone regarding the outlook. The company raised its FY2027 profit guidance above analyst expectations. Investors were also encouraged by comments from the CEO indicating that there are currently no plans for any major acquisitions, following earlier speculation about a potential takeover of GoDaddy, which many viewed as a sizeable and potentially risky deal. After being heavily sold off in recent months on these rumors, the stock reacted positively. Technically, the share price has once again reached the upper end of its multi-year trading range, which could act as a significant resistance level. However, given the improving fundamentals, we are raising our multiples based previous target price from $32 to $35 per share.
Gen Digital shares remain on our Equity Top pick List.
Quarterly report
The company generated revenue of $1.37 billion, representing 12% year-over-year growth. This increase can largely be considered organic, as the impact of the MoneyLion acquisition has now fully rolled out of the base. Revenue growth not only exceeded analyst expectations of $1.34 billion but also came in above the upper end of the company’s own guidance range. The strongest expansion continues to come from the Trust-Based segment, which includes digital trust and financial wellness services, with revenue rising 26% year-over-year. Meanwhile, the larger cybersecurity segment also delivered solid growth, expanding by 5% compared to the same period last year.
The cybersecurity business continued to perform well, with contract renewal rates reaching their highest level in a year. This should help ease investor concerns about the potential impact of AI agents on demand for cybersecurity services. Subscriber growth also remained strong, with the company’s total subscription base increasing by 6 million year-over-year to 83 million users, including a gain of 2 million during the quarter. Cross-selling initiatives were similarly successful, helping lift the segment’s operating margin from 61% to 62%, while operating income increased by 7%. In the Trust-Based segment, which now includes the recently acquired MoneyLion business, stronger revenue growth came alongside structurally lower margins that remained stable at 30%. As a result, the segment’s operating income rose by 24% year-over-year.
At the company level, operating margin reached 50%, while operating income increased by 10% year-over-year. This strong performance flowed through to earnings per share, which rose by 19%, marking the third consecutive year of double-digit EPS growth. While this growth has not been purely organic and has also benefited from acquisitions, the trend remains impressive. EPS came in at $0.74, ahead of the consensus estimate of $0.72. Free cash flow totaled $323 million during the quarter, more than three times the level recorded a year earlier. Of this amount, $76 million was returned to shareholders through dividends, equivalent to an annualized dividend yield of roughly 1.7%. The company also spent $171 million on share repurchases, corresponding to an annualized buyback yield of approximately 3.9%, while a further $45 million was used to reduce debt.
The outlook also remains encouraging. Management raised its full-year revenue guidance, now expecting growth of 10-11%, compared to the previous range of 9-11%. The company also became more optimistic on earnings, forecasting EPS of $2.93-$2.98, above the consensus estimate of $2.92. Performance is expected to strengthen further over the remainder of the year, supported by revenue synergies from the MoneyLion acquisition. In addition, free cash flow generation is typically stronger in the second half of the year, which could provide additional capacity for share repurchases and drive increased buyback activity.
Investors clearly rewarded these results, which is why they welcomed the CEO’s comment that the company is not currently pursuing any major acquisitions. On the one hand, the company’s leverage ratio of 2.9x net debt to EBITDA leaves limited room for a large-scale transaction. On the other hand, in the current market environment, investors appear to place a higher value on strong free cash flow generation and capital returns to shareholders. The acquisition issue had become a source of concern for the stock after reports by the Financial Times suggested that the company was considering a bid for GoDaddy. Such a deal would represent a significant undertaking given the relative size of the two companies, with GoDaddy’s market capitalization standing at roughly $14 billion compared to Gen Digital’s approximately $18 billion. For now, it is reassuring that this possibility appears to be off the table, and it would be beneficial for shareholders if that remains the case in the near term.
Valuation
In the technology sector, and particularly among software companies, Gen’s valuation metrics remain relatively depressed (P/E: around 9-10x vs. sector average: 35x; EV/EBITDA: 9x vs. sector average: 25x). Although expected growth is somewhat lower than the sector average, at 13% and 8% for EPS and EBITDA respectively, these figures do not necessarily justify such a significant valuation discount. Following the stronger-than-expected earnings report, we are raising our fair value estimate based on valuation metrics from $32 to $35 per share, which still suggests upside potential from the current share price.
Investment story
- The company provides protection against cyber threats (viruses, malware, ransomware, phishing, hacker attacks) to PCs, tablets, and smartphones through globally recognized brands such as Norton, Avast, Avira, and LifeLock. Norton LifeLock acquired its rival Avast in 2022 and is now the market leader in its field under a new name, Gen Digital.
- The company has a customer base of 500 million, mostly residential, of which 83 million are monthly or annual subscribers. The company is also developing in the field of machine learning and AI, has its own patents, and already offers solutions based on these to its customers.
- The company's free service user base (>400 million) is one potential source of new subscription growth, but customer retention and increased sales through partners could also contribute to the planned average annual revenue growth of around 5% over the next three years.
- The acquisition of MoneyLion was completed in April 2025, representing a cash outflow of $1 billion (at what appears to be fair pricing levels: a 9-11x EBITDA multiple) and, subject to certain conditions, could even have a dilutive effect (through the issuance of 1.5% new Gen shares). The company operates a consumer-focused financial products platform with 20 million users, with relatively little overlap with Gen's existing customer base. However, the emergence and adoption of AI agents could pose a significant challenge to the platform's business model, representing a material risk that may also cloud its long-term growth prospects.
- However, cross-selling opportunities are visible for the time being, and with annual revenues of USD 546 million, the new company could make a positive contribution (14% of that amount) from day one, and it is also profitable in terms of earnings. Following the completion of the transaction, Gen began to return to share repurchases in late 2025, in line with our expectations (USD 300 million, equivalent to 2% of its market capitalization), after having temporarily suspended buybacks due to the acquisition.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more