
EOG Resources: better than expected results, strong cash generation
Related content
Our Equity Top Pick List
We have updated our Equity Top Pick List to reflect the events of the past quarter. The list includes those stocks, typically US and European ones, that we consider to be proper investment choices from a fundamental point of view. It can provide a starting point for building a sector-diversified equity exposure in portfolios, but can also be used as a watch list. Technical analysis should be used to time / determine the specific investment decision.
Could the momentum return in the semiconductors?
The semiconductor sector has had a challenging quarter, with its performance in recent months lagging behind improvements in underlying fundamentals, even as AI-driven demand remained exceptionally strong. The accelerating adoption of AI by enterprises and the proliferation of AI agents are significantly increasing the demand for computing capacity, which points to a further surge in cloud services and data center investments. Given current supply constraints, record-high backlogs, and higher-than-expected investment needs, we expect further upward revisions to earnings forecasts in the semiconductor industry. Nevertheless, the sector’s valuation appears favorable from a historical perspective, which, in our view, could result in a more attractive risk-return profile in the coming months.
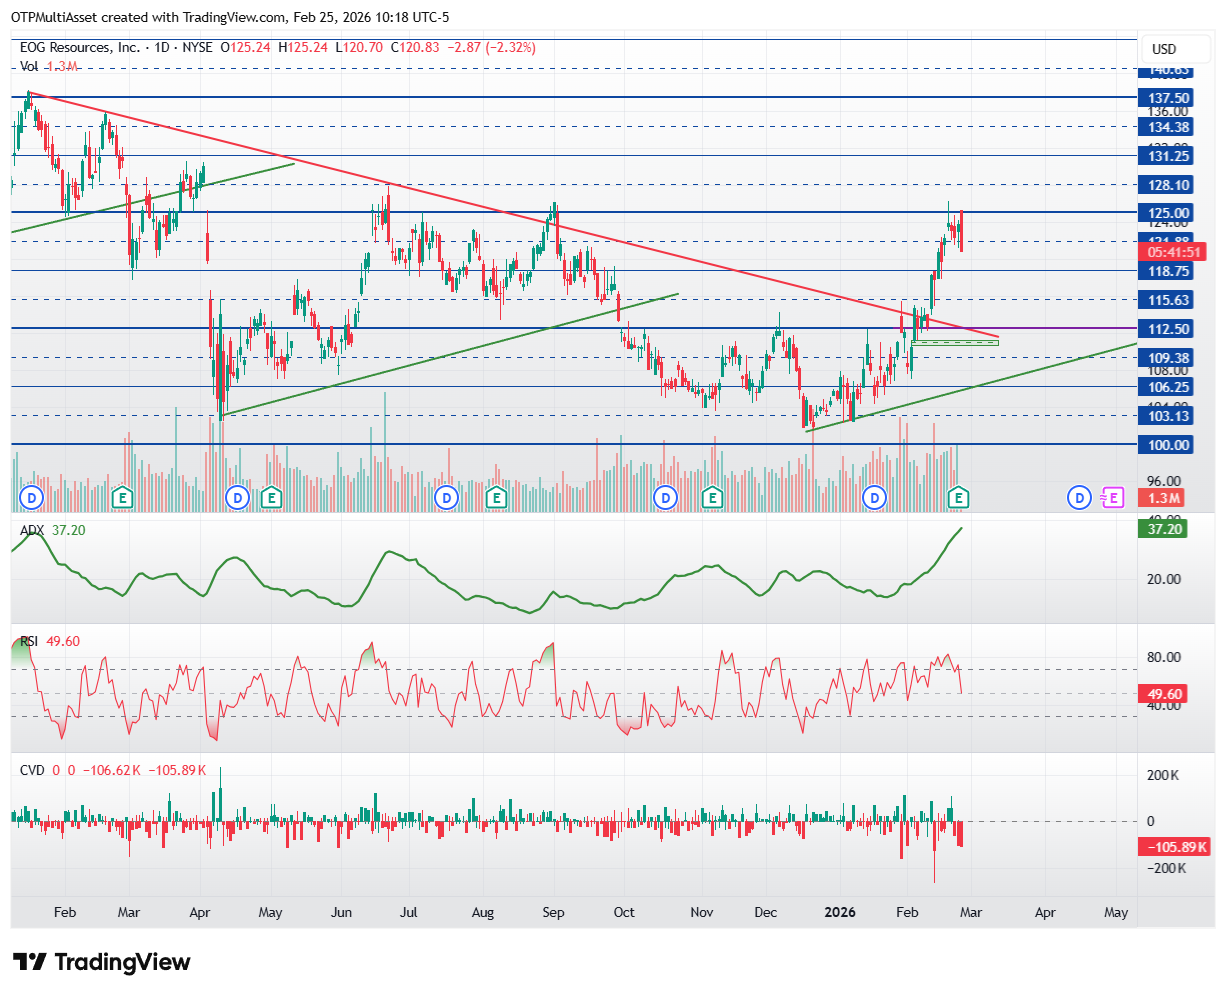
EOG Resources published its fourth quarter earnings report on Tuesday after the market closed, which was generally positive, with the company slightly beating analysts' expectations. On an annual basis, results are weaker due to lower oil prices, which higher production volumes were only able to partially offset. Nevertheless, free cash flow generation remains strong, which EOG is fully allocating to dividend payments and share buybacks. Management expects high free cash flow generation to continue in 2026, although it may be slightly lower than last year. We are therefore keeping our trading idea open for now, which is ~9% higher compared to our recommended entry level at the end of January, with the same target price of USD 134.35. In the short term, however, a correction is possible based on the technical picture. We will reassess our idea in the coming period based on the depth and shape of this correction. The level around 112.5 is considered as a strong support, so if the price falls below this, it would definitely be negative. On the other hand, it would be a good sign if the stock can remain above 118.
Quarterly earnings
EOG Resources published its fourth quarter earnings report on Tuesday after the market closed, for which we had formulated a trading idea at the end of January. Revenue and earnings per share slightly exceeded analysts’ expectations. For the full year, EPS ultimately came in at $10.16, compared to $11.62 in 2024 (-13% year-on-year), which can be considered relatively favorable in a weaker oil price environment. However, it should be noted that the company acquired the oil producer Encino in August last year, which had a positive impact on figures due to higher production volumes.
Free cash flow was $978 million (-23% year-on-year) in the last quarter and $4.66 billion (-13% year-on-year) for the whole of 2025, which is weaker on an annual basis but still significant. Net debt at the end of last year was $4.5 billion, which jumped significantly due to the acquisition of Encino ($4.5 billion cash transaction), but is not relatively high compared to free cash flow.
Oil and gas production averaged 1.4 million barrels per day in the last quarter, compared to an average of 1.23 million barrels per day for the whole of 2025 (Encino's production is equivalent to approximately 230,000 barrels, which is largely responsible for the better Q4 figures). However, higher volumes and higher average gas prices were unable to offset the decline in crude oil prices (the latter averaged $59.5 per barrel in Q4 vs. $71.7 in Q4 2024). At the same time, oil prices have been trending upward since the beginning of the year, which is encouraging, although tensions between Iran and the US also play a role here, so there is significant uncertainty (representing both upside and downside risks).
Dividend, share purchase and outlook
Following the results, EOG Resources declared a quarterly dividend of $1.02 per share (Q4 EPS was $2.27). This represents an annual payment of approximately $2.2 billion and an annualized dividend yield of ~3.3% (the quarterly dividend rate did not increase). At the same time, the company is also continuing to buy back its own shares, spending $675 million in Q4 and $2.5 billion for the full year (which was slightly higher than the dividend payments). The total shareholder payout was thus roughly equivalent to the total free cash flow for 2025. It should also be noted that since 2023, the company has reduced its share capital by approximately 10%, and the current buyback program still had a budget of $3.3 billion at the end of the year.
In 2026, EOG targets free cash flow of approximately $4.5 billion, which is slightly lower on a year-over-year basis (this implies roughly similar dividends and approximately $2.3 billion in share repurchases). Capital expenditures are expected to be $6.3-6.7 billion, which is approximately $200 million higher on a year-over-year basis at the midpoint.
Overall, EOG Resources performed well in the last quarter and in 2025, despite relatively weaker oil prices. The balance sheet structure is stable and free cash flow is high, which the company is using for dividends and share buybacks. We are therefore keeping our trading idea open for the time being, following the earnings report, with a current target price of $134.35. However, based on the technical picture, a correction is possible in the short term, the depth and shape of which will provide information on how to manage the position.
Technical picture
The stock reached an important technical level around 125, where profit-taking can be seen as a result of the earnings announcement. The extent and nature of this can provide important information about whether the position should be kept and remains in a strong trend. The less it falls and the more it can stay above 118.75, the better. The level around 112.5 is already a very strong support, and the price should not fall below this level.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more