
AutoWallis: Earnings Recovery Delayed
Related content
Glencore: clouds are gathering over the metals market
Glencore, the commodities giant, has achieved excellent financial results so far in 2026, but in our view, the outlook has taken an unfavorable turn, especially in the metals and mining sector, where both copper and zinc prices have been trending downward in recent weeks. Among other factors, weaker Chinese economic data and deteriorating AI sentiment may have played a role here, as data centers use significant amounts of copper. At the same time, although coal prices have improved significantly this year, we would have expected even higher prices given the tight conditions in the energy market. Accordingly, we are removing Glencore from our Equity Top Pick List. The stock has provided a return of about 26% including dividends since we added it to our list last December despite the decline in recent weeks.
FX - Technical Analysis
Following the correction seen over the past month, the U.S. dollar has regained strength against its major currency counterparts. The EUR/USD exchange rate has broken below the 1.1108 level, confirming the continuation of the downward trend. The dollar is also in a favorable position against the British pound, with the exchange rate potentially extending its move after breaking below the lower boundary of a broader trading range.In the case of EUR/HUF, the recent narrowing price action may soon come to an end, potentially leading to an upside breakout from the triangle pattern. The Hungarian forint had already been showing signs of depreciation against the U.S. dollar earlier, and this trend may continue with the formation of new swing highs. USD/JPY broke out to the upside from a narrowing range two weeks ago; however, the breakout has not yet been accompanied by particularly strong momentum. As for EUR/CHF, following a recent modest correction, the downward direction may once again come into focus.
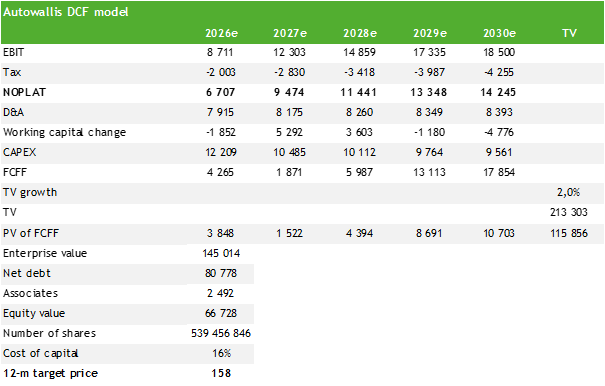
Following the latest quarterly results, we have revised our DCF model and earnings estimates. We cut our 12-month price target to HUF 158 and downgrade the shares to Hold from Buy. The challenges facing the Distribution business unit have not been resolved and, if anything, intensified during the first half of the year. This was the key driver behind our downward revisions to this year’s revenue and earnings forecasts.
Growth also slowed in Retail, while margins remained under pressure. We therefore expect the recovery in profitability to take longer to materialise and to be less pronounced than previously anticipated. Mobility continues to stand out in terms of earnings generation, but its contribution at Group level remains too small to offset the weak performance of the automotive distribution and retail businesses.
Following the model update, we forecast a low-single-digit revenue CAGR of 3.6% and an EBITDA CAGR of 7.4% over the forecast period. As before, our updated model does not incorporate any future acquisitions. On this basis, we expect revenue to approach HUF 570bn and EBITDA to reach approximately HUF 27bn by 2030. These figures are well below management’s current targets, raising the question of whether the financial targets set out in the company’s previous 2028 growth strategy will need to be materially revised.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more