
AWS Puts Amazon Back in High Gear
Related content
Meta: Burning Cash on the AI Promise
Overall, Meta’s quarterly performance continues to paint a positive picture in terms of the underlying fundamentals, while the company has also achieved significant milestones on the AI model development front. However, elevated spending is taking a substantial bite out of cash generation, with free cash flow now turning negative, which may increasingly require funding through capital market financing. Following the stock’s rally in recent weeks, valuation levels have also moved higher. In the near term, these factors may continue to put pressure on the stock, although the longer-term outlook remains constructive. Naturally, much will depend on the company’s ability to effectively monetize its investment program over time.
The government plans a 4.9% deficit for next year
The government plans a 4.9% deficit for next year and will gradually reach 2.8% by 2030, under the Maastricht criteria
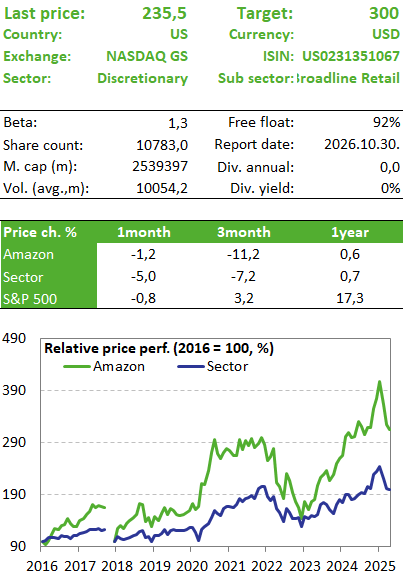
Amazon's stock price surged following the release of a better-than-expected preliminary report. Investors primarily praised AWS's spectacularly accelerating growth and outstanding profitability, and not even the announcement of a capex plan increased to $220 billion could dampen the mood.
Amazon shares remain on our Equity Top pick List.
Quarterly Report
Investors reacted positively to Amazon’s quarterly report after AWS’s growth accelerated dramatically, while the segment’s high profitability remained intact. AWS revenue rose to $42.2 billion, representing a 36.7 percent year-over-year increase, up from 28 percent in the previous quarter. This was the segment’s fastest growth since 2021. The consensus estimate had been for revenue of approximately $40.5 billion and 31 percent growth.
It is particularly important to note that this growth was not driven solely by demand for the computing capacity required to train the largest base models. Management reported strong demand for both AI services and traditional, core cloud services. This is because AI applications also generate additional demand for processors, data storage capacity, databases, network services, and data processing. Furthermore, the use of AI agents requires significant CPU capacity during device operation and reinforcement learning.
AWS’s contract backlog and unrecognized revenue rose to $496 billion from $364 billion in the previous quarter, and showed triple-digit growth year-over-year. Management also noted that the majority of the capacity set to come online in 2027 has already been committed, and customers have reserved significant capacity for 2028 as well. AWS posted an operating profit of $16.6 billion, up from $10.2 billion a year earlier, while the adjusted margin rose to 37.9%.
After this, not even Amazon’s decision to raise its annual capital expenditure plan from $200 billion to $220 billion could dampen the mood. The increase was primarily driven by higher prices for memory chips. Investors believe that the company’s massive investments can pay off relatively quickly.
The company’s retail division also posted strong growth. Revenue in North America rose 16 percent to $116.2 billion, while revenue from international markets, excluding currency effects, increased 15 percent to $42.2 billion. Amazon is continuously striving to increase efficiency in this area as well by improving inventory management and logistics, with automation and robotics playing an increasingly important role.
Advertising revenue rose 26 percent to $19.8 billion, exceeding consensus estimates. The largest share continues to come from sponsored product ads, but Prime Video and live sports broadcasts are also offering clients more and more opportunities.
Overall, Amazon delivered a strong quarterly performance built on solid foundations, so we’re keeping the stock on our Equity Top Pick List.
Investment thesis
- AWS is a leader among major cloud service providers, and this quarter has once again demonstrated that it still has room to grow. The advertising segment also has significant potential for growth, and this business line could become a major profit driver thanks to its high margins.
- The rise of AI is still in its early stages, and we can expect even greater growth in this area in the coming years; Amazon is one of the best-positioned companies to capitalize on this expansion. AWS already offers a platform that its customers can use, for example, to develop and run generative AI applications.
- The retail sector is constantly seeking ways to improve efficiency, which could continue to have a positive impact on margins in the future. It may also benefit early on from the spread of automation through increased efficiency.
- Risks: Competition is extremely intense in the cloud computing sector and the field of artificial intelligence. It is not certain that Amazon will come out on top. It is unclear over what timeframe and with what returns the tens of billions of dollars the company is spending on AI investments will pay off. This is one reason why sentiment in the stock market was currently negative.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more