
OTP Morning Brief: silver and gold prices hit new highs
Related content
OTP Morning Brief: Thursday trading brings equity market correction and rising oil prices
European equities closed slightly lower, primarily due to weakness in the technology and defence sectors. A more significant correction unfolded on US equities markets as a wave of selling hit technology stocks, while oil and natural gas prices rose markedly amid escalating geopolitical tensions. Amid growing investor caution, both US and German government bond yields declined, while the dollar edged higher against the euro after experiencing significant intraday volatility. Longer-dated yields also declined on the Hungarian bond market, while the forint weakened against both the euro and the dollar. The negative sentiment spilled over from US markets into Asia, with most major Asian equity indices trading in negative territory during the morning session. Today's focus will be on the October US labour market data, which could materially influence market expectations regarding the Federal Reserve's December rate decision. Additionally, retail sales data will be released from both the euro area and Hungary, while Germany will publish its September industrial production figures.
OTP Morning Brief: Investor sentiment improved following the Democrats’ congressional victory and the decline in oil prices
Lower bond yields and oil prices, driven by the Democrats’ expected congressional majority, improved market sentiment. Brent crude has fallen by roughly 20% since the beginning of the week, while the yield on the 10-year US Treasury note declined by 6 basis points to 4.89%. Amid the favourable risk environment, the US dollar weakened, with the EUR/USD exchange rate rising to near 1.123. In Europe, positive corporate news also supported market sentiment, with the STOXX 600 index rising by 1.8%, while shares of Novo Nordisk gained 5.6% after the company raised its full-year guidance. Today, investors will focus on German industrial orders, French industrial production and the euro area producer price index, alongside interest rate decisions by the Bank of England and the Czech central bank. In the US, weekly initial jobless claims, as well as Q3 productivity and labour cost data, will also be in the spotlight.
Western Europe’s markets inched down in Monday’s subdued pre-holiday trading; silver and gold prices broke records. The CEE region’s indices rose, the BUX and OTP closed at new highs. US markets marched higher. Japan’s and Germany’s 10Y bond yields are new highs. The forint’s weakening against the euro continued. America’s GDP data and Hungary’s current account balance are data to watch today.
Western Europe’s markets edged lower in Monday’s light trading, while silver and gold prices hit new record; the CEE region’s indices rose, OTP closed at a new high again
The stock markets of Western Europe closed slightly lower on Monday. The STOXX Europe 600 inched down 0.1%. The major stock markets also weakened: London's FTSE and France's CAC 40 shed 0.3% and 0.4%, respectively, while Germany's DAX ended flat.
Most sectors weakened after Friday's strong gains, while the food & beverage sector suffered the biggest losses. Shares in Diageo, the world’s largest spirits company, slumped 3.7%, as did French spirits maker Pernod Ricard (-2.9%) and Anheuser-Busch InBev (-2.5%), the owner of Stella Artois. The commodities sector closed higher; mining companies upped nearly 1% as gold broke above 4,400 USD/ounce for the first time, while silver and copper also hit record highs. The banking index –the main engine of last week’s growth– has barely changed. The sector has gained more than 65% year to date, and remained one of the strongest performers. Analysts attribute this to a pick-up in corporate mergers and acquisitions, a more moderate regulatory environment, and a relatively stable economic backdrop. The defence and aerospace sector slipped 0.4% after surging more than 3% in the previous two trading sessions. Oil stocks rose by 0.3%, tracking an increase in crude prices.
The London market was dragged down by the UK’s weaker-than-expected GDP data: while Q3 growth, at 0.1% quarter-on-quarter, was in line with expectations, the Office for National Statistics revised down the second-quarter figure to 0.2% from 0.3%.
In individual stories, Abivax jumped 15% after media reports suggested that US pharmaceutical giant Eli Lilly may be making another bid for the company. Orsted, on the other hand, plunged more than 12% after the Trump administration suspended approvals for five large-scale offshore wind projects, citing national security concerns. The Danish energy company owned two of those projects.
The main markets in the CEE region rose: CETOP (+0.3%), PX50 (+0.4%), and Poland’s WIG (+0.9%) all advanced. Hungary’s BUX (+0.4%), benefited from MOL’s (+2.3%) growth that followed a decline in the previous days. OTP (+0.4%) closed at a new all-time high, while Richter (-0.7%) and MTelekom (-0.9%) subsided.
Gold and silver also closed at new highs, with gold ending above USD 4,400 and silver above USD 68. The gains were driven by news that the US had seized another Venezuelan oil tanker, in the third such seizure in two weeks. The incident also contributed to an increase in oil prices: Brent and WTI both closed roughly 2% higher for the day.
US markets marched higher
America’s stock market rose further, partly supported by the continued strength of technology stocks; the broad-based rally helped almost all of the eleven sectors of the S&P 500. The Dow Jones added 0.5%, the S&P and Nasdaq advanced 0.6% each.
The rally began late last week after Micron Technology issued an exceptionally strong forecast, and weaker-than-expected US inflation data came out – as a result, the S&P 500 and the Dow came less than 1% shy of their record closing levels set on 11 December. Nvidia shares grew by 1.2%, making the largest contribution to the strengthening of the S&P 500 index. Reuters reported that the company has told Chinese customers that it plans to start shipping its second-most powerful AI chip to China in mid-February, before the Lunar New Year. Micron surged by 3.8%, and most other chipmakers rose, helping the Philadelphia SE Semiconductor Index increase by 1.1%.
Gold price rose 0.3%, while silver jumped 2.5%, reaching a new all-time high above $67.
Japan’s and Germany’s 10-year yields hit new highs; the HUF weakened against the EUR again
The upward trend, which started after Japan had hiked interest rates on Friday, continued on Monday: Japan’s 10Y yield closed above 2.08%. Meanwhile, a former decision-maker of the Bank of Japan said that the base rate may rise to 1.5% from the current 0.75%. Germany’s 10Y yield also rose above 2.9%, a level last seen in October 2023. The US 10-year government bond yield also rose, closing at 4.17%. The EUR/USD closed at 1.176. The yen strengthened 0.4% against the USD after Finance Minister Satsuki Katayama said in an interview with Bloomberg News on Monday that Japan has “free hand” for a bold action in the FX market if needed.
The HUF weakened by 0.5% on Monday, reversing Friday’s strengthening: the EUR/HUF closed at 388.71. While yields rose elsewhere, Hungary’s benchmark yields sank on securities maturing in up to ten years, yields on 15Y-20Y tenors increased; the 10-year yield was 6.78%.
Today’s highlights
Asia’s indices moved mixed this morning: China’s SSEC upped 0.3% and Japan’s Nikkei shed 0.2%. The yen remained the focus of attention in the FX market, as investors assess chances that Japan’s authorities will intervene soon to support the local currency. The yen appreciated by 0.7% in today’s trading. Europe’s index futures were near-stagnant, while their American counterparts edged down trivially. WTI sank 0.3%.
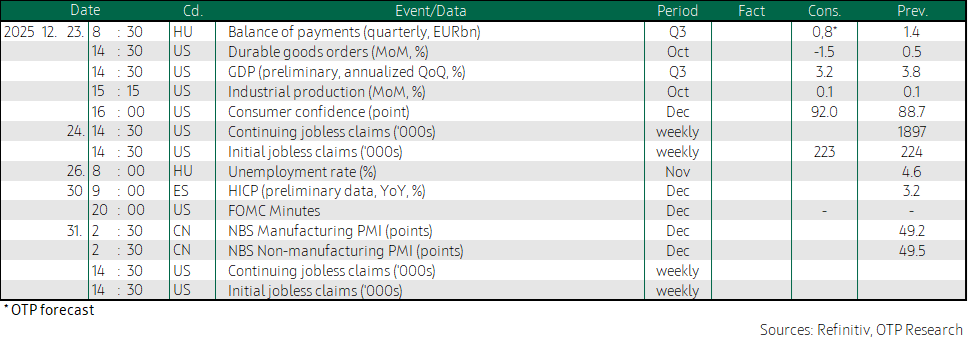
The USA releases the Q3 GDP data, which were delayed due to the government shutdowns. It is estimated that annualized growth may have been around 3%, in a slight slowdown compared to the previous quarter.
Our next Morning Brief will be published on 5 January 2026. Happy Holidays!

Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more