
OTP Morning Brief: Anthropic's IPO fails to restore confidence in the AI growth story
Related content
OTP Morning Brief: Stronger-than-expected investor interest surrounded Anthropic’s IPO
Major European indices declined yesterday; mining stocks were among the worst performers following the sell-off in copper prices; the banking sector came under pressure on reports related to the ECB; UK inflation rose slightly less than expected. Major US indices closed mixed yesterday; Nvidia shares declined despite strong earnings results; Anthropic’s IPO attracted stronger-than-expected investor demand; mixed data arrived from the US housing market. Developed-market long-term yields mostly declined, even as further signals pointing to additional Fed tightening emerged; oil prices fell on the back of higher-than-expected inventories; the Hungarian forint weakened further. Today, alongside the usual weekly US initial jobless claims data, the Conference Board Leading Economic Index (LEI) will also be released.
OTP Morning Brief: Risk aversion strengthened across markets ahead of Nvidia’s earnings release
Negative sentiment prevailed across equity markets on Tuesday: European exchanges suffered their steepest decline in several months, while the technology-led correction on Wall Street continued amid a wait-and-see approach ahead of Nvidia’s earnings release. In the US, comments from Fed policymakers further reinforced expectations of a December rate hike. The MNB kept its base rate unchanged; however, the decision was not unanimous. Growing caution led to declining yields across developed bond markets, while French government bonds outperformed within the euro area. In Hungary, yields edged lower, while the forint weakened against both the euro and the US dollar. Today’s releases include the UK’s October CPI data, several key US housing market indicators and Hungary’s September wage figures, while the minutes of the Fed’s latest rate-setting meeting will also be published later in the day. Among corporate earnings releases, quarterly results from Tencent and Palo Alto Networks will be in focus.
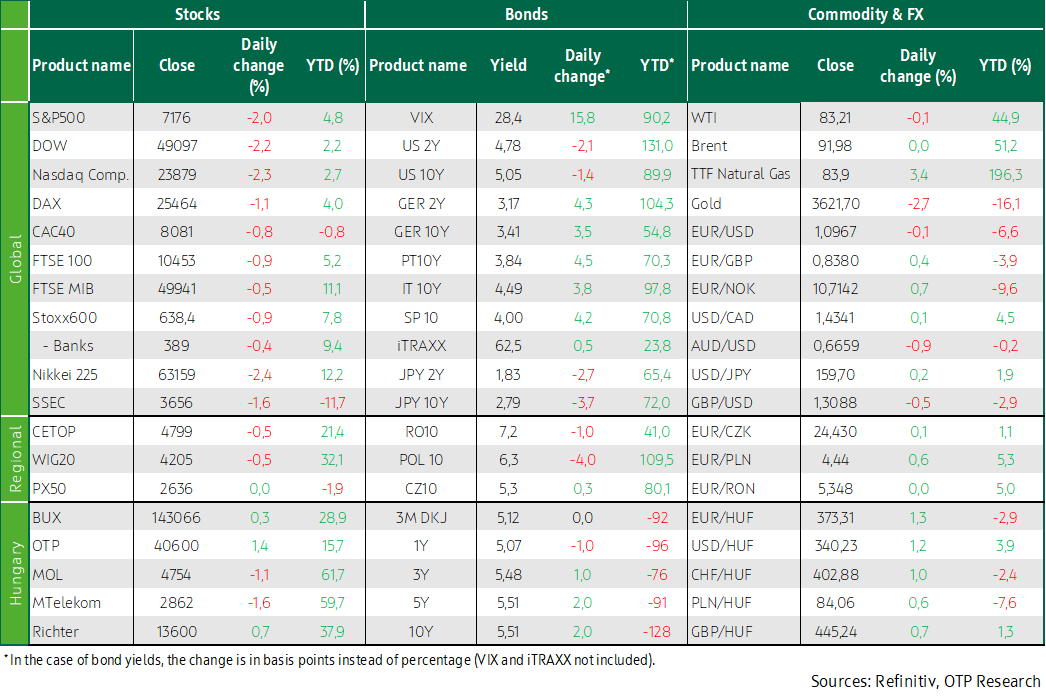
Leading European and US indices ended Thursday's trading session in negative territory. Uncertainty surrounding the profitability of AI investments and elevated technology stock valuations weighed on market sentiment. Anthropic, the developer of Claude, began trading at a $1.5 trillion valuation following its $81.3 billion capital raise on Wednesday. Long-term yields declined in the US, while moving higher in Europe. The dollar strengthened against the euro. The forint continued to weaken against the major currencies. Today, attention will be on the ECB’s Q3 wage data and the euro area’s November consumer confidence index. In Hungary, the focus will be on Moody's sovereign rating review.
Uncertainty over the profitability of AI investments weighed on investor sentiment across major European equity markets
Major European equity indices declined for a fourth consecutive trading session on Thursday, as investors grew increasingly cautious about the outlook for artificial intelligence-related stocks. The pan-European STOXX 600 fell 0.9%, closing at its lowest level since October 23. Market sentiment was primarily weighed down by uncertainty over the profitability of AI investments and elevated technology stock valuations, with expectations surrounding Anthropic’s record-breaking IPO adding to investor concerns. Among European technology suppliers, ASML gained 2.2%, while STMicroelectronics advanced 1.6%.
Selling pressure was broad-based across sectors, with defensive stocks among the weakest performers. Food and beverage companies and healthcare names fell 2.1% and 1.8%, respectively, after significantly outperforming in recent weeks. The decline in energy prices since the start of the week also weighed on European equity markets, as the energy sector had been a key driver of regional performance in recent months. Among individual stocks, Soitec soared 12% after the semiconductor supplier issued a more optimistic financial outlook than expected, while Novartis fell 3.2% after reaffirming the lower end of its medium-term revenue growth target range. Commerzbank lost 1.2% as developments related to UniCredit’s (+0.2%) takeover attempt remained in focus, with the two sides reportedly making progress on several key issues surrounding the proposed transaction. Sanofi declined 2.9% following a Bloomberg report that the French drugmaker is considering an acquisition of US-based Insmed.
The BUX outperformed its regional peers in Central and Eastern Europe, rising 0.3%, while Hungary’s blue-chip stocks delivered mixed performance, with gains posted by OTP and Richter.
Anthropic's IPO fails to restore confidence in the AI growth story
Wall Street ended Thursday’s session with losses of around 2%, as Anthropic’s market debut failed to materially improve sentiment toward artificial intelligence-related stocks. The Dow fell 2.2%, the S&P 500 declined 2.0%, while the tech-heavy NASDAQ dropped 2.3%, marking its sixth consecutive day in negative territory. Selling pressure was notably broad-based, with more than 90% of S&P 500 constituents closing lower. The benchmark index has now fallen for six straight sessions, its longest losing streak since 2024, and remains 8.2% below the record high reached in October. On a weekly basis, the major indices were down between 4.9% and 6.2%.
Anthropic, the developer of Claude, began trading at a $1.5 trillion valuation following its $81.3 billion capital raise on Wednesday, with its market capitalization briefly exceeding $2 trillion. Anthropic shares opened at $111.5, well above the $83 IPO price, and climbed as high as $115 during the session. Initial enthusiasm gradually faded, but the stock still closed the day up 17.1%. Within the technology sector, semiconductor manufacturers and companies exposed to data center buildouts were among the weakest performers: AMD dropped 7.7%, Nvidia fell 3.3%, while Micron and Broadcom each lost 2.1%, as the Philadelphia Semiconductor Index declined 2.4%. Investors are increasingly questioning the expected returns on AI investments and the pace at which data center expansion can continue amid rising costs and potential financing constraints. Among company-specific developments, Palo Alto Networks rose 6.4% after the cybersecurity firm raised its 2027 revenue growth outlook, while Walmart slipped 1.0% following a disappointing full-year sales forecast.
Market sentiment was further undermined by the minutes of the Fed’s October policy meeting, released on Wednesday, which showed that a majority of policymakers still see the need for additional monetary tightening. Combined with stronger-than-expected inflation data published since the meeting, expectations for a December rate hike strengthened further. Markets are now pricing in an almost 100% probability of a 25-basis-point increase in December, while the likelihood of a 50-basis-point hike has also moved higher.
Long-term yields moved lower in the US and higher in Europe; the forint weakened against major currencies
US long-term yields moved lower after initial jobless claims rose to 203,000, above expectations of 197,000, easing rate hike expectations. This followed Wednesday’s focus on the Fed’s hawkish meeting minutes and comments from Fed Governor Christopher Waller, who suggested that a 50-basis-point rate increase could still be justified in December. As a result, the US 10-year Treasury yield fell to 5.05% on Thursday. In Europe, long-term yields edged higher, with the German 10-year Bund yield rising to 3.41%. The dollar outperformed the euro, with the EURUSD pair moving in favor of the greenback.
Thursday's trading brought only modest moves to the Hungarian bond market based on the Government Debt Management Agency’s (ÁKK) early-afternoon benchmark quotations. The short end of the yield curve was broadly unchanged, while yields at the long end rose by 1–2 basis points. ÁKK sold HUF 20 billion of discount treasury bills maturing in October next year, in line with the announced amount, at an average yield of 5.09% and a bid-to-cover ratio of 2.5x. The forint continued to weaken against major currencies, with EURHUF rising above 373 and USDHUF moving above 340.
Oil prices moved higher on Thursday, although they ended the day little changed compared to Wednesday’s close. Incidents in the Strait of Hormuz heightened uncertainty surrounding the Middle East conflict and fueled concerns over potential supply disruptions. According to Iranian reports, two oil tankers struck naval mines, while Houthi forces launched missiles toward Riyadh. Market participants offered mixed reactions to the meeting between Donald Trump, Xi Jinping and Vladimir Putin, where the three leaders emphasized the importance of maintaining stability in global energy markets.
Today's highlights
The sharp sell-off on Wall Street cast a shadow over Asia-Pacific markets this morning, with the correction in AI-related stocks exerting the strongest downward pressure on regional equities. South Korea’s Kospi was down 5.5% and Japan’s Nikkei nearly 5% heading into the close, while Hong Kong’s Hang Seng and China’s Shanghai Composite also posted steep losses. Semiconductor stocks came under particularly heavy pressure, with shares of Samsung, SK Hynix, TSMC, SoftBank, Tokyo Electron and other chip-related companies plunging between 4% and 16%. Taiwan’s benchmark Taiex was down more than 6% in morning trading and is on track for a weekly decline of around 15%, which would mark its worst weekly performance since 1997. Among regional technology names, Alibaba stood out as the sole major gainer after reporting better-than-expected results. Investor sentiment was further weighed down by stronger-than-expected inflation data in Japan, which reinforced expectations of a December rate hike.
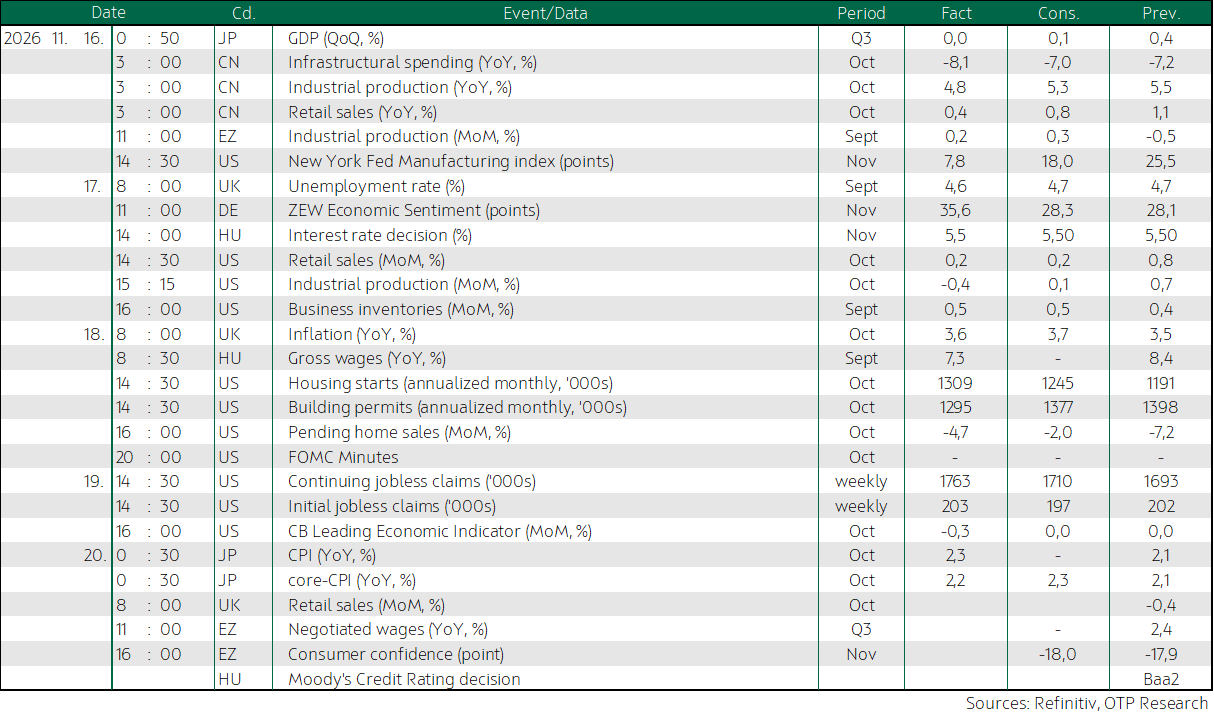
Today, attention will be on the ECB’s Q3 wage statistics and the euro area’s November consumer confidence index.
In Hungary, the spotlight will be on Moody’s sovereign rating review, scheduled for release after market close.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more