
OTP Morning Brief: The company's stock price plummeted following the resignation of Nvidia's CEO
Related content
OTP Morning Brief: CoreWeave shares soared nearly 25% yesterday
Major European indices advanced yesterday; optimism surrounding AI-related companies strengthened, while mostly favorable earnings reports emerged across Europe. Meanwhile, rising oil prices heightened inflationary pressures. Major US indices moved higher yesterday on the back of positive corporate developments; CoreWeave shares soared nearly 25%, while reports suggest strong investor interest in Anthropic’s IPO scheduled for next week. US bond markets were closed yesterday for a public holiday, while yields in Europe showed little change; oil prices rose following a renewed escalation of geopolitical tensions. Today, alongside the usual weekly US initial jobless claims data, housing market and federal budget figures will also be released, while the UK’s Q3 GDP data will provide further insight into economic performance.
OTP Morning Brief: OTP reported earnings above analysts' expectations this morning
The US 10-year Treasury yield briefly climbed above 5% on Tuesday following the release of stronger-than-expected inflation data. Expectations for further Fed rate hikes strengthened, supported not only by the latest inflation data and last week’s exceptionally strong labour market figures, but also by hawkish comments from central bank policymakers. US equity indices weakened in the face of rising bond yields, with the IT sector emerging as the day's worst performer. In Europe, steadily declining oil prices provided further support to equity markets. The US dollar strengthened, with EUR/USD falling to 1.116. In Hungary, CPI accelerated to 2.0% in October, while core CPI rose to 2.1%. Hungarian long-term bond yields, however, edged lower, with the benchmark 10-year yield declining to 5.26%, its lowest level in nearly four months. The forint weakened alongside other regional currencies, albeit to a greater extent, with EUR/HUF edging up to 364.5. Investor attention is likely to focus on OTP’s Q3 earnings report released this morning.
Europe benefited from its lower exposure to AI, and the Stoxx 600 rose to a record high. Overseas news was dominated by the resignation of Nvidia CEO Jensen Huang, and the stock price of the most prominent company in the AI boom took a sharp nosedive, which also cast a shadow over sentiment in the broader stock market. Meanwhile, uncertainty in the Middle East has intensified after Trump changed his position overnight, making a successful negotiation seem less likely once again, while oil prices continue to rise. This also pushed up bond yields in the United States, but had only a minor impact in Europe. The United Kingdom's economy posted a strong third quarter. Asian markets were mixed in the morning. Today, we can expect the release of eurozone employment data and the US producer price index.
The Stoxx 600 hit a record high on Thursday, and the UK economy grew strongly in the third quarter
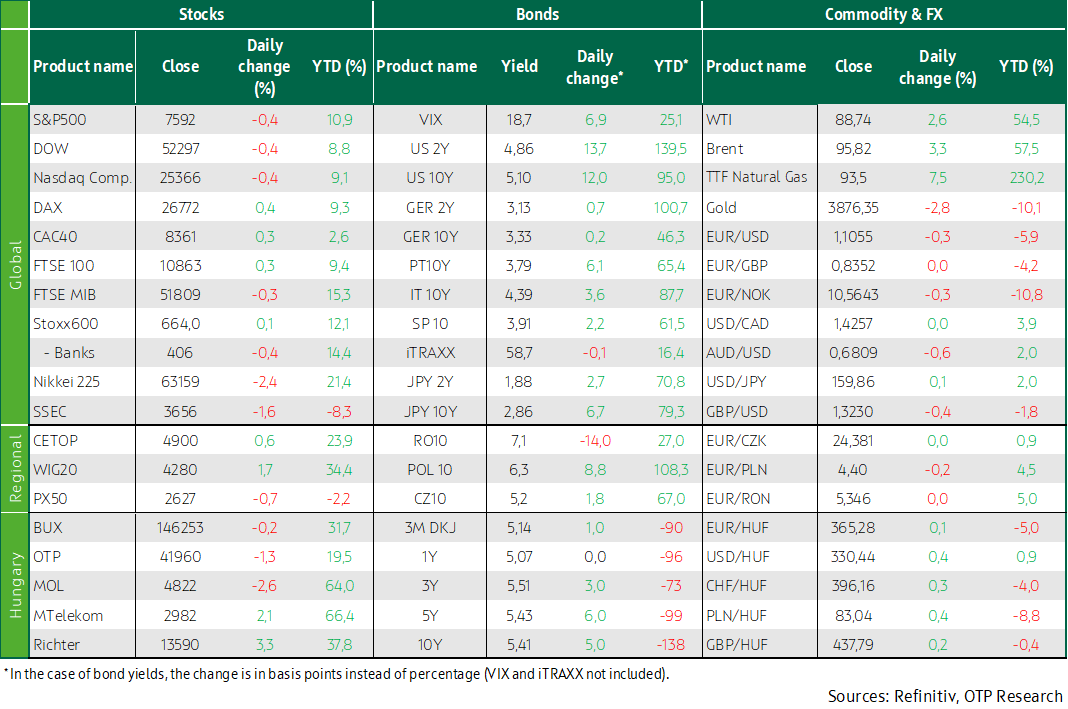
Although it closed slightly below its intraday high, the pan-European Stoxx 600 still closed at a record high, up 0.1% for the day. Lower AI exposure compared to Asian and U.S. markets has been favorable for the European market, so European indices have outperformed in recent periods. On Thursday, the insurance (+1.3%) and retail (+1.1%) sectors outperformed, while the technology sector fell by 0.4%. Among the major national indices, the DAX stood out with a 0.4% gain; moreover, the German index also closed at a record high. Both the French CAC 40 and the British FTSE 100 closed 0.3% higher. Among individual stocks, Siemens rose 1.7% after the German industrial technology company raised its medium-term growth outlook.
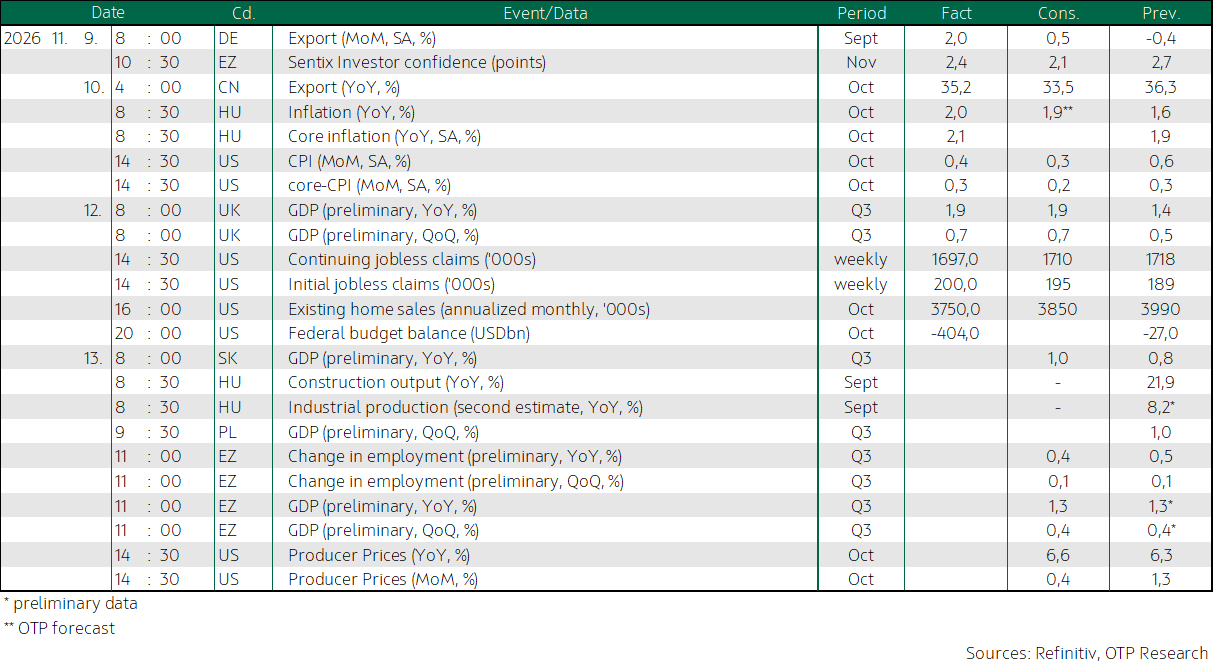
The United Kingdom’s economy expanded by 0.7% in the third quarter of 2026 compared to the previous period, marking the fastest growth rate since the first quarter of 2024. Economic growth accelerated from 0.5% in the second quarter and was in line with market expectations. Investment rose by 1.7%, while both household consumption and government consumption increased by 0.6%. Exports expanded by 1.6%, while imports rose by 1.8%. Year-over-year, GDP rose by 1.9%, marking the strongest growth rate in nearly two years and an acceleration from the 1.4% recorded in the second quarter.
The CEE region posted mixed results: the WIG 20 rose 1.7%, while the PX 50 fell 0.7% and the BUX fell 0.2%. Looking at the Hungarian market, domestic blue chips also presented a mixed picture; the market’s decline was driven by a 2.6% drop in Mol and a 1.3% drop in OTP, while MTelekom rose 2.1% and Richter rose 3.3%. The latter’s share price was boosted by the fact that the Hungarian pharmaceutical company signed an agreement with the US-based Eli Lilly, which includes a share buyback.
Jensen Huang, Nvidia's Chairman and CEO, has resigned; stock price of the most influential company in the AI boom plummets
US stock markets closed with moderate declines on Thursday: the S&P 500, the Dow Jones, and the Nasdaq all fell by 0.4%. The defining event of the trading day was the announcement by Jensen Huang, CEO of Nvidia, that he was stepping down in the wake of the Chinese espionage scandal that came to light earlier this week. Investors are concerned about the leadership change at the helm of a key player in the AI boom; as a result, Nvidia’s stock fell more than 14% during the day, though it recovered by the end of the session and ultimately closed down “only” 4.3%. Nvidia’s competitors welcomed the news, with AMD’s stock price rising 5.9% and Broadcom’s 5.5%. Alongside Nvidia, Chinese companies that use Nvidia chips also saw declines, such as Alibaba (-7.1%) and Tencent (-2.6%). The White House is also closely monitoring the situation; according to some White House officials, the possibility of removing Howard Lutnick from his commercial role has been discussed, as he failed to comply with the requirement to reduce chip exports to China.
Meanwhile, the price of Brent crude oil rose to about $96 per barrel on Thursday, marking its second consecutive day of gains and rebounding from the 10-week low of $91.50 reached on November 10. The price rise was fueled by US President Donald Trump’s statement that the United States no longer needs an agreement with Iran. This marked a sharp turnaround from his statement on Monday, when, following talks with the Qatari prime minister, he said the conflict was “practically over in military terms.” Meanwhile, Iran continues to show no willingness to soften its negotiating stance. Mohsen Rezaee, secretary of Iran’s Supreme National Security Council, stated that Tehran will not remove any enriched nuclear material from the country.
US yields rose again amid uncertainty in the Middle East
US bond yields reacted to renewed tensions in the Middle East and rising energy prices, with the two-year bond yield creeping up to 4.88% and the ten-year yield to 5.13%, representing increases of sixteen and fourteen basis points, respectively. In contrast, German bond yields rose only marginally. The dollar strengthened by 0.3% against the euro as investors anticipate an increased likelihood of an interest rate hike. Investors are currently pricing in an 85.5% probability of a rate hike at the next meeting in December.
As for domestic yields, short-term yields rose by only a few basis points, while longer-term yields rose by 5–6 basis points. The forint weakened slightly against the euro, closing at 365.25 on Thursday.
Today's highlights
Asian indices painted a mixed picture this morning: the Nikkei was up half a percent, on track to close out a strong week on a positive note following last week’s decline. The Japanese index was buoyed by favorable corporate reports and optimism surrounding AI companies, despite Nvidia’s setbacks. In contrast, the SSEC was down half a percent, and the Kospi was down one percent.
Today, the Hungarian Central Statistical Office (KSH) will release domestic construction output data for September, and third-quarter Polish GDP figures will also be published. Employment data for the eurozone will be released, while overseas, the October producer price index will be worth watching.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more