
OTP Morning Brief: CoreWeave shares soared nearly 25% yesterday
Related content
OTP Morning Brief: OTP reported earnings above analysts' expectations this morning
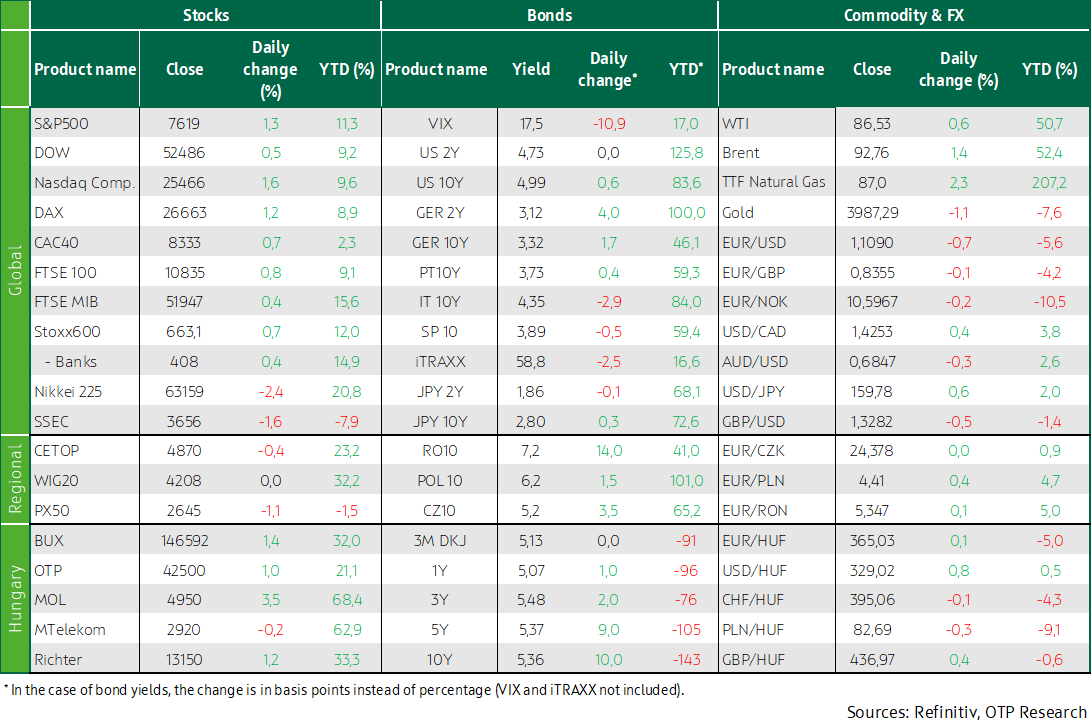
The US 10-year Treasury yield briefly climbed above 5% on Tuesday following the release of stronger-than-expected inflation data. Expectations for further Fed rate hikes strengthened, supported not only by the latest inflation data and last week’s exceptionally strong labour market figures, but also by hawkish comments from central bank policymakers. US equity indices weakened in the face of rising bond yields, with the IT sector emerging as the day's worst performer. In Europe, steadily declining oil prices provided further support to equity markets. The US dollar strengthened, with EUR/USD falling to 1.116. In Hungary, CPI accelerated to 2.0% in October, while core CPI rose to 2.1%. Hungarian long-term bond yields, however, edged lower, with the benchmark 10-year yield declining to 5.26%, its lowest level in nearly four months. The forint weakened alongside other regional currencies, albeit to a greater extent, with EUR/HUF edging up to 364.5. Investor attention is likely to focus on OTP’s Q3 earnings report released this morning.
OTP Morning Brief: Lower oil prices underpinned investor optimism
Major European and Wall Street indices closed Monday's trading session in positive territory, with gains broad-based across sectors. The positive sentiment was driven by lower oil prices after Donald Trump stated that a renewed strike against Iran was highly unlikely, provided there is progress in the negotiations. We saw a rebound in the technology sector after last week's sharp sell-off. The dollar weakened against the euro. The BUX climbed 1.8%, while all major Hungarian blue-chip stocks finished the session higher. The forint strengthened against the major currencies. October CPI figures for both Hungary and the US are due for release today.
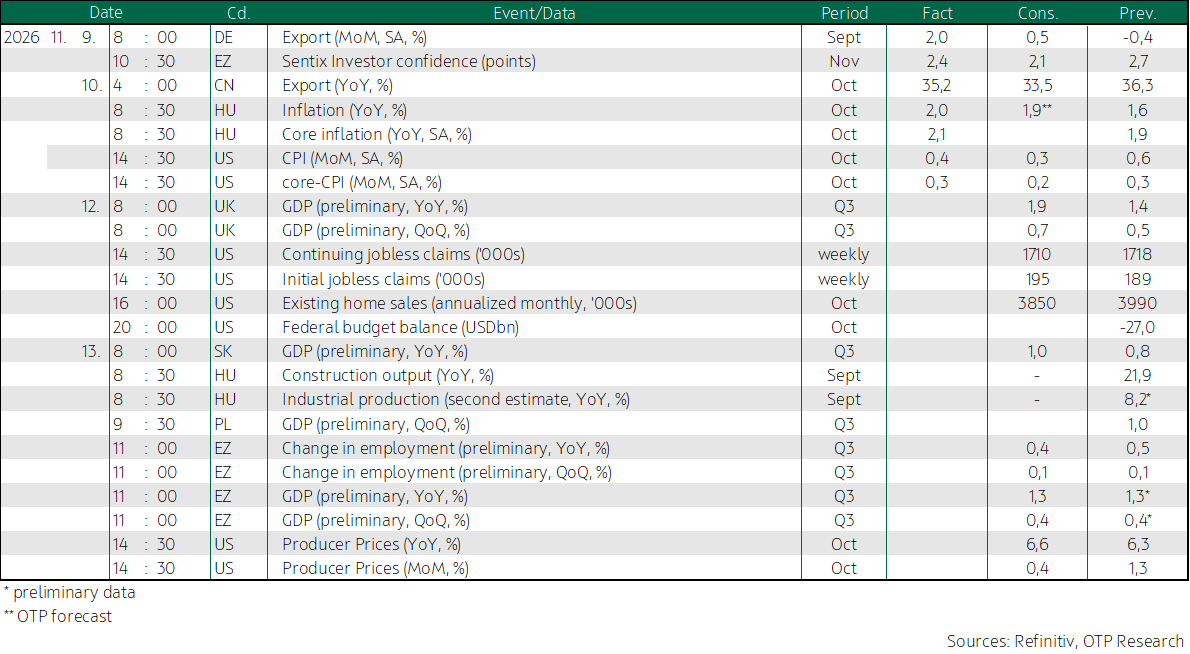
Major European indices advanced yesterday; optimism surrounding AI-related companies strengthened, while mostly favorable earnings reports emerged across Europe. Meanwhile, rising oil prices heightened inflationary pressures. Major US indices moved higher yesterday on the back of positive corporate developments; CoreWeave shares soared nearly 25%, while reports suggest strong investor interest in Anthropic’s IPO scheduled for next week. US bond markets were closed yesterday for a public holiday, while yields in Europe showed little change; oil prices rose following a renewed escalation of geopolitical tensions. Today, alongside the usual weekly US initial jobless claims data, housing market and federal budget figures will also be released, while the UK’s Q3 GDP data will provide further insight into economic performance.
European indices advanced yesterday as optimism surrounding AI-related companies strengthened, while mostly favorable earnings reports were released across Europe; meanwhile, rising oil prices heightened inflationary risks
Major European equity markets moved higher on Wednesday, extending the positive trend seen throughout the week, with the STOXX 600 gaining 0.7% to close at a fresh record high. Sentiment was primarily supported by strong performance in the technology sector after AI-linked CoreWeave issued upbeat guidance, while anticipation continued to build ahead of Anthropic’s planned IPO. Shares of ASML rose 3.1%, while Infineon advanced 6.3%. Corporate earnings also provided support for the market. Siemens Energy soared 10.8% on the back of record quarterly revenue and plans to more than triple its dividend, while RWE added 1.8% after reporting better-than-expected results. ABN Amro, which had traded higher earlier in the session following a 52% year-on-year increase in Q3 net profit, ultimately closed 0.9% lower. Meanwhile, wind turbine manufacturer Vestas fell 3% after posting weaker-than-expected quarterly earnings. Investors also remained focused on inflationary risks. Stronger-than-expected US inflation data released on Tuesday, combined with hawkish remarks from Federal Reserve officials and rising oil prices following attacks in the Strait of Hormuz, reinforced expectations of further rate hikes. At the same time, the President of the Bundesbank noted that the German economy is recovering faster than previously anticipated.
Major indices in the CEE region delivered mixed performance, with the BUX posting gains while the Prague index declined and the Warsaw market remained closed. Among Hungarian blue chips, MOL led the advance, rising 3.5% alongside higher oil prices. OTP also performed well following its earnings release, while Richter was the only major blue-chip stock to finish the day lower.
Major US indices moved higher yesterday on the back of positive corporate developments; CoreWeave shares soared nearly 25%, while reports suggest strong investor interest in Anthropic’s IPO scheduled for next week
US equity markets closed higher yesterday, driven primarily by the strong performance of companies linked to artificial intelligence. Shares of cloud infrastructure provider CoreWeave soared nearly 25% after the company reported better-than-expected revenue and raised its 2026 guidance. Nvidia gained 2.9%, recovering part of the sharp decline recorded earlier this week. Investor sentiment was further supported by reports of strong demand for the upcoming IPO of AI developer Anthropic, whose valuation could reach as much as $1.4 trillion, although this remains below the previously anticipated $2.0 trillion. Positive corporate news helped offset concerns stemming from Tuesday’s unfavorable US inflation data. According to the report released a day earlier, the US Consumer Price Index rose 0.4% month-on-month in October, exceeding market expectations and reinforcing bets that the Federal Reserve could raise interest rates again in December. CME FedWatch data indicated that markets were pricing in an approximately 88% probability of a 25-basis-point rate hike as of Wednesday evening. Overall, trading continued to be shaped by inflation and interest rate expectations; however, strong corporate earnings and optimism surrounding the AI sector outweighed concerns about monetary policy, resulting in broad-based gains across US equity markets.
US bond markets were closed yesterday for a public holiday, while yields in Europe showed little change; oil prices rose following a renewed escalation of geopolitical tensions
There was no trading on US bond markets yesterday due to Veterans Day, leaving yields unchanged following the sharp rise triggered by Tuesday’s US inflation data. In contrast, European markets remained open, with trading conditions stabilizing after the previous session’s sell-off. The yield on the 10-year German Bund edged slightly higher, while its French counterpart eased marginally. Hungarian yields beyond the one-year segment moved higher during the day, with the 10-year benchmark rising by 10 basis points to close at 5.36% after Tuesday’s decline, although it remained well below the elevated levels seen at the end of October. The Hungarian forint weakened modestly against the euro.
Oil prices rose yesterday as geopolitical tensions in the Middle East returned to the forefront. Iran signaled that it is unwilling to give up its stockpile of enriched nuclear material, reducing expectations for a swift resolution to the conflict. Market attention remained focused on security conditions around the Strait of Hormuz, where 37 vessel attacks were recorded in October, marking the highest monthly total since the conflict began. Fresh incidents were also reported this week: a tanker was struck off the coast of Oman, while Iran’s Revolutionary Guard stated that two tankers caught fire after hitting naval mines. Meanwhile, renewed Ukrainian attacks on Russian oil infrastructure provided additional support for prices. The advance was partially capped by data from the API showing that US crude oil inventories increased by 9 million barrels last week. Overall, supply-side risks continued to exert upward pressure on oil prices.
Today's highlights
Asian equity markets were trading lower this morning, alongside weaker US equity futures. Investor sentiment was weighed down by uncertainty surrounding Nvidia’s leadership after media reports suggested that the company’s board is considering replacing CEO Jensen Huang. Market participants fear that any instability at Nvidia could have negative implications for Asian suppliers and companies linked to artificial intelligence, given the firm’s pivotal role in the AI ecosystem.
Today, alongside the usual weekly US initial jobless claims data, housing market and federal budget figures will also be released, while the UK’s Q3 GDP data will provide further insight into economic activity.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more