
OTP Morning Brief: Investor sentiment improved following the Democrats’ congressional victory and the decline in oil prices
Related content
OTP Morning Brief: Democrats may secure majorities in both chambers of Congress in the midterm elections
Western European stock indices edged lower on a macroeconomically quiet day. US markets closed mixed. The tech-heavy Nasdaq rose, while concerns over memory chip prices weighed on Apple shares and supported gains in Micron Technology and Nvidia. The number of job openings in the US surged. Favourable macroeconomic data pushed bond yields higher on Tuesday. However, the focus remained on the midterm elections: based on the results available by this morning, a significant Democratic victory was taking shape, potentially allowing Democrats to secure majorities in both chambers of Congress. October CPI data for the eurozone is due for release today. Among others, McDonald’s and Novo Nordisk are set to report earnings today.
OTP Morning Brief: Markets focus on the US midterm elections today
Major European indices rose yesterday; German retail sales fell sharply on a monthly basis, while Hungary’s manufacturing PMI declined slightly. Major US indices closed mixed, while US manufacturing activity continued to strengthen; however, construction spending declined on a monthly basis following the previous month’s increase. US long-term yields edged lower, while rates in Europe were little changed; following the declines seen in recent days, the Hungarian 10-year government bond yield rose slightly. The US midterm elections take place today, determining whether the Republican Party can retain its majority in both the House of Representatives and the Senate. In addition, data on US factory orders and job openings will be released today.
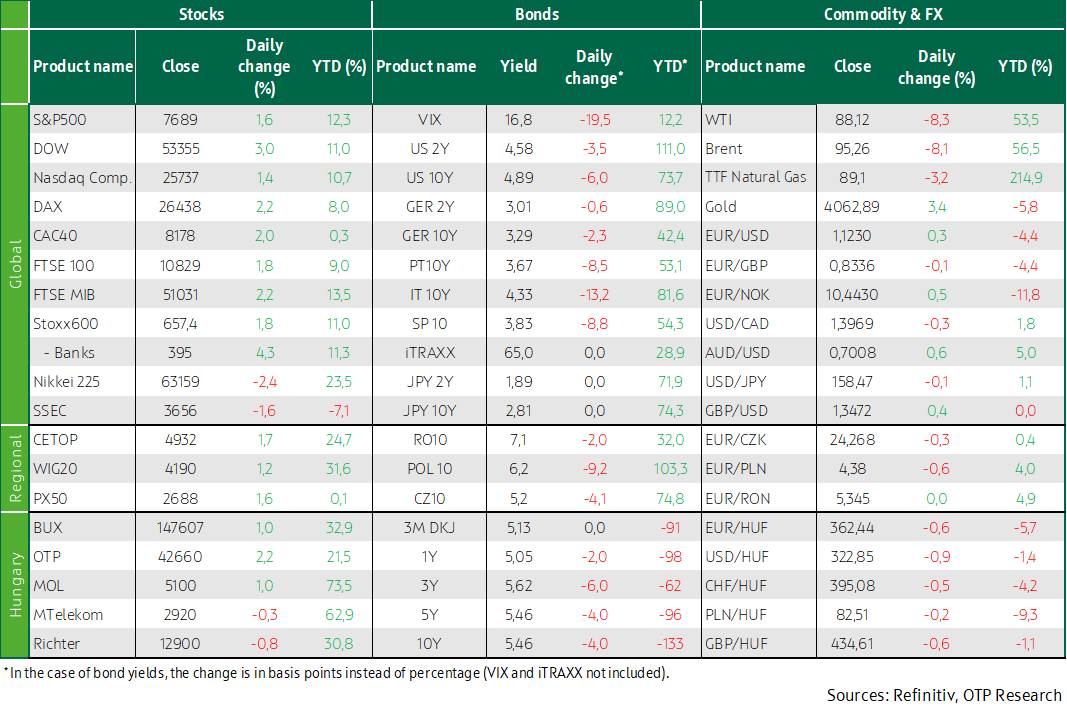
Lower bond yields and oil prices, driven by the Democrats’ expected congressional majority, improved market sentiment. Brent crude has fallen by roughly 20% since the beginning of the week, while the yield on the 10-year US Treasury note declined by 6 basis points to 4.89%. Amid the favourable risk environment, the US dollar weakened, with the EUR/USD exchange rate rising to near 1.123. In Europe, positive corporate news also supported market sentiment, with the STOXX 600 index rising by 1.8%, while shares of Novo Nordisk gained 5.6% after the company raised its full-year guidance. Today, investors will focus on German industrial orders, French industrial production and the euro area producer price index, alongside interest rate decisions by the Bank of England and the Czech central bank. In the US, weekly initial jobless claims, as well as Q3 productivity and labour cost data, will also be in the spotlight.
Increased risk appetite following the US election results supported the major European equity indices
Trading on European equity markets was buoyant as the Democratic Party secured a majority in both chambers of the US Congress, while a series of corporate earnings releases also lent support to sentiment. The STOXX 600 index rose by 1.8%. Financial stocks outperformed, supported by more favourable regulatory expectations, while renewable energy companies also posted gains. Among company-specific movers, Novo Nordisk stood out with a 5.6% advance after raising its full-year guidance. In contrast, the technology sector lagged behind amid expectations of tighter regulation targeting the US AI and data centre industries.
The major Western European equity indices all closed significantly higher. The DAX gained 2.2%, the CAC 40 advanced 2.0%, while the FTSE 100 rose 1.8% compared with the previous day's close. The German market delivered the strongest performance, supported by positive global sentiment and a number of encouraging corporate earnings reports.
Regional equity markets also posted positive performances, with Hungary’s BUX rising 1.0%, Poland’s WIG20 gaining 1.2%, and the Czech PX50 index advancing 1.6%.
Hungarian blue-chip stocks delivered mixed performances. Shares of OTP gained 2.2%, while MOL advanced 1.0%. In contrast, Magyar Telekom fell 0.3%, and Richter declined 0.8%.
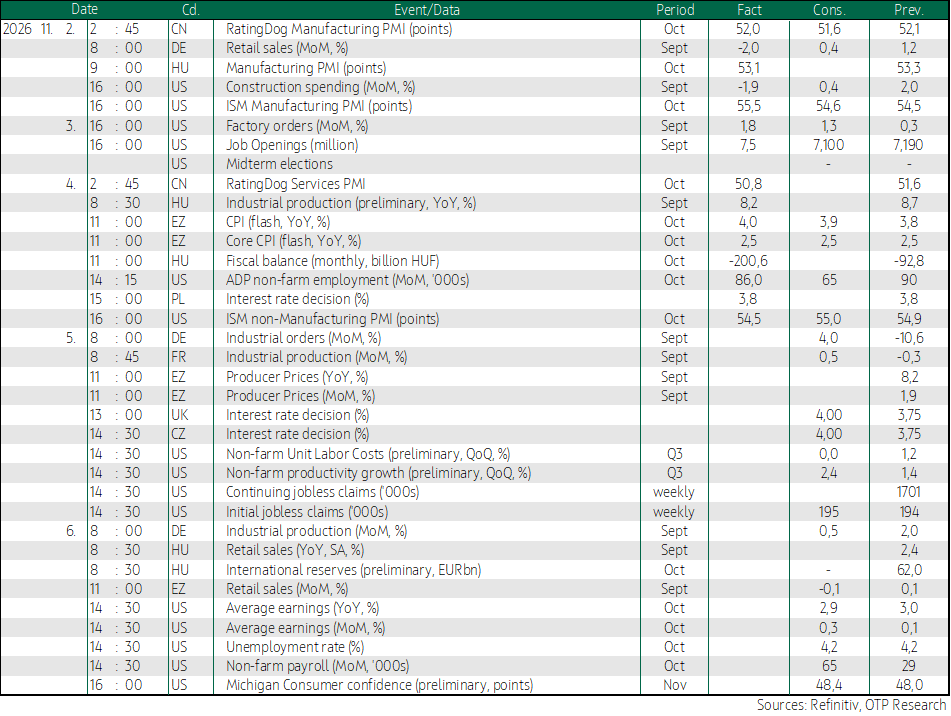
In the euro area, CPI accelerated to 4.0% in October from 3.8% in September, marking a three-year high and remaining well above the European Central Bank's 2% target. The increase was driven primarily by faster growth in energy prices, while core inflation remained unchanged at 2.5%. The data strengthened expectations that the ECB could deliver another rate hike in December.
In Hungary, industrial production expanded by 8.2% year-on-year in September, following 8.7% growth in August. The increase was driven primarily by vehicle manufacturing, as well as the production of electronic and electrical equipment, while output in the food, beverage and tobacco industries declined. Meanwhile, the central government budget posted a deficit of HUF 200.6bn in October.
The National Bank of Poland left its benchmark interest rate unchanged at 3.75%, in line with market expectations, marking the seventh consecutive meeting at which policymakers refrained from altering borrowing costs.
Major US indices advanced as the Democratic congressional victory and the decline in oil prices supported market sentiment
Investor sentiment was primarily supported by the outcome of the US midterm elections, as the Democratic Party gained control of both chambers of Congress. Markets welcomed the prospect that a divided political landscape could reduce the likelihood of unpredictable policy moves and volatile military interventions. A sharp correction unfolded in the oil market, with Brent crude settling at USD 94.89 per barrel following an 8.4% decline, while WTI closed at USD 88.30 after falling 8.1%, as investors saw growing chances of a resolution to the conflict with Iran.
The major US equity indices closed higher. The Dow gained 3.0%, while the S&P 500 advanced 1.6% and the Nasdaq added 1.4%. At the sector level, consumer goods companies outperformed, whereas energy stocks came under pressure following the sharp decline in crude oil prices. Performance across technology and artificial intelligence-related stocks was mixed. Some investors expect that stricter regulation under a Democratic-controlled Congress could slow the pace of data centre investment. Among the large-cap technology names, Microsoft rose 6.7%, Amazon gained 6.1%, Alphabet advanced 3.2%, and Meta Platforms added 1.4%. In contrast, data centre operators suffered notable losses, with IREN falling 11% and Core Scientific declining 10%. The Philadelphia Semiconductor Index closed 3.1% lower, although AMD edged up 1.0% on the back of better-than-expected growth prospects.
Macroeconomic data painted a mixed picture of the US economy. The ISM Services PMI edged down to 54.5 in October from 54.9 in the previous month, pointing to a moderation in the growth of the services sector. According to the survey, companies continue to view tariff-related pressures and rising fuel costs as their key risks. At the same time, the ADP employment report showed that the private sector added 86,000 jobs in October, surpassing market expectations of 69,000.
US yields declined and the dollar weakened amid improving risk sentiment
US Treasury yields moved lower across the curve. The yield on the 2-year Treasury note declined by 3 basis points to 4.58%, while the benchmark 10-year yield fell 6 basis points to 4.89%. Meanwhile, the 30-year Treasury yield eased by 5 basis points to 5.28%. The sharp decline in oil prices helped alleviate inflation concerns, supporting demand for government bonds and putting downward pressure on yields.
In the foreign exchange market, the US dollar weakened against major currencies. The US Dollar Index declined by 0.25%, while the EUR/USD exchange rate rose to near 1.1229. Sterling also strengthened against the dollar ahead of the Bank of England’s policy decision. Bond market moves were more subdued in Europe, with the yield on the German 2-year government bond edging down by 1 basis point to 3.01%.
The positive mood in global bond markets also provided support to Hungarian assets. Yields along the Hungarian government bond curve moved moderately lower, with the 3-year benchmark yield falling by 6 basis points to 5.62% and the 5-year yield declining by 4 basis points to 5.46%, while the 10-year benchmark yield closed 4 basis points lower at 5.46%. The forint strengthened by 0.6% against the euro, ending the session at 362.5, while USD/HUF traded around 322.8 by the close of trading.
Today's highlights
Asian technology stocks came under pressure this morning as investors priced in tighter regulation of the data centre and AI sectors following the Democrats’ congressional victory. South Korea’s KOSPI fell 4.0%, while Taiwan’s benchmark index and Japan’s Nikkei both closed 1.8% lower. Weakness in companies linked to data centre investment and the semiconductor sector weighed heavily on regional trading.
Today, investors will focus on German industrial orders, French industrial production and the euro area producer price index. In addition, both the Bank of England and the Czech central bank are set to announce interest rate decisions, while in the US, weekly initial jobless claims as well as Q3 productivity and labour cost data are due for release.
Among today's earnings releases, Deutsche Telekom, Rheinmetall, Toyota and ConocoPhillips are scheduled to report quarterly results.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more