
OTP Morning Brief: Democrats may secure majorities in both chambers of Congress in the midterm elections
Related content
OTP Morning Brief: Markets focus on the US midterm elections today
Major European indices rose yesterday; German retail sales fell sharply on a monthly basis, while Hungary’s manufacturing PMI declined slightly. Major US indices closed mixed, while US manufacturing activity continued to strengthen; however, construction spending declined on a monthly basis following the previous month’s increase. US long-term yields edged lower, while rates in Europe were little changed; following the declines seen in recent days, the Hungarian 10-year government bond yield rose slightly. The US midterm elections take place today, determining whether the Republican Party can retain its majority in both the House of Representatives and the Senate. In addition, data on US factory orders and job openings will be released today.
OTP Morning Brief: Further increase in energy prices, stock market correction in the US
On Friday, and over the course of last week as a whole, both oil and gas prices continued to rise. This longer-term trend was also reflected in the October inflation data released on Friday across eurozone member states, with CPI continuing to increase. At the same time, the better-than-expected Q3 GDP figures for the region, which were also published on Friday, continued to point to strong economic resilience. Stock prices declined in Europe and, even more markedly,in the US, with the Nasdaq posting its largest single-day drop since June,falling 3%. Bond yields edged lower, while Hungarian 10-year government bond yields declined significantly, falling by nearly 20 basis points.
Western European stock indices edged lower on a macroeconomically quiet day. US markets closed mixed. The tech-heavy Nasdaq rose, while concerns over memory chip prices weighed on Apple shares and supported gains in Micron Technology and Nvidia. The number of job openings in the US surged. Favourable macroeconomic data pushed bond yields higher on Tuesday. However, the focus remained on the midterm elections: based on the results available by this morning, a significant Democratic victory was taking shape, potentially allowing Democrats to secure majorities in both chambers of Congress. October CPI data for the eurozone is due for release today. Among others, McDonald’s and Novo Nordisk are set to report earnings today.
Western European indices edged lower on a macroeconomically quiet day
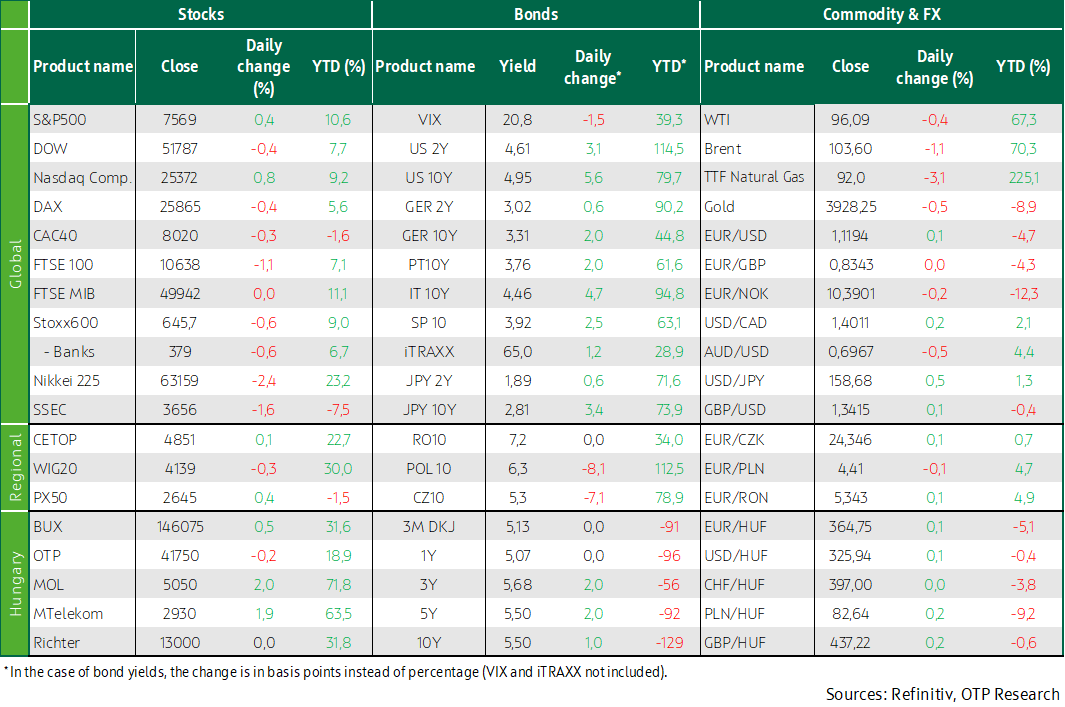
Following Monday’s gains, major Western European indices moved lower on Tuesday. The STOXX 600 fell 0.6%, while the DAX and CAC 40 each declined 0.4%, and the FTSE 100 dropped 1.1%. On the corporate front, shares of German online fashion retailer Zalando tumbled 6.6%, marking the largest daily decline within the STOXX 600, as slightly better-than-expected revenue failed to offset the company’s net loss. The broader retail sector weakened by 2%, while technology stocks lost nearly 1%. Shares of ASML, widely seen as a key beneficiary of AI investment, declined 1.6%. German pharmaceutical and agricultural group Bayer gained 3.6% after raising its 2026 profit guidance. Lufthansa advanced 3.9% as analysts generally viewed its results as resilient despite the airline lowering its full-year profit outlook. Philips rose 4.8% after reaching a preliminary agreement with the US Department of Justice regarding the closure of investigations related to the Dutch company’s 2021 global recall of respiratory and sleep therapy devices. Shares of sportswear manufacturer Adidas fell 2.8% after UBS downgraded the stock from neutral to sell.
No major macroeconomic data was released from the eurozone. European benchmark TTF natural gas prices declined 3.1% to around EUR 92. EU gas storage facilities were 74.3% full, nearly 9 percentage points below the level recorded on the same day last year. Brent crude prices extended their decline on Tuesday, falling a further 1.1%.
In Hungary, the BUX gained 0.5%, while the regional PX50 index rose 0.4%, whereas the WIG20 slipped 0.3%.
A significant Democratic victory appears to be taking shape in the early results
While investors awaited the outcome of the midterm elections, US equity indices closed mixed again on Tuesday. The Nasdaq Composite rose 0.8% and the S&P 500 gained 0.4%, while the Dow Jones slipped 0.4%. Shares of Apple fell 1.9% after the company warned that memory chip costs continue to rise, putting pressure on holiday-quarter gross margins. By contrast, memory chip manufacturer Micron Technology advanced 2.6%, while Nvidia gained 2.3%. The Philadelphia Semiconductor Index, which tracks the broader semiconductor sector, climbed 2.6%. Microsoft and Amazon also rose more than 2%. Palantir Technologies, a developer of AI-driven analytics software, forecast fourth-quarter revenue above market expectations following stronger-than-expected Q3 results; nevertheless, its share price declined 1.65%. AMD reported better-than-expected Q3 earnings and surged more than 5% in after-hours trading after gaining 3.65% during Tuesday’s session.
Among the S&P 500 sector indices, consumer staples and materials recorded the steepest declines. Shares of Gartner plunged 13.2%, while US-listed shares of Thomson Reuters fell 9.9% and Shopify dropped 8.7% after all three companies released their quarterly results.
Based on the results available this morning, the midterm elections appear to have delivered a decisive Democratic victory, potentially giving Democrats control of both chambers of Congress. The scale of the win is underscored by Democratic Senate gains in traditionally Republican strongholds such as South Carolina, Texas and Ohio.
President Trump announced that Washington will end its annual USD 4 billion aid package to Israel after the end of this year. The support has so far been provided in the form of military assistance. The US also carried out what it described as defensive strikes on Qeshm Island in Iran.
On the macroeconomic front, incoming data continued to point to a resilient labour market. The number of job openings surged by 333,000 to 7.523 million at the end of September, well above the analyst consensus of 7.1 million. The number of voluntary resignations also increased, signalling strengthening worker confidence.
Strong macroeconomic data pushed US yields higher on Tuesday
Labour market data and stronger-than-expected factory orders both pointed to the continued strength of the US economy, putting upward pressure on bond yields. The US 10-year Treasury yield rose 6 basis points to 4.95% on Tuesday. News of a Democratic victory initially sent Nasdaq futures down more than 2%, as investors may have started pricing in tighter regulation of the AI sector. The yield on the safe-haven US 10-year Treasury briefly fell back toward the 4.9% level, but both Nasdaq futures and benchmark yields later recovered significantly. Germany’s 10-year government bond yield increased by 2 basis points to 3.33%. The EUR/USD exchange rate was broadly unchanged at 1.119 on Tuesday before weakening by around 0.3% by Wednesday morning.
Hungarian government bond yields showed little movement on Tuesday, with the 10-year benchmark yield edging up 1 basis point to 5.5%. The forint closed marginally weaker against the euro at 364.75. Meanwhile, the Government Debt Management Agency (ÁKK) sold HUF 21 billion of discount treasury bills maturing in February at an average yield of 5.16%.
Today's highlights
Asian markets remained mixed this morning. Approaching the close, Japan’s Nikkei was down 1.7%, while China’s SSEC was up 1.8%. South Korea’s KOSPI was trading around 0.2% higher, and Hong Kong’s Hang Seng was gaining approximately 1.1%.
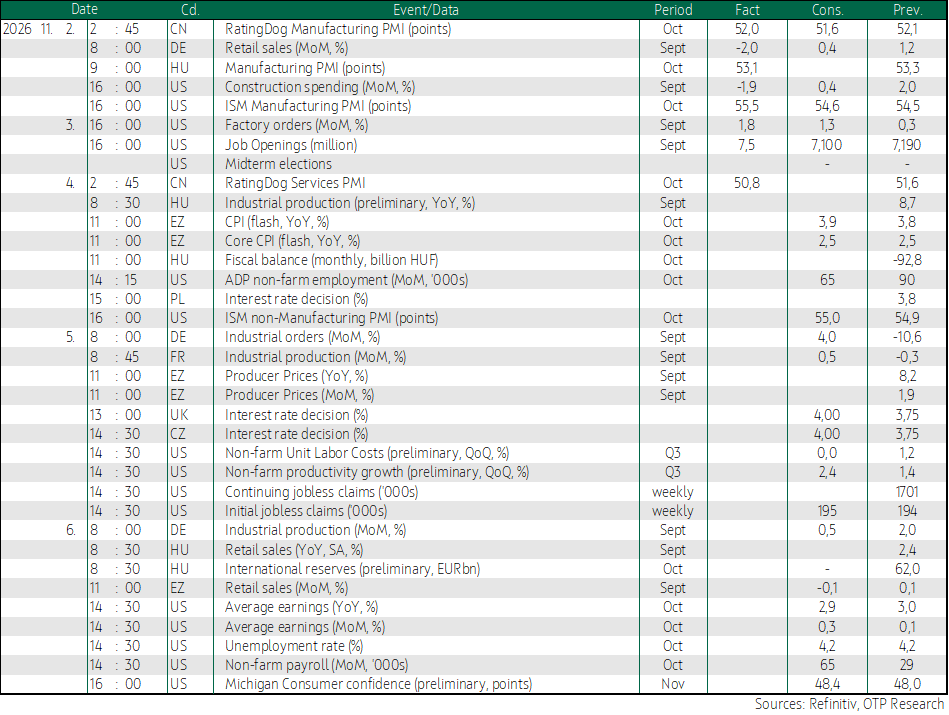
Following the release of national data, the eurozone’s October CPI reading is due today and, according to market consensus, may show a further year-on-year acceleration. In Hungary, September industrial production figures and the October budget balance will be published. Meanwhile, the National Bank of Poland is set to hold its interest rate decision meeting.
Among others, McDonald’s and Novo Nordisk are set to report their quarterly earnings today.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more