
OTP Morning Brief: The Fed left its benchmark interest rate unchanged as market attention turns to the ECB’s decision
Related content
OTP Morning Brief: Investor sentiment improved ahead of the Fed decision; strong corporate earnings supported markets
Strong corporate earnings and optimism surrounding the technology sector supported equity markets on both sides of the Atlantic. In Europe, the STOXX 600 rose 0.5%, while in the US the S&P 500 gained 0.6%, with the Nasdaq closing 1.2% higher. The BUX gained 1.9%, driven primarily by the strong performance of OTP. In bond markets, short-term US Treasury yields edged higher, while yields declined across Europe. The Hungarian forint traded steadily, while today’s focus will be on the Fed’s interest rate decision, along with earnings reports from Microsoft, Alphabet, Meta Platforms, UBS, Deutsche Börse and Mercedes-Benz.
OTP Morning Brief: News of Anthropic's potential stock market debut drove the rally in the technology sector
Major European and US equity indices moved higher. In Europe, the defence sector led the gains, while technology stocks spearheaded the rally in the US. Anthropic submitted documentation for its stock market listing, putting the spotlight back on AI investment spending. Saudi Arabia and Iran held talks aimed at easing tensions between the two countries, while crude oil prices edged lower. There was little movement in developed bond markets, with investors focusing on the ECB's and the Fed's interest rate decisions due later this week. The US dollar extended its gains against the euro. The BUX climbed by more than 1% yesterday. The Hungarian forint continued to weaken against the major currencies. The earnings season continues today with major names such as Coca-Cola and Boeing reporting results.
The wait-and-see sentiment ahead of the ECB’s rate decision led to limited movements across European equity markets, while individual stock performance was driven primarily by corporate earnings releases. Wall Street closed modestly higher after the Fed left its benchmark interest rate unchanged, in line with expectations. Strengthening supply risks continued to drive energy prices higher, with the TTF benchmark soaring to its highest level since the 2022 energy crisis. While yields rose across US and European bond markets, the decline in the Hungarian government bond market continued. Today's focus is on the ECB’s rate decision, as well as the US GDP release and the core PCE inflation gauge closely monitored by the Fed. In addition to macroeconomic data, the earnings season continues, with Amazon among the companies set to report its quarterly results.
Corporate earnings drove European equity markets amid a wait-and-see mood ahead of the ECB decision
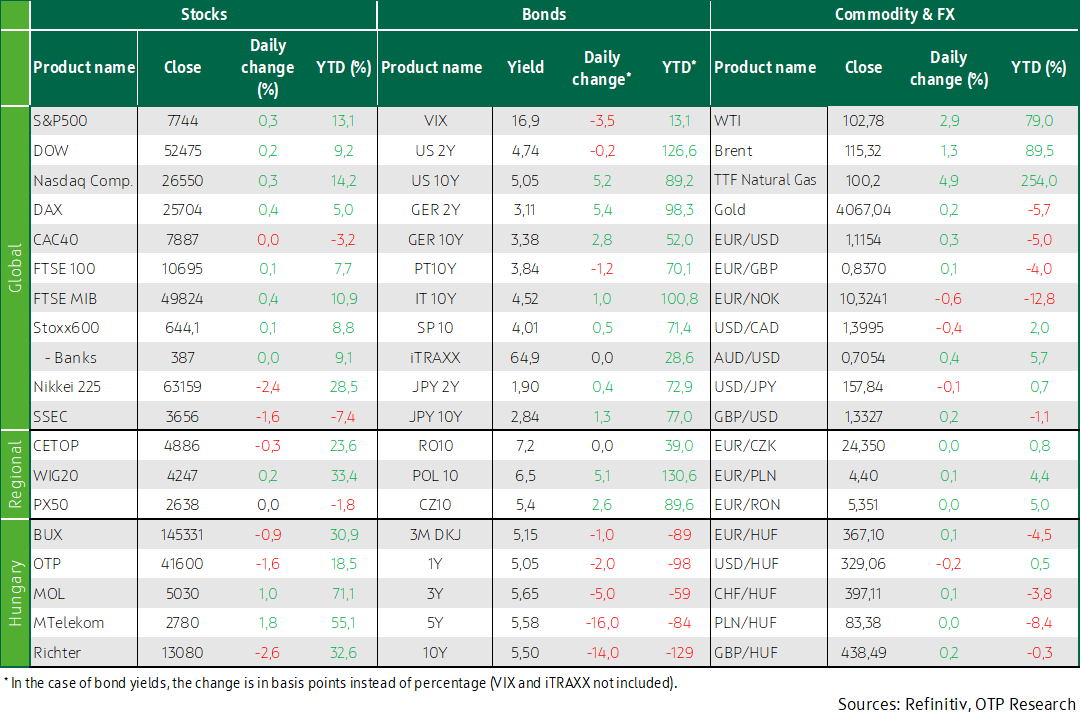
Ahead of the ECB’s rate decision on Thursday, European equity markets remained in wait-and-see mode, with the STOXX 600 index edging up just 0.1%. At the sector level, oil and gas stocks outperformed on the back of rising energy prices, while automakers benefited from favourable company-specific news. In contrast, the media and chemicals sectors underperformed, and mining stocks came under pressure as declining copper prices weighed on the industry.
Individual stock moves were primarily driven by earnings releases. Within the banking sector, shares of Deutsche Bank advanced following better-than-expected quarterly results, while Standard Chartered gained after raising its full-year targets. In contrast, Santander lost more than 5% of its value due to weaker performance in Brazil, which also weighed on the Spanish equity market. Among the day’s biggest losers was Adyen, which suffered a double-digit share price decline after lowering its profitability target. Thyssenkrupp also came under heavy selling pressure, with its shares falling sharply as investors reacted negatively to the stock market debut of its metals and materials trading division.
The major Western European equity indices also recorded only modest moves, with the FTSE 100 rising 0.1% and the DAX gaining 0.4%, while the CAC 40 was essentially flat.
Regional equity markets delivered mixed performance: Poland’s WIG20 rose 0.2%, while the Czech PX50 closed virtually unchanged. In contrast, the BUX fell by nearly 1%. The Hungarian benchmark was dragged lower primarily by declines in OTP and Richter, whose shares dropped 1.6% and 2.6%, respectively. Meanwhile, Magyar Telekom and MOL both ended the day higher.
Wall Street closed modestly higher following the Fed’s widely expected policy decision
The Fed left its benchmark interest rate unchanged at a target range of 3.75% to 4.00% at its October meeting, in line with market expectations. In its policy statement, the central bank struck a more constructive tone on the performance of the US economy than previously, while emphasizing that inflation remains elevated and leaving the door open to further monetary tightening. According to CME FedWatch data, markets are currently assigning a probability of more than 80% to a 25-basis-point rate hike in December.
The major Wall Street indices closed Wednesday's session with modest gains following the widely expected interest rate decision. The Dow Jones rose 0.2%, while both the S&P 500 and the Nasdaq advanced 0.3%.
The earnings season continued to paint a favourable picture, with 84% of the S&P 500 companies that have reported so far delivering results above consensus expectations. The technology sector was supported by semiconductor manufacturers after SK Hynix reported a significant increase in profits, providing a positive signal for chip demand linked to AI development. After the market close, shares of Microsoft surged more than 4% following strong quarterly results, driven in particular by the better-than-expected performance of its Azure cloud business. In contrast, Alphabet fell more than 7% after releasing its earnings report.
Oil prices continued to rise on Wednesday as supply risks in the Middle East intensified. Yemen’s Houthis attacked Aden Airport, one day after claiming responsibility for a missile strike on one of Saudi Arabia’s largest oil refineries. The rally was further supported by US inventory data: according to the Energy Information Administration (EIA), crude oil inventories fell by 1.9 million barrels last week, whereas analysts had expected a modest build of 15,000 barrels. Brent crude rose 1.3% to USD 115.3 per barrel, while WTI surged nearly 3% to USD 102.8 per barrel.
The TTF benchmark soared nearly 5% to above EUR 100/MWh, a level not seen since the 2022 energy crisis. Prices continue to be driven higher by disruptions to LNG supplies linked to the conflict in the Middle East, while Europe entered the heating season with gas storage levels below historical averages.
International and Hungarian bond markets moved in opposite directions
Longer-dated US Treasury yields moved higher after the Fed upgraded its assessment of economic conditions, with the 10-year yield rising 5.2 basis points to 5.05%. Meanwhile, the 2-year yield was broadly unchanged from the previous day, widening the spread between the two maturities to 31 basis points, which may reflect improving market expectations for economic growth.
Yields on European government bond markets also moved higher on Wednesday, driven primarily by rising oil prices. Germany’s 10-year benchmark yield climbed nearly 3 basis points to 3.38%, while the French 10-year yield increased to 4.93%. Shorter maturities also came under upward pressure, with the German 2-year government bond yield edging up 5.4 basis points to 3.11%. In the currency market, the euro strengthened modestly against the dollar following the Fed’s policy decision, gaining 0.3%, with the EUR/USD exchange rate closing at 1.115.
In contrast to developments in international bond markets, Hungarian yields continued to decline on Wednesday, with yields across the 5- to 20-year segment falling by 10-16 basis points compared to the previous day. According to the Government Debt Management Agency (ÁKK)'s early afternoon quotation, the 10-year benchmark yield stood at 5.50%. The forint traded steadily, weakening slightly against the euro while posting a modest gain versus the dollar. The EUR/HUF exchange rate closed at 367.10, while USD/HUF ended the session at 329.06.
Today's highlights
Alphabet’s disappointing earnings report dampened the momentum of the previous day’s technology rally across Asian markets. As of 7:00 a.m. Budapest time, South Korea’s KOSPI was down around 1%, while China’s Shanghai Composite also traded in negative territory and the Hang Seng was broadly unchanged. In contrast, Japan’s Nikkei 225 gained nearly 1% after Advantest, a manufacturer of testing equipment widely used by AI chipmakers, raised its profit outlook.
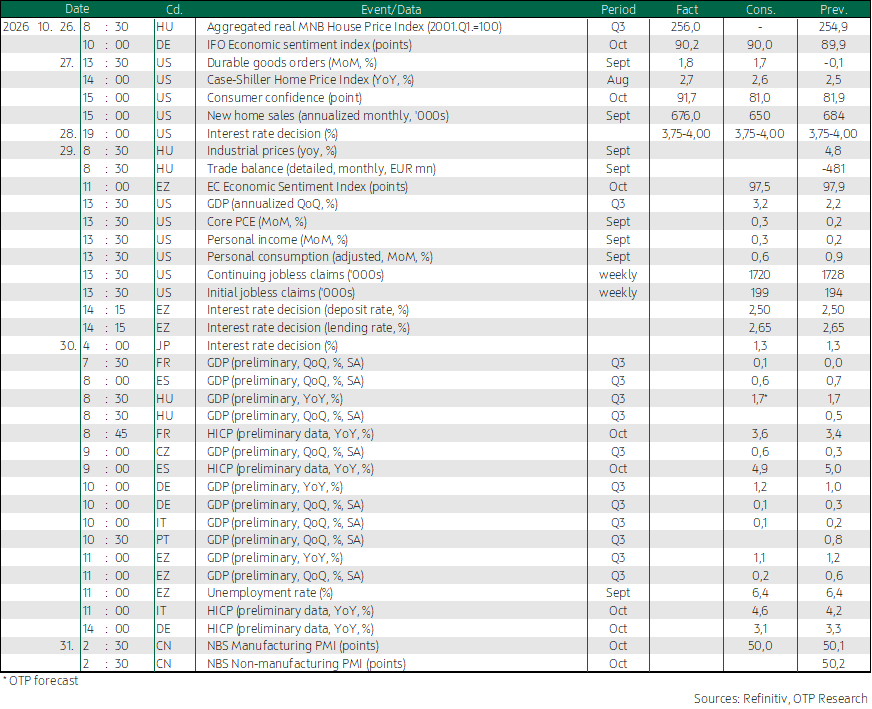
Investors’ attention today will be focused primarily on the ECB’s rate decision, where benchmark interest rates are expected to remain unchanged. As a result, market reactions are likely to be driven mainly by the accompanying communication. The day’s key macroeconomic release will be the first estimate of US third-quarter GDP growth. In addition, markets will receive the Fed’s preferred core PCE inflation gauge, September personal income and consumer spending data, as well as the latest weekly jobless claims figures. Alongside macroeconomic releases, the earnings season continues, with Amazon among the companies scheduled to report quarterly results.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more