
OTP Morning Brief: Investor sentiment improved ahead of the Fed decision; strong corporate earnings supported markets
Related content
OTP Morning Brief: Stocks started the week in the red; Nvidia earnings are due today
Stocks closed lower on Monday, while the dollar continued to strengthen, pushing the EUR/USD exchange rate below 1.10, and oil prices declined sharply. Eurozone industrial production rose by 0.2% month-on-month in September. Today, investors will focus on the UK unemployment data, Germany’s ZEW Economic Sentiment Index, the MNB’s interest rate decision, as well as US retail sales and industrial production figures. Among corporate earnings releases, investors should keep a close eye on results from Nvidia, Home Depot, and Walt Disney.
OTP Morning Brief: Rate hike expectations moved higher again
The Stoxx 600 closed at a record high, rising 2.4% on a weekly basis. It outperformed the US indices both in November and throughout the autumn period. Although Brent rebounded in the second half of last week, it still ended the week down 2.5%, closing at around USD 96 per barrel. Amid the Jensen Huang scandal, Nvidia fell nearly 6% last week; nevertheless, the US indices still gained more than 2%, led in part by Broadcom and AMD. On Friday, the US 10-year Treasury yield rose a further 5 basis points to 5.15%, bringing its weekly increase to 29 basis points. Rate hike expectations moved higher in both the US and Europe, with markets pricing in three rate hikes over the next 12 months. Moreover, markets expect all three rate hikes to be delivered by March in the US, providing further support to the dollar. The recovery of Hungarian industry continued in September. This week, investors will be paying close attention to US economic indicators, negotiated wage data from Europe, and in Hungary, the MNB’s rate decision as well as Moody’s sovereign rating review.
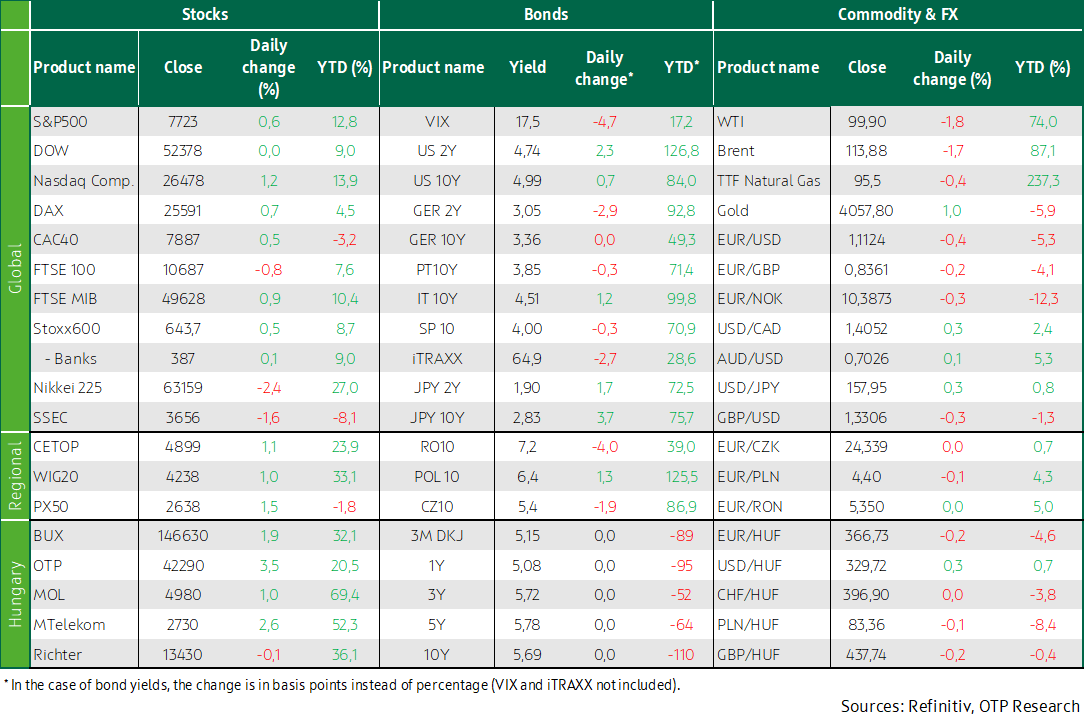
Strong corporate earnings and optimism surrounding the technology sector supported equity markets on both sides of the Atlantic. In Europe, the STOXX 600 rose 0.5%, while in the US the S&P 500 gained 0.6%, with the Nasdaq closing 1.2% higher. The BUX gained 1.9%, driven primarily by the strong performance of OTP. In bond markets, short-term US Treasury yields edged higher, while yields declined across Europe. The Hungarian forint traded steadily, while today’s focus will be on the Fed’s interest rate decision, along with earnings reports from Microsoft, Alphabet, Meta Platforms, UBS, Deutsche Börse and Mercedes-Benz.
Earnings season and easing oil prices improved sentiment in Europe
Investor sentiment improved across European equity markets, supported by strong corporate earnings and lower oil prices. The pan-European STOXX 600 rose 0.5%, with the technology and mining sectors outperforming. Among the top gainers were Besi and AT&S, with the former benefiting from Applied Materials’ announcement of an increased stake in the company. Company-specific news from Novartis also supported sentiment after the drugmaker raised its full-year operating profit guidance despite significant one-off write-downs. However, sentiment was partly weighed down by HSBC’s weak revenue performance.
Major Western European indices closed mixed. The DAX gained 0.7% and the CAC 40 rose 0.5%, while the FTSE 100 fell 0.8%, weighed down by HSBC’s sharp decline. Markets remain focused on Thursday’s ECB rate decision and the central bank’s accompanying communication.
Regional equity markets performed strongly, with the BUX rising 1.9% to its highest level in nearly a month, while Poland’s WIG20 gained 1.0% and the Czech PX Index advanced 1.5% compared with the previous day’s close.
Most domestic blue chips posted strong gains, providing meaningful support to the BUX. OTP surged 3.5%, Magyar Telekom rose 2.6%, and MOL closed 1.0% higher, while Richter edged down 0.1%.
AI optimism and strong earnings supported Wall Street
Among the major US indices, gains in technology stocks primarily lifted the Nasdaq, which rose 1.2%, while the S&P 500 advanced 0.6%; the Dow, meanwhile, closed virtually unchanged. News surrounding Anthropic’s upcoming IPO provided fresh momentum for the semiconductor sector, while investors also welcomed expectations ahead of the Fed meeting that policymakers would leave the benchmark interest rate unchanged. Among sectors, technology was the strongest performer, whereas energy lagged amid a pullback in oil prices.
Among company-specific developments, the deepening partnership between Nvidia and Meta stood out, with Nvidia making a $3 billion investment as part of Meta’s capital raise. Coca-Cola raised its full-year earnings guidance after demand for its zero-sugar beverages and premium products remained strong, with both revenue and earnings exceeding expectations. Visa reported stronger-than-expected profit growth, supported by resilient consumer demand and continued strength in travel and services spending. UPS and Royal Caribbean also upgraded their full-year outlooks, while Boeing fell 10.7% after reporting a larger-than-expected quarterly loss and signaling a slower production ramp-up for its 737 program.
Geopolitical developments also remained in focus for investors. In Israel, election exit polls pointed to a political deadlock, raising the prospect of prolonged coalition negotiations or even another election. Meanwhile, markets continued to monitor the conflict in the Middle East and its implications for commodity markets. In Latin America, the spotlight remained on Luiz Inácio Lula da Silva’s re-election and the question of how Brazil will balance its geopolitical relationships with China and the US.
Macroeconomic data painted a mixed picture. The Conference Board’s consumer confidence index rose to 91.7, significantly exceeding expectations and pointing to a meaningful improvement in household sentiment. However, while headline durable goods orders increased by 1.8% in September, measures excluding the more volatile transportation components painted a weaker picture. In the housing market, new home sales declined on a monthly basis, while house price data also signaled a monthly contraction. Overall, the data did not indicate a meaningful economic slowdown, but continued to send mixed signals about the underlying strength of the economy.
US short-term yields edged higher, German bond yields declined, while the Hungarian forint remained stable
US Treasury markets saw mixed moves ahead of the Fed’s rate decision. The 2-year yield rose 3 basis points to 4.74%, while the 10-year yield closed unchanged at 4.99%. A stronger-than-expected increase in the Conference Board consumer confidence index exerted modest upward pressure on short-term yields, while investors continued to price in the possibility of further Fed action later this year. Markets still overwhelmingly expect policymakers to leave interest rates unchanged at this meeting, although the prospect of an additional rate hike before year-end has not been fully ruled out. Investors also remain focused on longer-term inflation risks, the sizeable fiscal deficit, and the financing needs generated by ongoing AI-related investment.
In Europe, bond yields declined, with the German 2-year yield falling 3 basis points to 3.05%. Investors are now focused on Thursday’s ECB rate decision, where the benchmark interest rate is widely expected to remain unchanged. At the same time, developments in the Middle East continued to be a key driver of market sentiment. Oil prices corrected on Tuesday as diplomatic discussions involving Iran continued, with Brent settling at $113.88 per barrel and WTI closing at $99.90 per barrel. The EUR/USD exchange rate stood at 1.1124, while the US dollar was broadly unchanged against major currencies.
International bond market trends were also reflected in the Hungarian government bond market, where yields generally moved lower across the curve. Moves at the short end were modest, while yields declined more noticeably in the longer-tenor segment, with the 10-year benchmark yield falling 6 basis points to 5.69%. The Hungarian forint remained stable, trading around 366.73 against the euro and 329.72 versus the US dollar.
Today's highlights
AI-driven optimism also supported Asian equity markets, particularly the technology sector. Following strong earnings from South Korea’s SK Hynix, Japan’s Nikkei rose 1.3% and China’s CSI 300 gained 0.7%, while regional stock markets broadly traded in positive territory.
In India, telecom operator Reliance Jio soared 21% on its stock market debut following the country’s largest-ever IPO. As a result, the company reached a market valuation of approximately $131.5 billion, making it India’s second-largest listed company by market capitalization.
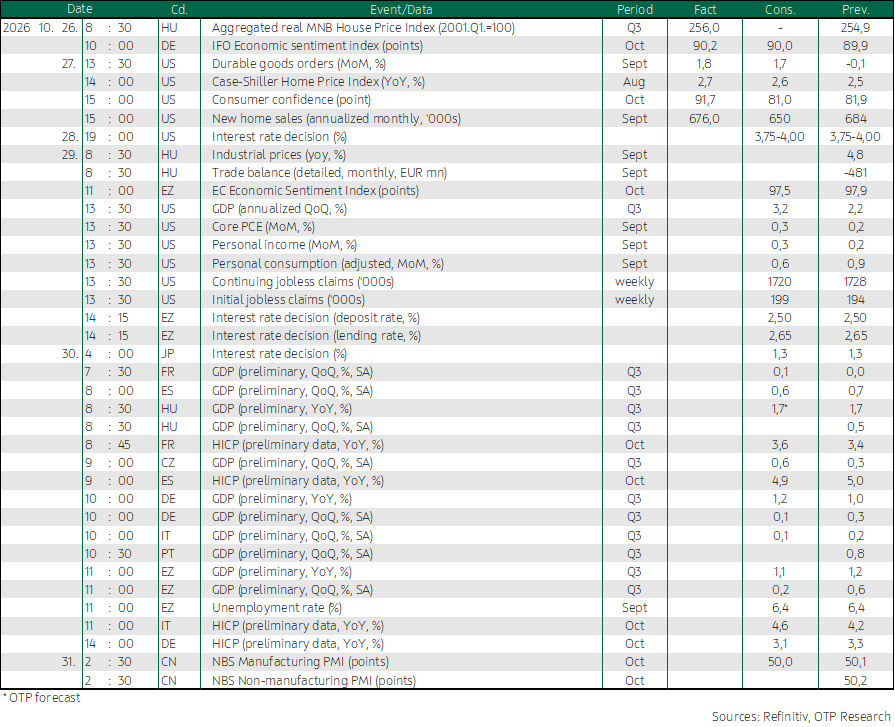
Alongside the Fed’s rate decision, investors will be closely watching corporate earnings releases today. In the US, Microsoft, Alphabet and, after the market close, Meta Platforms are scheduled to report, while in Europe UBS, Deutsche Börse and Mercedes-Benz will publish their quarterly results during the trading session.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more