
OTP Morning Brief: News of Anthropic's potential stock market debut drove the rally in the technology sector
Related content
OTP Morning Brief: Oil and gas prices hit multi-year highs as equity markets slide
By the end of last week, oil prices had climbed to their highest levels since spring, while European natural gas prices approached levels last seen in late 2022, driven by escalating tensions in the Middle East. Equity markets also turned lower by the end of the week: while the energy sector benefited from higher commodity prices and soared to record highs, all other sectors came under pressure. In the bond market, the US 10-year Treasury yield dipped back below 5%, while its German counterpart closed at a one-and-a-half-month low. French, Mediterranean, and CEE bond yields showed little movement on Friday, but over the course of the week they rose noticeably overall.
OTP Morning Brief: Earnings season continues to drive equities higher, while the French 10-year yield climbs above 5%
Stock markets moved higher yesterday in both Europe and the US, with technology stocks leading the gains on both sides of the Atlantic. Individual earnings reports released so far do not indicate that the AI investment boom is set to slow in the coming months. French financial indicators, however, are coming under increasing pressure from social and political uncertainty across both the corporate and public sectors: while French retail giant Carrefour issued a profit warning due to the unrest, French long-term bond yields soared to their highest level since 2002. The rise in yields also affected other countries, with the yield on 10-year Hungarian government bonds moving higher as well.
Major European and US equity indices moved higher. In Europe, the defence sector led the gains, while technology stocks spearheaded the rally in the US. Anthropic submitted documentation for its stock market listing, putting the spotlight back on AI investment spending. Saudi Arabia and Iran held talks aimed at easing tensions between the two countries, while crude oil prices edged lower. There was little movement in developed bond markets, with investors focusing on the ECB's and the Fed's interest rate decisions due later this week. The US dollar extended its gains against the euro. The BUX climbed by more than 1% yesterday. The Hungarian forint continued to weaken against the major currencies. The earnings season continues today with major names such as Coca-Cola and Boeing reporting results.
Leading European indices advanced; the BUX also closed in positive territory
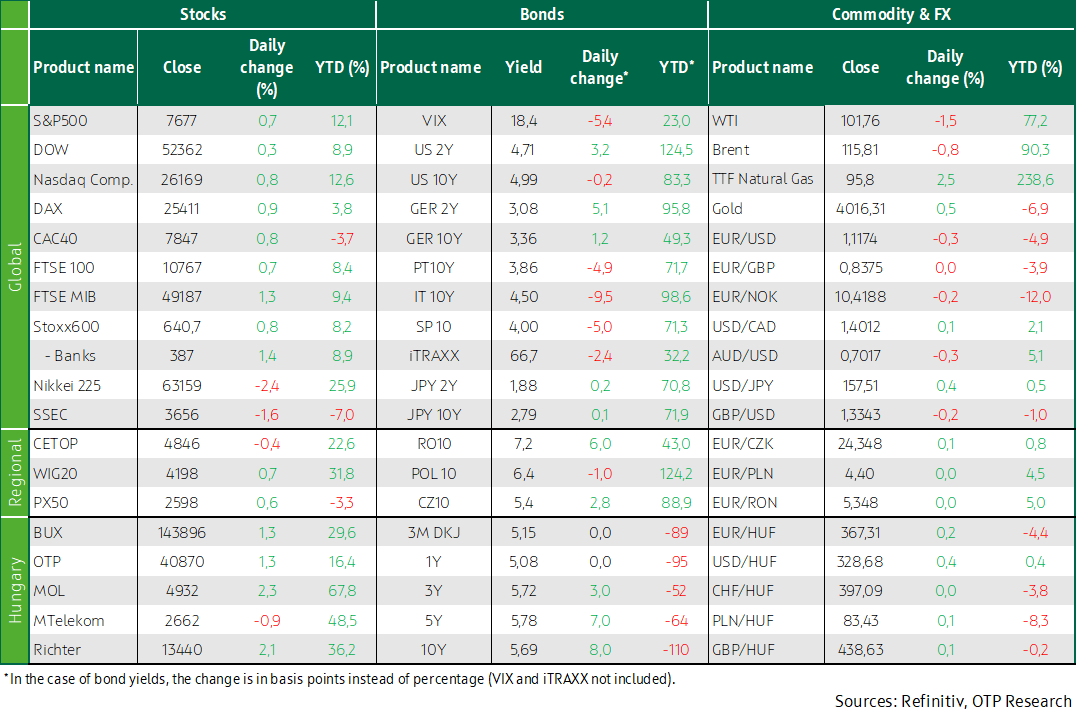
Leading European equity indices started the week on a positive note, as encouraging corporate news helped offset concerns over elevated energy prices and geopolitical tensions. The pan-European Stoxx 600 advanced 0.8%, with defence stocks leading sectoral gains, rising 2.6% after both the European Union and the United Kingdom reaffirmed their commitment to supporting Ukraine, while investors increasingly expect NATO members to maintain higher defence spending over the long term. Among individual stocks, technology services provider Computacenter (+13.1%) and biotech company Genmab (+12.1%) were the top performers. Computacenter benefited from its fourth upward revision of annual profit guidance this year, while Genmab gained following positive trial results for an experimental cancer treatment.
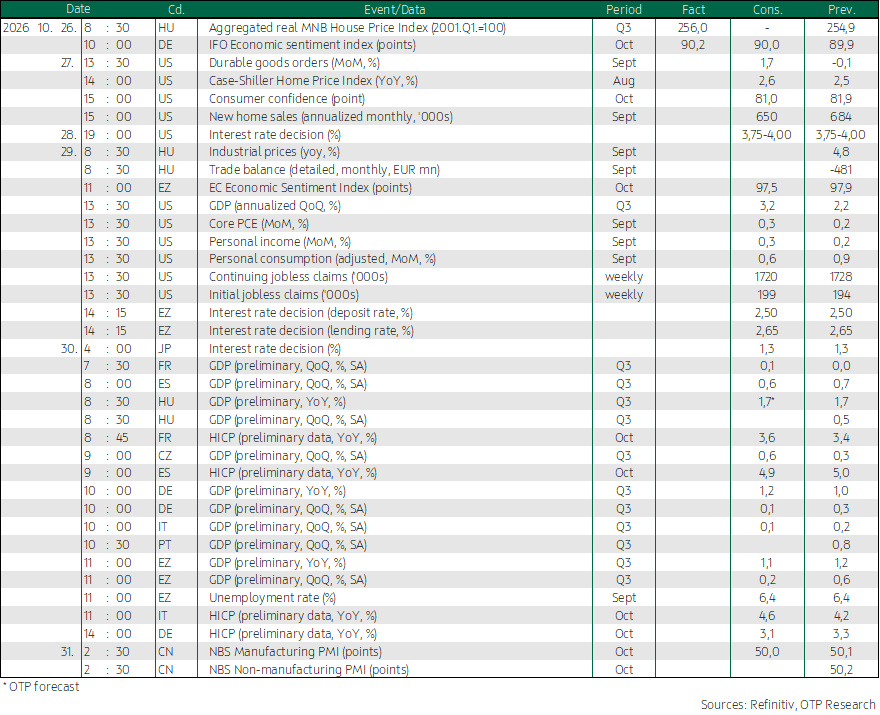
On the data front, Germany’s October economic sentiment index surprised to the upside, but investors are now primarily focused on the interest rate decisions due later this week, as well as the release of third-quarter growth figures.
Central and Eastern European equities closed higher on Monday, with the BUX leading the region's gains after advancing 1.3%. Hungary's blue-chip stocks delivered a mixed performance, with Magyar Telekom being the only major constituent to finish the session in negative territory.
The TTF benchmark on the Dutch gas exchange climbed above EUR 95/MWh, bringing its gain since the start of October to more than 30%.
News related to Anthropic's stock market debut fueled gains on Wall Street, while crude oil prices edged lower
The major Wall Street indices also closed higher on Monday, as Anthropic’s submission of documents related to its stock market debut redirected investor attention towards artificial intelligence-linked stocks. The Dow gained 0.3%, the S&P 500 rose 0.7%, while the technology-heavy NASDAQ advanced 0.8%, with the latter two indices thereby snapping their two-week losing streak. At the sector level, technology led the gains, rising 1.5%, while the Philadelphia Semiconductor Index, which tracks semiconductor manufacturers, climbed 2.8%. Among AI-related companies, Lumentum surged 8.2% and Coherent rose 5.8%, while Tesla shares jumped 5.2% following an upgrade by Barclays. In contrast, Meta fell 1.9% after the company announced plans for a share offering of up to USD 95 billion to finance infrastructure investments related to AI development.
Investor focus is now shifting beyond Anthropic’s stock market debut to the key events later this week. These include the Fed’s interest rate decision, due on Wednesday, Thursday’s growth and inflation data releases, and earnings reports from major technology companies. More than one-third of S&P 500 constituents are scheduled to report results this week, including Alphabet, Microsoft and Amazon.
Crude oil prices eased by around 1% after Saudi Arabia’s defence minister held talks with the Iranian leadership in Tehran aimed at reducing tensions between the two countries. Even so, both Brent and WTI crude remain above USD 100 per barrel, having risen by more than 10% since the start of October. The latest talks do not, however, signal any de-escalation in the attacks on Saudi Arabia carried out by Yemen’s Houthi rebels in recent weeks, with the group announcing further missile and drone strikes against Saudi targets on Monday. Investors remain concerned that any major attack on Saudi oil production and refining infrastructure could trigger supply disruptions at a time when global inventories are already low.
Developed bond and currency markets await the Fed’s and the ECB’s policy meetings; the Hungarian forint continued to weaken against major currencies
All eyes in developed bond markets are now on this week’s policy meetings of the ECB and the Fed. The US 10-year Treasury yield continued to hover near 5%, while the German 10-year Bund yield declined to around 3.35% from above 3.6% at the end of September. The French 10-year yield also moved lower despite concerns related to recent street unrest and the country’s elevated budget deficit, falling back to just below the 5% mark.
The US dollar continued to strengthen against the euro, with the EUR/USD exchange rate hovering around 1.117 ahead of this week’s policy meetings of the Fed and the ECB.
There was little movement at the short end of the Hungarian yield curve, while the long end moved 3-8 basis points higher during Monday's trading session. The Hungarian forint continued to weaken against major currencies, with EUR/HUF rising above 367 and USD/HUF climbing past 328, its highest level in three weeks.
Today's highlights
Asia-Pacific equities managed to ride the wave of optimism generated by yesterday’s strong performance in the technology sector. Equity index futures point to a mixed, though predominantly negative, open in both Europe and the US. Crude oil prices moved lower this morning.
HSBC released its quarterly earnings report, with earnings per share and revenue both missing expectations, while pre-tax profit came in broadly in line with forecasts. HSBC also announced that it could repurchase up to USD 1 billion worth of its own shares by year-end.
The Government Debt Management Agency (GDMA) will offer HUF 30 billion worth of discount treasury bills at auction today.
In the US, September durable goods orders are due for release today. After two months of robust growth, orders were broadly flat in August, while the market expects a month-on-month rebound in the latest reading. Core durable goods orders, which exclude transportation and defence equipment, continued to rise in August and may have extended their gains in September. Meanwhile, the Conference Board’s consumer confidence indicator, also scheduled for release today, is expected to show a further deterioration in US consumer sentiment in October, following a decline in September driven mainly by elevated inflation and concerns about labour market conditions and the economic outlook.
Among others, Visa, Coca-Cola, Novartis and Boeing are scheduled to report quarterly earnings today.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more