
OTP Morning Brief: Earnings season continues to drive equities higher, while the French 10-year yield climbs above 5%
Related content
OTP Morning Brief: OTP reported earnings above analysts' expectations this morning
The US 10-year Treasury yield briefly climbed above 5% on Tuesday following the release of stronger-than-expected inflation data. Expectations for further Fed rate hikes strengthened, supported not only by the latest inflation data and last week’s exceptionally strong labour market figures, but also by hawkish comments from central bank policymakers. US equity indices weakened in the face of rising bond yields, with the IT sector emerging as the day's worst performer. In Europe, steadily declining oil prices provided further support to equity markets. The US dollar strengthened, with EUR/USD falling to 1.116. In Hungary, CPI accelerated to 2.0% in October, while core CPI rose to 2.1%. Hungarian long-term bond yields, however, edged lower, with the benchmark 10-year yield declining to 5.26%, its lowest level in nearly four months. The forint weakened alongside other regional currencies, albeit to a greater extent, with EUR/HUF edging up to 364.5. Investor attention is likely to focus on OTP’s Q3 earnings report released this morning.
OTP Morning Brief: Lower oil prices underpinned investor optimism
Major European and Wall Street indices closed Monday's trading session in positive territory, with gains broad-based across sectors. The positive sentiment was driven by lower oil prices after Donald Trump stated that a renewed strike against Iran was highly unlikely, provided there is progress in the negotiations. We saw a rebound in the technology sector after last week's sharp sell-off. The dollar weakened against the euro. The BUX climbed 1.8%, while all major Hungarian blue-chip stocks finished the session higher. The forint strengthened against the major currencies. October CPI figures for both Hungary and the US are due for release today.
Stock markets moved higher yesterday in both Europe and the US, with technology stocks leading the gains on both sides of the Atlantic. Individual earnings reports released so far do not indicate that the AI investment boom is set to slow in the coming months. French financial indicators, however, are coming under increasing pressure from social and political uncertainty across both the corporate and public sectors: while French retail giant Carrefour issued a profit warning due to the unrest, French long-term bond yields soared to their highest level since 2002. The rise in yields also affected other countries, with the yield on 10-year Hungarian government bonds moving higher as well.
European markets posted strong gains, with the Budapest Stock Exchange standing out as the only exception
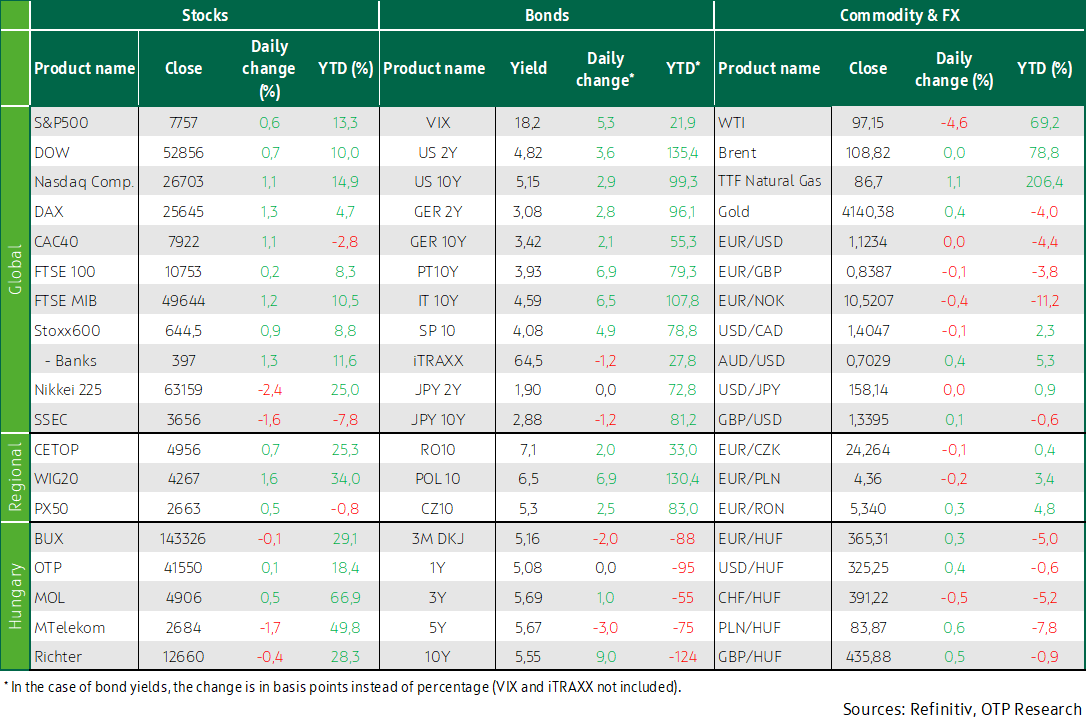
European equity markets clawed back the losses accumulated during the first two trading days of the week on Wednesday. The STOXX 600 rose 0.9%, effectively returning to last Friday’s closing level, which had marked a one-and-a-half-month high. Most sectors posted gains, with technology stocks leading the advance (+2.1%), driven primarily by Dutch semiconductor equipment maker ASML (+2.6%) and German software giant SAP (+1.6%). The latter also released its Q3 earnings report yesterday, reporting sales and profits above market expectations. Automakers, however, fell 1.7%, while telecommunications stocks lost an average of 0.5% amid persistent weakness across the sector globally. The clear laggard of the day was French retail chain Carrefour, whose share price plunged 13.8% after management accompanied its Q3 earnings release with a profit warning. The company said that this year's operating profit could decline by EUR 80-200 million, equivalent to roughly 5-10% of last year's annual figure, due to the ongoing unrest in France, during which around 50 of its stores have been targeted.
No major macroeconomic data releases came out of Western Europe yesterday, with the exception of the UK CPI report, which continued to signal accelerating price growth. Headline CPI rose to 3.5% YoY in October from 3.1% in the previous month, although the reading did not significantly exceed market expectations.
Regional equity markets mostly moved higher, with the Prague Stock Exchange gaining 0.5% and the Warsaw market advancing 1.6%, the latter matching its all-time high once again. The BUX delivered a more subdued performance, ending Wednesday down 0.1%. The decline was led by Magyar Telekom (-1.7%), in line with its European and US telecom peers, while MOL and OTP still managed to post modest gains of 0.5% and 0.1%, respectively.
US markets also advanced, with both Tesla and Meta delivering strong earnings results
US indices also moved higher on Wednesday, with the Dow gaining 0.7%, the S&P 500 rising 0.6%, and the Nasdaq advancing 1.1%. Technology stocks once again led the market higher. SpaceX surged 7.8%, partly continuing the momentum generated by its earnings release on Tuesday. The stock also appeared to benefit from Tesla’s stronger-than-expected quarterly results, which helped its shares climb 3.4%, as well as comments from Elon Musk suggesting that a merger between the two companies should not be ruled out. After the closing bell, Meta also reported results that exceeded expectations. The company’s Q3 revenue rose 26% year-on-year, while profit improved significantly compared to the same period last year, despite setting aside around USD 10 billion for potential settlements related to lawsuits concerning the mental health of young users. Server manufacturer Super Micro, which also reported earnings yesterday, saw its share price soar 9.6% after highlighting stronger demand for AI infrastructure and forecasting higher revenue for Q1 2027.
No major macroeconomic data releases were published in the US on Wednesday.
Bond yields edge higher, but the French 10-year yield tops 5%, reaching a 24-year high
US Treasury yields were broadly unchanged on Wednesday, with the 2-year yield edging up 2 basis points to 4.81%, while the 10-year remained at Tuesday’s level of 5.12%. German 10-year Bund yields also increased only marginally, rising 2 basis points to 3.42%, while comparable Italian yields climbed 7 basis points to 4.59%. French 10-year government bond yields rose by a similar magnitude, adding 9 basis points, but this move was enough to push them above the psychologically important 5% threshold, a level not seen since 2002. The development clearly reflects mounting concerns over the unrest in France, fiscal challenges, and uncertainty surrounding next year’s presidential election, which is not expected to be particularly favourable for mainstream candidates. French yields have not only widened to their largest spread over German Bunds since 2011, reaching 157 basis points, but are now also trading at a premium of more than 40 basis points over Italian government bonds despite France maintaining a credit rating that is three to four notches higher. Such a situation is unprecedented. Government bond yields also moved higher across Central and Eastern Europe yesterday, with Poland’s 10-year yield rising 7 basis points to 6.48%, Hungary’s increasing 9 basis points to 5.55%, and the Czech equivalent adding a more modest 2 basis points to 5.33%.
Brent crude rose 0.9% yesterday, while WTI was broadly unchanged. Meanwhile, TTF natural gas prices increased by 0.8%.
There were no major moves in currency markets either. The US dollar was little changed against the euro, while the Hungarian forint weakened by 0.3% versus the common currency. Meanwhile, both the Polish zloty and the Czech koruna posted modest gains, appreciating by 0.2% and 0.1%, respectively.
Today's highlights
Asian markets painted a grim picture on Thursday morning, with the Hang Seng down 3.1%, the Nikkei falling 2.4%, and South Korea’s KOSPI sliding 3.9%. Technology stocks were leading the sell-off.
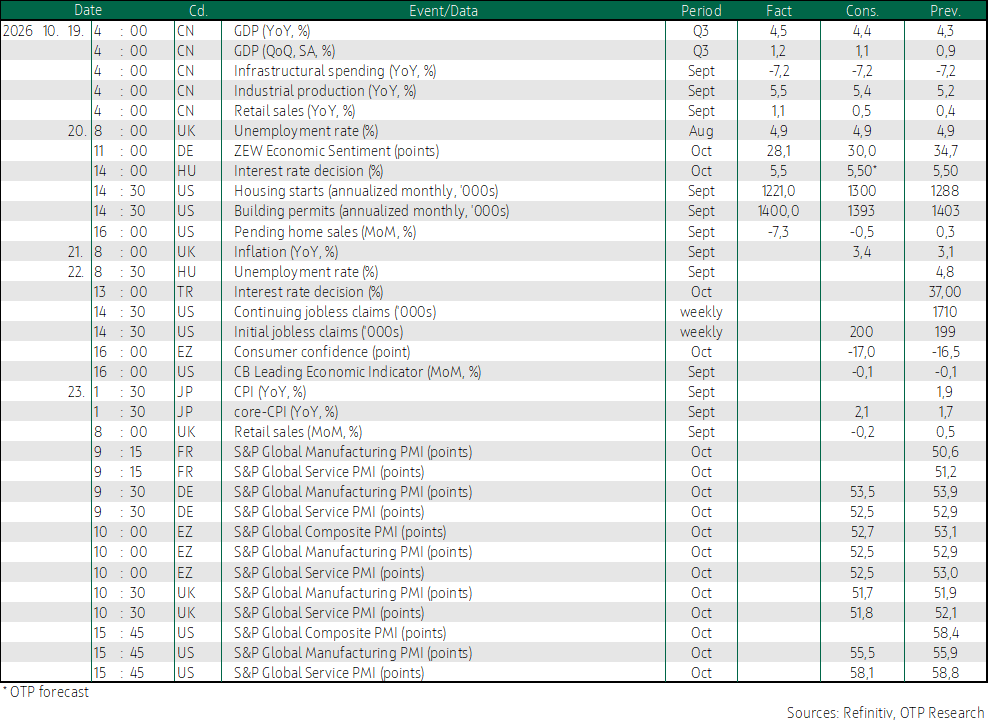
No major macroeconomic releases are scheduled for today. However, on Friday, October 23, S&P Global will publish its Purchasing Managers’ Indices (PMIs) for the euro area, Germany, and France. Investors will also receive Japan’s September inflation data, while Moody’s is set to review France’s sovereign credit rating.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more