
OTP Morning Brief: MNB keeps base rate unchanged at 5.5%, lowers inflation target from 2028 onwards
Related content
OTP Morning Brief: Oil prices rise, the technology sector struggles, and the earnings season gains momentum
The major European stock indices closed Monday's session in positive territory, with banks and utilities leading the advance. The BUX gained 0.9%, while Hungary’s blue-chip stocks delivered a mixed performance. TTF gas prices remain above EUR 84/MWh. Wall Street indices delivered a mixed performance yesterday, with the technology sector under pressure and semiconductor manufacturers posting declines. We saw an approximately 2% rise in crude oil prices. The euro weakened against the dollar as investors grew concerned about France’s fiscal position and the outlook for next year’s presidential election. The EUR/HUF exchange rate fell below 365. The earnings season continues today with reports from major companies.
OTP Morning Brief: Modest gains in equities, stronger rise in energy prices
Both US and European equity markets posted modest gains last Friday. The BUX largely recouped the losses accumulated over the previous week. There was no positive turnaround in energy prices, however: oil prices rose both on the last trading day of the week and over the week as a whole, while European natural gas prices surged above EUR 82/MWh, reaching levels rarely seen since 2022. The US-Russia diesel agreement announced over the weekend is also unlikely to bring meaningful relief to the market, as the volumes involved are negligible relative to global demand. Following the sharp rise in yields seen in September, October has so far been characterized by ongoing uncertainty on bond markets as investors continue to search for direction.
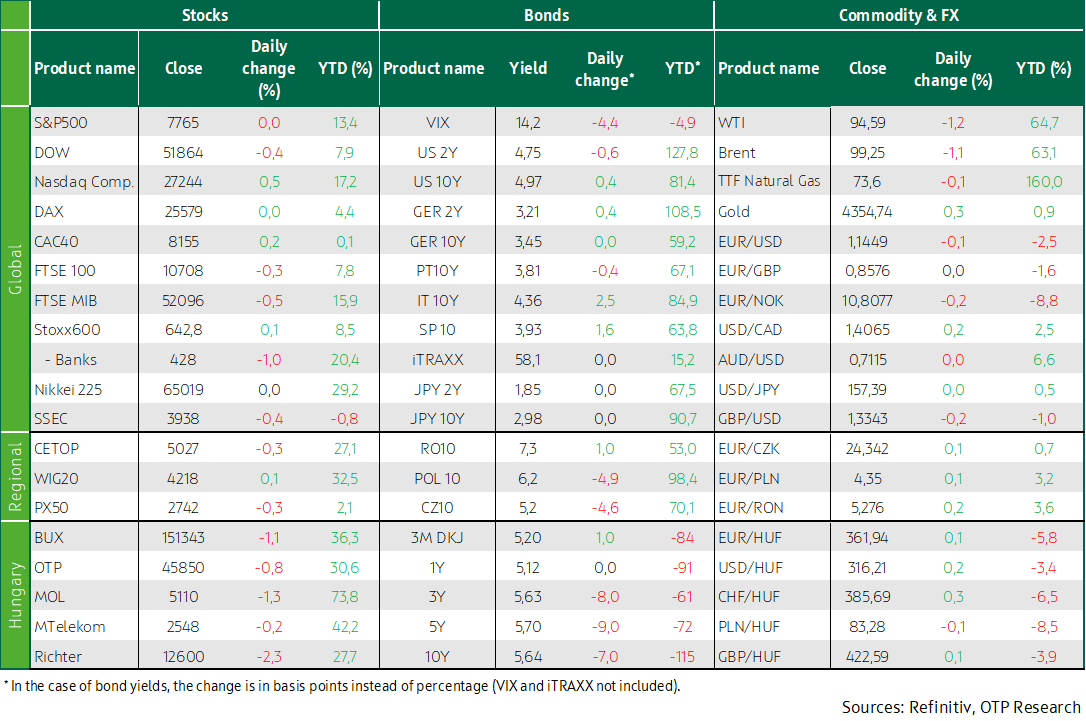
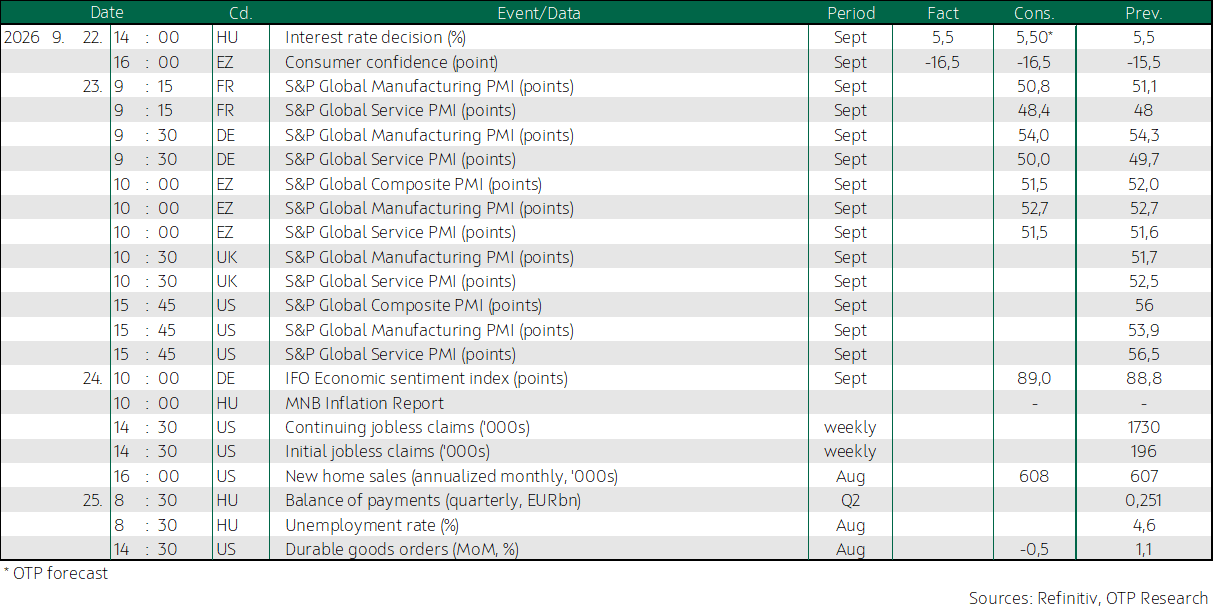
Tuesday's trading session brought only modest moves across Western European markets. The MNB kept its base rate unchanged at 5.5%, in line with market expectations. The inflation target will be lowered to 2.5% from January 2028. Wall Street indices closed mixed, despite gains in artificial intelligence-related stocks. The decline in crude oil prices extended for a fifth consecutive day. Developed market bond yields were broadly unchanged and showed little meaningful movement. The Hungarian 10-year government bond yield eased to 5.64%. Investors will be closely watching the September PMI releases from Europe and the US today. Additionally, Chinese President Xi Jinping's visit to the US begins today.
Modest moves in Western Europe as MNB leaves rates unchanged
After Monday's strong rally, Tuesday's trading session brought only modest moves across the major Western European stock markets. The Stoxx 600 rose 0.1%, while the DAX was little changed, the CAC 40 gained 0.2%, and the FTSE 100 slipped 0.3%. Technology stocks advanced 1.5%, tracking the performance of the Nasdaq. Shares of Kingfisher, the UK home improvement retailer, soared more than 12% after the company raised its full-year profit guidance. However, broader market gains were capped by a 1% decline in banking stocks. Telecommunications shares fell 2.1%, with Ericsson down 3.8% after Morgan Stanley downgraded the Swedish telecom equipment maker's stock.
In Hungary, the MNB kept its base rate unchanged at 5.5% at yesterday's policy meeting, in line with market expectations. The Monetary Council unanimously decided to lower the inflation target to 2.5%, effective from January 1, 2028. Starting in 2027, the central bank will hold eight scheduled rate-setting meetings per year. The MNB left its 2026 CPI forecast unchanged at 1.8%. At the same time, it raised its 2027 inflation projection from 2.3% to 3.1%. According to the updated forecast, economic growth is expected to reach 1.8%, 2.9%, and 2.8% in 2026, 2027, and 2028, respectively.
MOL announced on Tuesday that it had completed the restoration of the AV3 unit at its Duna Refinery, which was damaged in a fire last October. This paves the way for the gradual restart of production, allowing the Százhalombatta refinery to return to full operating capacity.
The BUX fell 1.1% on Tuesday. Among the blue chips, Richter led the declines, dropping 2.3%, while shares of OTP, MOL, and Magyar Telekom also closed lower. Across the region, the PX 50 slipped 0.3%, while the WIG20 rose 0.1%.
The price of TTF natural gas fell to €73-74/MWh during the first two trading days of the week, down from levels that had exceeded €80/MWh last week.
AI-related chip stocks once again drove US markets higher
The Nasdaq closed at a record high on Tuesday, rising 0.5%, supported by gains in Micron Technology (+5%), SanDisk (+7%), and other artificial intelligence-related stocks. The S&P 500 was little changed, while the Dow Jones fell 0.4%. Investor attention focused on Meta Platforms' AI-powered assistant, which is capable of sending emails and executing transactions on behalf of users. The positive reception of the AI assistant, called Muse, in recent days has provided significant momentum for AI-related chip stocks. The financial sector posted the weakest performance, declining 1.7%. Among major banks, both JPMorgan Chase and Wells Fargo fell by more than 3%.
Xi Jinping, President of China, is set to arrive in Washington today, with official talks scheduled to begin on Thursday. The agenda is expected to focus on the trade truce expiring on November 10, US arms sales to Taiwan, developments in artificial intelligence, and the conflict in the Middle East. The most tangible outcome is likely to be a decision on extending the trade truce.
The decline in crude oil prices extended for a fifth consecutive day, with Brent crude closing below $100 per barrel for the first time since September 8.
Developed market bond yields remained broadly unchanged
Oil prices ultimately closed lower on Tuesday after US President Donald Trump told reporters at the United Nations that US officials had held a “very good” three-hour meeting with the Iranian delegation earlier in the day. The US 10-year Treasury yield edged higher on Tuesday. Meanwhile, the yield on the German 10-year government bond was unchanged at 3.45%, after declining by 7 basis points on Monday amid falling energy prices.
After a volatile trading session, the Hungarian forint closed 0.1% weaker against the euro at 361.94. During the MNB's press conference, the exchange rate briefly strengthened below the 360 level. The Hungarian 10-year government bond yield fell by 7 basis points to 5.64%. Amid nearly twofold oversubscription, the AKK sold HUF 36.5 billion of discount treasury bills maturing in January at an average yield of 5.21%. In addition to switch auctions, the government debt manager will offer HUF 20 billion of discount treasury bills maturing in April today.
Today's highlights
After several days of market closure, the Nikkei will reopen tomorrow for the first time since Friday. Approaching the close, South Korea's KOSPI was up 0.5%, while China's SSE Composite was down 0.4% and Hong Kong's Hang Seng was lower by 0.8%.
Investors will be closely watching the September PMI releases from Europe and the US today. In addition, Chinese President Xi Jinping's visit to the US begins today.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more