
OTP Morning Brief: Both the US and Hungarian finance ministries made important announcements
Related content
OTP Morning Brief: Rate hike expectations strengthened across developed markets
The escalation of the Middle East conflict pushed Brent and WTI prices above USD 100 per barrel. The European TTF benchmark climbed above EUR 80/MWh. The Friday rebound in developed equity markets was not enough to offset the losses accumulated earlier in the week. The BUX advanced both on Friday and on a weekly basis. Developed market long-term bond yields reached multi-year highs. The US dollar strengthened against the euro. The long end of the Hungarian yield curve shifted higher, while the forint weakened against major currencies. The week's most anticipated event will be the Fed's policy meeting, while the Bank of England and the Bank of Japan will also announce their interest rate decisions.
OTP Morning Brief: Developed market yields surged significantly
European equities declined, the ECB raised its key interest rates by 25 basis points as expected, while the Turkish central bank left its policy rate unchanged. Wall Street indices extended their decline, while oil prices continued to rise. In the US, initial jobless claims edged down, while producer price inflation accelerated in line with expectations. Developed market yields surged significantly, despite the US Treasury's buybacks of longer-dated securities. Today's primary focus will be on US CPI data, while tomorrow the University of Michigan Consumer Sentiment Index and the US federal budget balance for August are due for release.
Monday was quiet in terms of macroeconomic data releases. US indices closed mixed, weighed down by the weak performance of the technology sector. US Treasury Secretary Scott Bessent announced further tightening of sanctions against Iran, primarily through the expanded use of secondary sanctions. Brent crude prices declined after six consecutive days of gains. The pan-European Stoxx 600 was virtually unchanged on Monday. The Hungarian government is planning a budget deficit equivalent to 7.5% of GDP for 2026. US long-term yields edged lower. In Hungary, markets are focused on today's interest rate decision by the MNB.
The pan-European Stoxx 600 was virtually unchanged on Monday
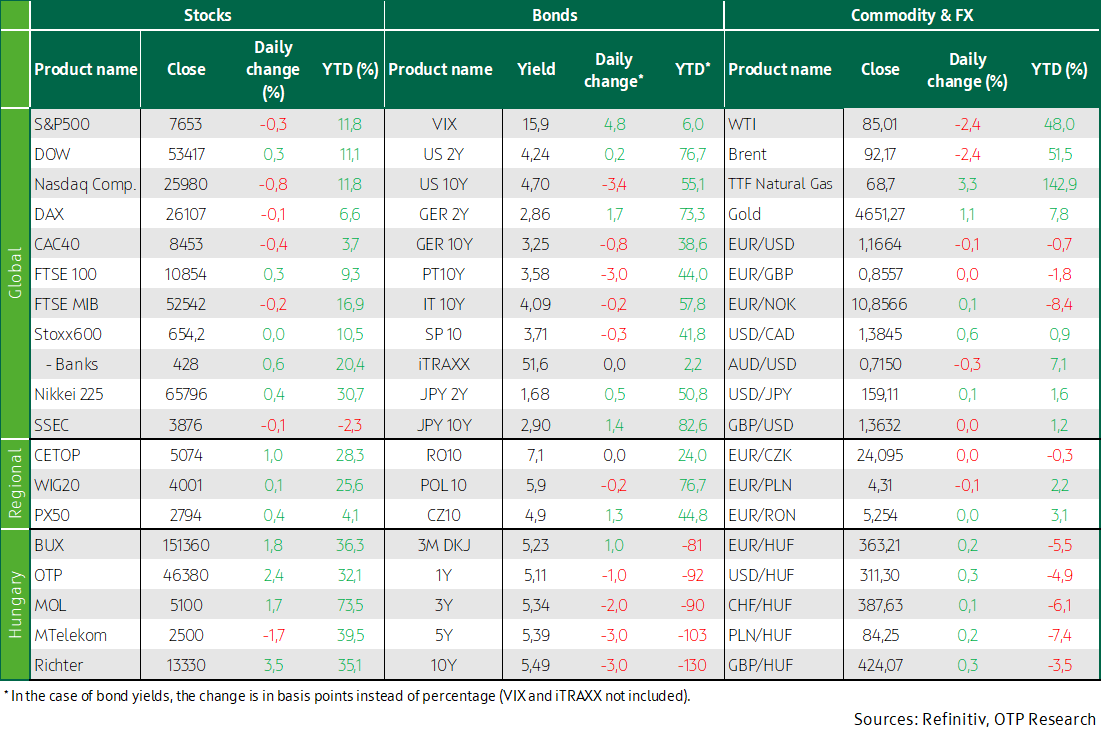
The pan-European Stoxx 600 was virtually unchanged on Monday. The DAX slipped 0.1%, while the CAC 40 fell 0.4%, whereas the FTSE 100 advanced 0.3%. Travel and leisure stocks gained on the back of lower oil prices, while the energy sector was the worst performer, declining 1.6%. Shares of automakers and auto parts suppliers dropped 1%, despite July data pointing to a recovery in European electric vehicle sales. The technology sector weakened 0.8% as investors awaited Nvidia’s earnings release on Wednesday.
With a 1.8% gain, the BUX outperformed both Western European and regional markets, as Monday marked the first trading session following the long weekend. Among the blue chips, OTP rose 2.4%, Richter advanced 3.5%, and Mol gained 1.7%, while Magyar Telekom lost 1.7% of its value. Elsewhere in the region, the Czech PX50 added 0.4%, and Poland’s WIG20 edged up 0.1%.
According to a statement released by the Ministry of Finance yesterday, the Hungarian government will submit its revised 2026 budget by August 31 at the latest. In line with the fiscal review published in July, the ministry stated that without the change in government and the measures introduced thereafter, the actual budget deficit would reach 8.3% of GDP. Measures implemented so far, including the agreement on EU funds, the restructuring of public interest asset management foundations, and declining government bond yields, have reduced the deficit to 7.5% of GDP. The government intends to incorporate this 7.5% deficit target into the revised budget. Accordingly, government debt as a share of GDP would increase from 74.6% to 77.5%. The statement noted that the debt ratio is expected to return to a declining path from 2027 onward. The draft 2027 budget is scheduled to be presented in October, together with the medium-term macroeconomic plan.
The price of European benchmark TTF natural gas rose a further 3.3%, reaching nearly EUR 69.
Wall Street indices closed mixed, weighed down by the weak performance of the technology sector
US stock indices closed mixed on Monday. The S&P 500 (-0.3%) and the Nasdaq Composite (-0.8%) moved lower, primarily due to weakness in technology stocks. Nvidia and Broadcom each fell nearly 3%, while Micron Technology dropped 5.8%. Texas Governor Greg Abbott, a Republican, voiced strong criticism of the AI industry after suspending approvals for grid connections for new data center projects. The criticism centered on the strain placed on the power grid and the sector’s deteriorating public perception. The industrial-heavy Dow Jones closed 0.3% higher.
US Treasury Secretary Scott Bessent announced further tightening of sanctions against Iran, primarily through the expanded use of secondary sanctions. He suggested that countries may have to choose between maintaining ties with Iran and preserving access to the US dollar-based financial system. For now, details remain limited, with no clarity on which countries would be affected or when the new measures might take effect. It remains uncertain to what extent the US is willing to risk friction with China through additional sanctions, such as targeting Chinese banks, especially after Beijing demonstrated last year that restrictions on rare earth exports could exert meaningful pressure on the US. Moreover, a presidential-level meeting between the two powers is expected next month, which may encourage a more cautious approach from Washington. After six consecutive days of gains, Brent crude prices declined again, falling 2.4% to USD 92.17 per barrel.
US President Donald Trump warned that tariffs on passenger vehicles, trucks, and automotive parts imported from Canada could increase to 50% from January 1, 2027, following the breakdown of trade negotiations over the weekend. The announcement weighed on automaker stocks, with Ford falling 3.3% and General Motors declining 1.1%.
Following a 1.1% gain on Monday, gold has now risen by more than 15% in August.
US long-term yields edged lower
US Treasury yields moved lower on Monday after reports emerged that the Treasury Department may finance an expansion of its bond buyback program using its cash balance. In addition, sentiment in the bond market was supported by a decline in oil prices following six consecutive days of gains. The US 10-year Treasury yield fell 3.4 basis points to close at 4.70%. Looking ahead, Wednesday’s core PCE release and Federal Reserve Chair Kevin Warsh’s speech at Jackson Hole on Friday are likely to be key market-moving events for bond investors. Meanwhile, the German 10-year Bund yield eased by 1 basis point to 3.25%, remaining close to its highest level in 15 years.
The Hungarian forint weakened 0.2% against the euro to 363.21, modestly underperforming its regional peers. However, the currency showed little reaction to the Ministry of Finance’s announcement that this year’s budget deficit could reach 7.5% of GDP.
Today's highlights
Asian equity markets are trading mixed as the close approaches. Japan’s Nikkei is up 0.4%, while the KOSPI, Hang Seng, and Shanghai Composite (SSEC) are posting modest declines.
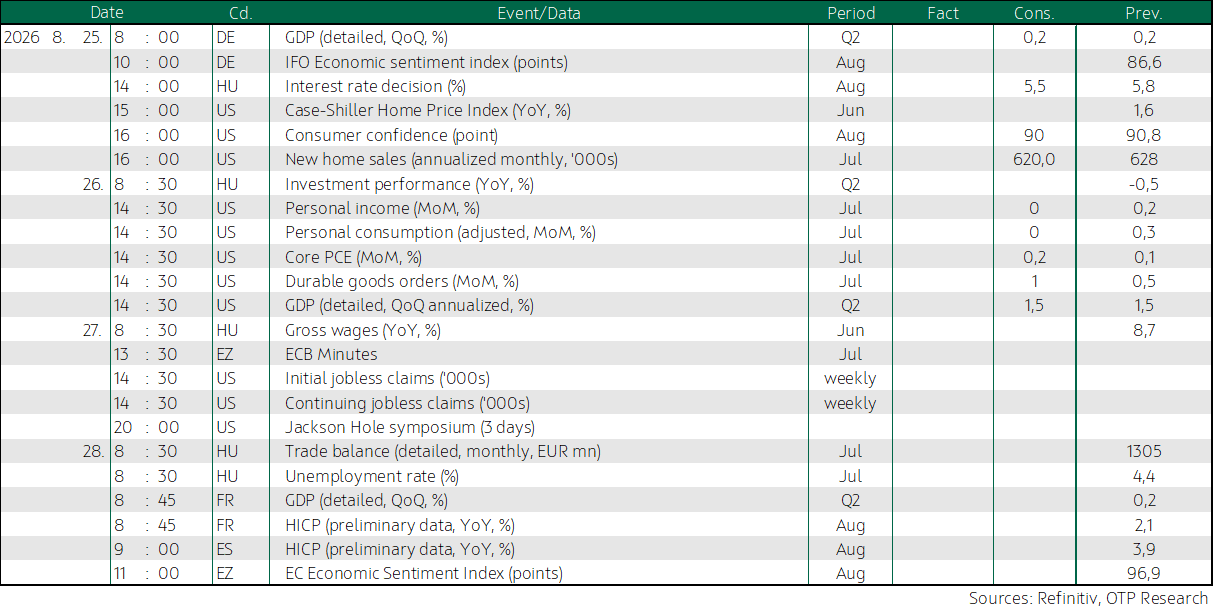
Today, Germany will release its detailed Q2 GDP figures and the August reading of the Ifo Business Climate Index. In Hungary, market participants will be closely watching the MNB’s interest rate decision.
Get more out of your investments!
Global Markets Services
OTP Global Markets offers a broad range of services in the field of local and international money and capital markets.
Read morePrivate Banking Services
Personal care and expertise with OTP Private Banking, along with the knowledge, security, and innovations of a multinational banking group.
Read more